CPKC's Freight Upturn Faces Proof Test As Coal Drag And Merger Noise Weigh On Shares
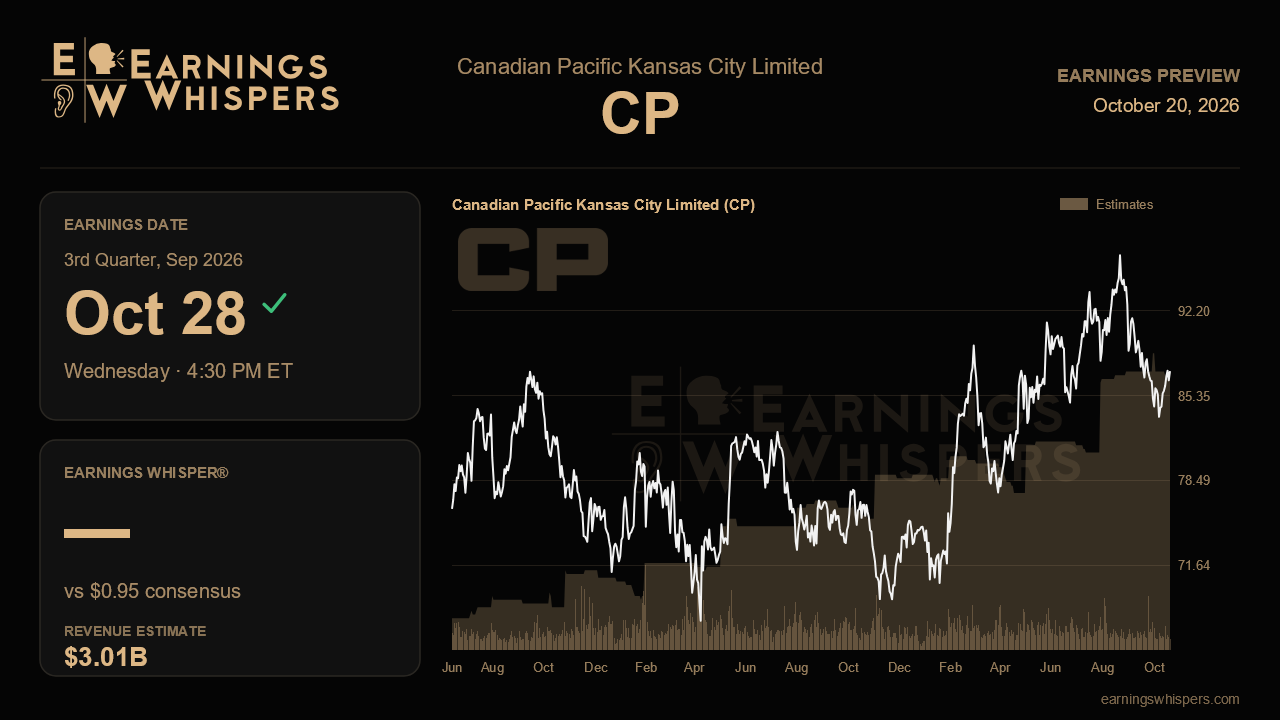
Three months ago, Canadian Pacific Kansas City's management did something it had not done since the 2023 merger: it described the freight economy as a tailwind rather than an obstacle. Volumes were said to be rising and accelerating, synergy targets moved higher, and the talk turned to operating leverage that was only beginning to show. The market has not bought it. The shares have slipped 5.4% since that report while the S&P 500 gained 3.6%. That gap sets up the third-quarter release, due after the close on October 28, as a test of whether the upcycle narrative is showing up in the numbers or remains mostly tone.
The Street is asking for a solid quarter on paper. Consensus calls for earnings of $0.95 a share on revenue of $3.01 billion, which would be growth of roughly 19% in earnings and 13% in sales from the year-ago $0.80 and $2.66 billion. Those are strong year-over-year figures, but the sequential picture is more modest. Revenue is expected to match last quarter's $3.01 billion, and earnings would rise only three cents from $0.92. In other words, analysts are not modeling the acceleration management described so much as assuming the business holds its ground. Management reaffirmed full-year guidance for low-double-digit EPS growth and mid-single-digit growth in revenue ton-miles rather than raising it, so a quarter running ahead of that annual pace would at least suggest the back half is carrying its weight.
The evidence that would validate last quarter's optimism is fairly specific. Volume growth should be visibly better than the 3% to 4% range cited on the call, with grain continuing to move south from the record Canadian harvest into Mexico and the southern U.S. Pricing should stay at or above the top of the 3% to 4% band, and any sign it is accelerating would support the idea of a firmer freight market. On the growth projects, the Mexico Midwest Express was running near 70% of capacity with a second train pair under discussion; a decision there would be a concrete sign of demand. The new SMX service with CSX was slated to ramp in the second half, and the Hapag-Lloyd and Loblaw intermodal renewals plus the AmeriCold reefer business should begin to show in intermodal and merchandise volumes. The synergy run-rate, now targeted at $1.4 billion to $1.5 billion by year end, needs steady progress toward that goal.
The challenges are equally clear. Coal was described as being at its worst in the second quarter, with a return to prior-year levels not expected until 2027, so any further deterioration would undercut the volume story. Refined fuel shipments into Mexico have been essentially absent, and tariffs on steel and lumber remain a drag on cross-border traffic. Fuel-surcharge lag and a weak Canadian dollar can distort the operating ratio and revenue per ton-mile, which means a headline miss could stem from noise rather than fundamentals. The buyback should start to help per-share earnings, offering some cushion.
Sentiment has cooled noticeably, swinging to mildly bearish from mildly bullish heading into the prior report, and the stock sits nearer the bottom of its post-earnings range of $83.25 to $96.90, just above its 200-day moving average. Management's attention to the proposed Union Pacific and Norfolk Southern combination, which it has called a distraction for customers, likely adds to the caution. That backdrop lowers the bar somewhat for a positive reaction.
Ultimately, the report will turn on whether volumes and pricing confirm a genuine upturn strong enough to outrun coal weakness and currency noise. If CPKC can show accelerating carloads, firm pricing and synergy progress alongside an improving operating ratio, the market's skepticism may prove overdone. If revenue stalls again at last quarter's level, the macro tailwind story will look more like hope than momentum.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-13 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-21 | |
| Sep-03 | |
| Sep-03 | |
| Aug-23 | |
| Aug-21 | |
| Aug-04 | |
| Jul-30 | |
| Jul-29 |
