Algoma Steel Faces Its Trough Quarter As EAF Unit 2 Startup And Liquidity Take Center Stage
Algoma Steel told investors last quarter that its transformation had entered its final stage, and then warned in the same breath that the coming quarter would be the ugliest of the year for volumes. That tension defines the report due after the close on October 28. The September quarter was flagged as the trough, with shipments expected to fall another 10% to 20% from the 181,000 tons shipped in the prior period because of scheduled maintenance and the tie-in of the second electric arc furnace. The real question is whether the underlying economics kept improving while the tonnage shrank, and whether the balance sheet held up long enough for the payoff to arrive.
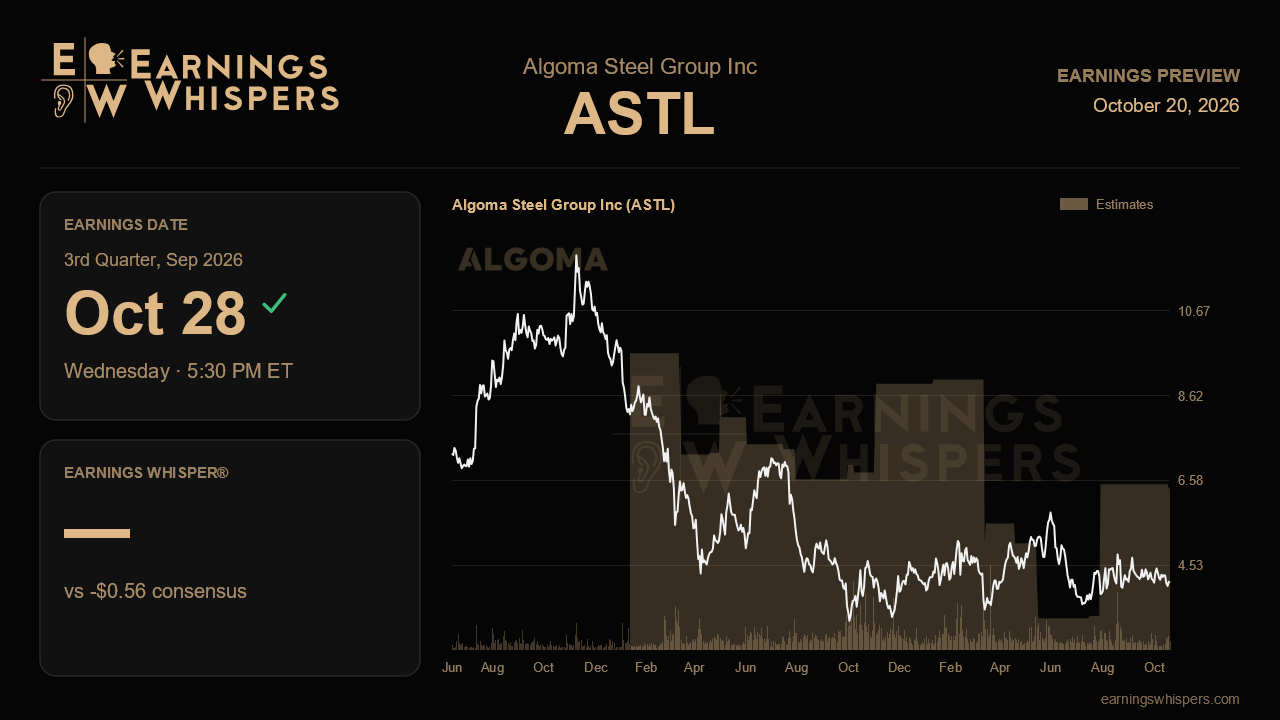
The Street is looking for a loss of $0.56 per share. That is a modestly smaller loss than the $0.64 reported last quarter, but a sharp reversal from the $0.12 profit earned a year ago, which is where the roughly 567% year-over-year decline comes from. Revenue tells a similar story of contraction: last quarter's $193.2 million was barely half of the $380.4 million booked in the same period a year earlier, and lower volumes make another weak top line likely. What stands out is that consensus assumes a narrower loss even though last quarter benefited from a $45 million final insurance payment that will not recur. In other words, analysts are betting that pricing, mix and lower tariff costs can more than offset lighter shipments and the disappearance of that one-time help. That is a reasonable but not trivial ask.
The evidence for that bet comes from the prior call. Average net sales realization climbed from $1,077 per ton two quarters back to $1,361 per ton, driven by a deliberate pivot toward plate, which set its second straight shipment record at 125,000 tons. Direct tariff costs fell to $18.7 million as Algoma kept pulling back from the U.S. market. Underlying EBITDA, stripped of insurance and a non-cash capacity-utilization adjustment, improved by about $33 million sequentially. Validation this quarter would mean realization holding near or above last quarter's level, plate share continuing to rise as a portion of a smaller pie, and tariff costs drifting lower again. A challenge would look like price erosion in an oversupplied Canadian coil market or plate volumes stalling during the maintenance outage. There is also a reporting wrinkle: the capacity-utilization cushion, which fell from $90.2 million to $54.7 million, is shrinking toward zero by the December quarter, so reported EBITDA faces a headwind that has nothing to do with operating performance.
Operationally, the single most important milestone is first steel from EAF Unit 2, which management said was only weeks away and expected within this quarter. Confirmation that it fired on schedule would underpin the reiterated target of a 1.5 to 2.0 million ton annual run rate exiting 2026 and the goal of roughly 600,000 tons of plate in 2027. Any slip would hit the core of the recovery thesis. Liquidity is the other swing factor. Cash slid to $62.6 million and available borrowing under the government-backed facility dropped from $417 million to $168 million over two quarters. Progress on the roughly $200 million tax refund would go a long way toward easing that strain, while unresolved supply-agreement litigation and the loss of the Hanwha beam-mill opportunity remain overhangs.
The market has not given Algoma much credit for its improving trajectory. Shares are up 2% since the last report, trailing the S&P 500 by about two percentage points, and at $4.13 they sit below the 200-day moving average of $4.42 and in the lower half of the post-earnings range of $3.64 to $5.07. Sentiment has slipped from mildly bullish to mildly bearish, suggesting expectations are tempered rather than elevated.
Ultimately, this report is less about the size of the loss than about whether the trough looks like a floor. If Unit 2 is producing steel, per-ton pricing is holding and the refund is in sight, the transformation story stays intact. If startup delays or cash burn dominate, the bear case gains the upper hand.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-15 | |
| Oct-01 | |
| Sep-02 | |
| Aug-17 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-16 | |
| Jun-30 | |
| Jun-23 | |
| Jun-04 | |
| May-13 | |
| May-12 | |
| Apr-30 |
