Alerus Earnings Preview: Can Loan Growth And Margins Offset Fading Accretion?
Alerus Financial heads into its third-quarter report having just cleared its biggest credit overhang, yet Wall Street is bracing for a noticeably smaller profit than the bank delivered three months ago. That gap is the story. Management spent last quarter raising its margin outlook for a fourth straight time and touting its strongest commercial pipeline in four years. Analysts, meanwhile, have penciled in a step down that reflects the headwinds management itself flagged. This report will show which of those forces carries more weight.
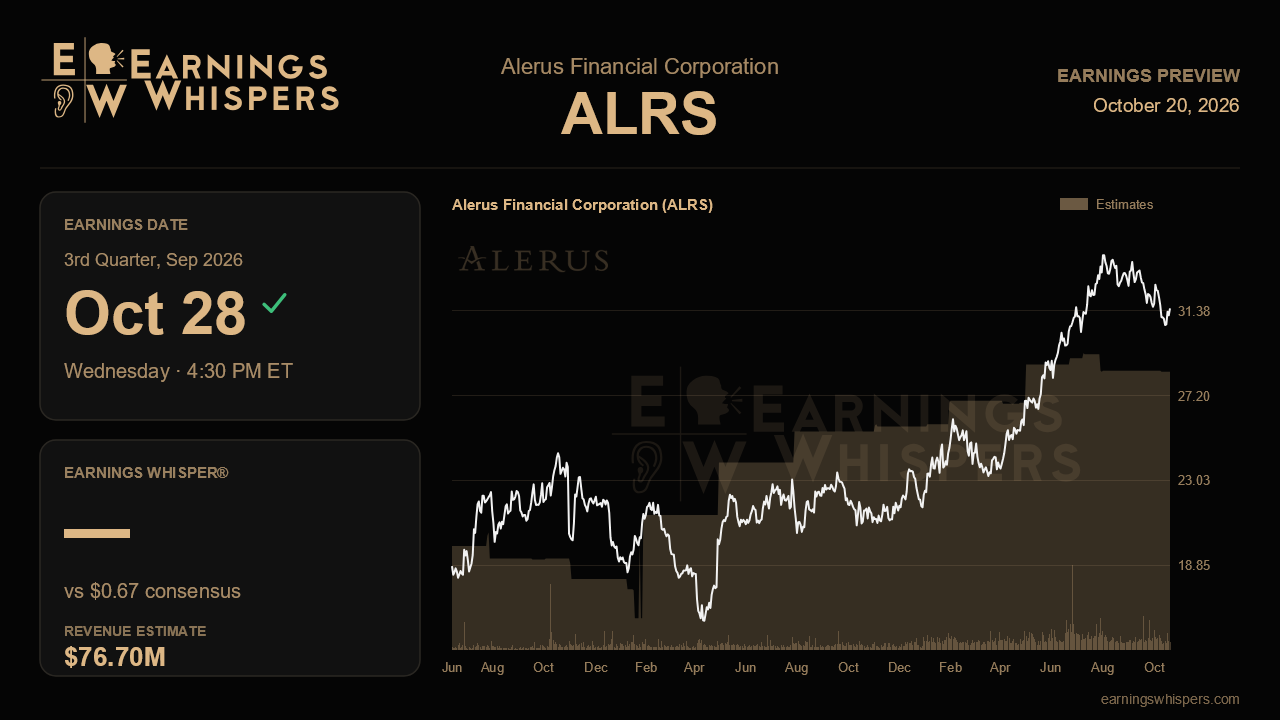
Consensus calls for earnings of $0.67 per share when Alerus reports after the close on October 28. That is essentially flat against the $0.66 earned a year ago, a gain of about 1.5%, and well below the roughly $0.80 posted last quarter. The revenue consensus of $76.7 million implies a 23% year-over-year decline. That figure is hard to square with management's decision to hold its full-year revenue outlook steady, so the per-share estimate is likely the cleaner yardstick. Either way, the Street is modeling a quarter of consolidation rather than acceleration.
The arithmetic behind that caution traces directly to the last call. Purchase-accounting accretion, which topped $3 million in the second quarter, is expected to fall to about $1.9 million. Refinanced subordinated debt adds funding cost. Mortgage banking revenue has kept sliding, and management cut its origination outlook. Most important, management reversed its macro framing. After several quarters of assuming rate cuts would help, it began planning for a meaningful chance of a September hike, which would pressure deposit costs and mortgage volumes. Against that backdrop, the full-year net interest margin guide of roughly 3.7% to 3.8% becomes the key test. Reported margin hit 3.97% last quarter. Holding near that level despite thinner accretion would suggest the core spread is genuinely improving, not just being flattered by acquisition accounting.
Loan growth is the second test, and arguably the harder one. Management's mid-single-digit full-year target requires roughly 10% annualized growth in the back half. The 30 new mid-market commercial relationships and a $28 million loan package approved just after quarter-end give that ambition some substance. Investors should want to see balances visibly moving, ideally funded by core deposits. The loan-to-deposit ratio jumped to 96.2% after seasonal public-fund outflows, and a rebound in deposits would ease worries that growth will have to be financed with pricier money. On credit, the bar is simply staying clean. Nonperforming loans below 20 basis points leave little room for surprises, though the remaining reserve on a troubled commercial credit and holding costs on two foreclosed properties bear watching. Fee income, now more than 40% of revenue, should get support from record retirement and wealth assets above $50 billion.
The market has not given Alerus much credit for its cleaner balance sheet. Shares are up just 0.4% since the last report, trailing the S&P 500 by nearly four percentage points. Sentiment has slipped from mildly bullish heading into last quarter to modestly bearish now. At $31.16, the stock sits comfortably above its 200-day moving average of $28.39 but in the middle of its post-earnings range of $28.80 to $34.40, hardly signaling conviction either way.
That muted positioning arguably lowers the bar. The central question is whether Alerus's core earnings power can absorb the loss of accretion and a less friendly rate backdrop. A margin that holds near the high end of guidance, combined with evidence that the second-half loan surge has begun, would keep the improving narrative intact. A margin that slips toward the low end while loans stall would suggest last quarter's optimism got ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-01 | |
| Sep-25 | |
| Aug-27 | |
| Jul-29 | |
| Jul-29 | |
| Jul-01 | |
| May-22 | |
| May-19 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-02 | |
| Mar-31 | |
| Feb-26 |
