TE Connectivity's Record Backlog Faces A Fiscal Year-End Test As AI Orders Set The Bar
TE Connectivity enters its fiscal fourth-quarter report with the kind of problem most industrial companies would welcome: management has raised its outlook so many times this year that merely hitting guidance may no longer feel like enough. Over three straight quarters, the full-year sales framework moved from beating a 6% to 8% through-cycle rate, to more than $2 billion of growth, to roughly 15% growth and over $2.5 billion of incremental revenue. Orders set a new record each quarter, reaching $5.7 billion last time, up 27% from a year earlier. The October 28 report, due before the open, is where that backlog has to keep turning into revenue and profit.
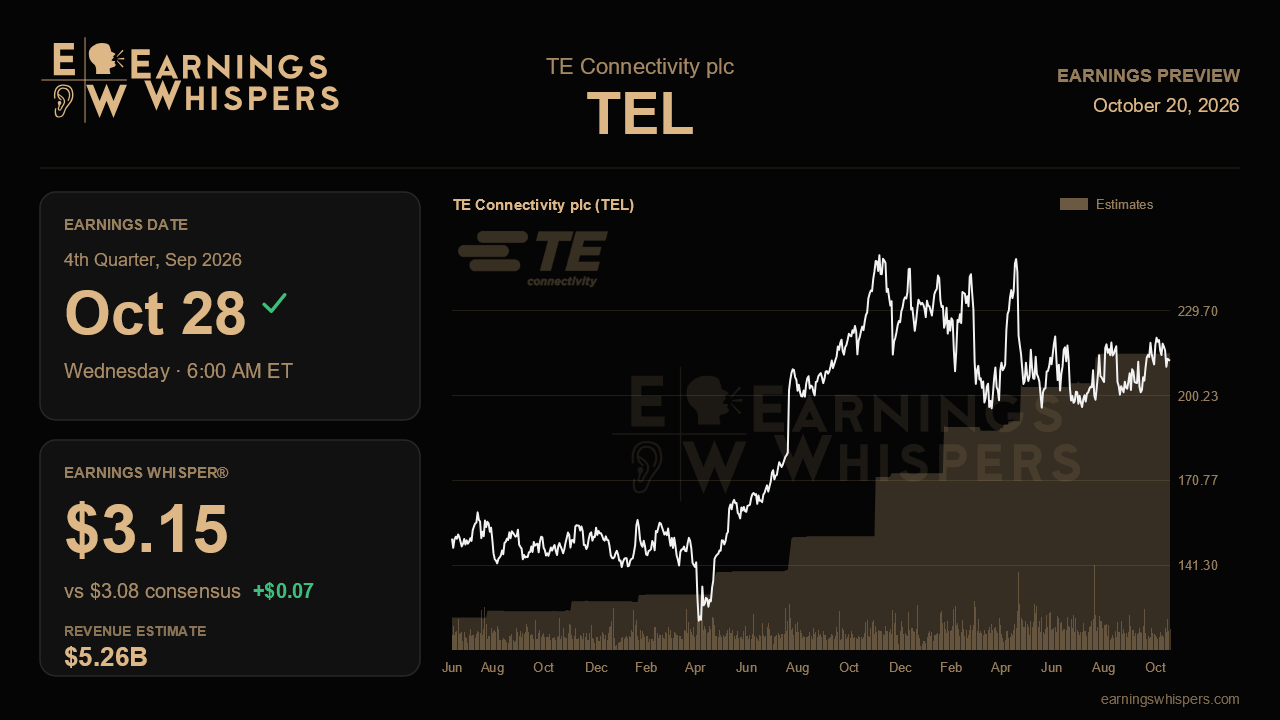
Wall Street expects earnings of $3.08 a share on revenue of about $5.26 billion. That works out to EPS growth of roughly 26% and sales growth near 11% from the year-ago $2.44 and $4.75 billion. Management guided to about $3.05 on approximately $5.25 billion, so consensus sits essentially on top of the company's outlook, with a few cents of extra optimism baked into earnings. The Earnings Whisper of $3.15 nudges the bar higher still. The gap is not dramatic, but it signals that the market expects TE to clear its own guidance by a modest margin, as it has grown used to doing. Sequentially, the forecast implies only about 2% revenue growth from last quarter's $5.16 billion, which looks undemanding given a book-to-bill that has run around 1.1 all year.
The heart of the story remains data center and AI demand. Last quarter management said its $3 billion AI target continues to shift earlier and that the business is now running above that pace, after smaller upward revisions in each of the prior two quarters. Industrial orders rose 36%, and data center orders are up roughly 70% year to date. Validation this quarter would look like continued strength in industrial segment sales, another healthy order intake that keeps book-to-bill above parity, and segment margins holding near the 23% level industrial reached last time. Energy deserves similar attention. Management recast it as a mid-teens grower after 33% organic growth last quarter, a sharp jump from the 11% to 15% range earlier in the year, and investors will want to know whether that step-up is durable or lumpy.
The risks are familiar rather than new. Global auto production is still slightly down, North American trucking remains negative, and resin, metal and freight inflation is being offset with pricing. Total adjusted operating margin of 21.9%, up 90 basis points from a year earlier, is the clearest gauge of whether pricing is keeping pace with costs. A softer margin on in-line sales would raise questions about the quality of the beat. Longer term, TE's modest presence in optical scale-out networking is the watch item, which makes any update on its fiber-attach roadmap and the 800-volt data center power opportunity worth hearing.
The stock has gained 6.5% since the last report, outpacing the S&P 500 by nearly 4 percentage points, yet at about $212 it sits just under its 200-day moving average and roughly 5% below its post-earnings high of $223.52. That range closely mirrors the prior quarter's, suggesting the shares have been consolidating rather than pricing in perfection. Sentiment is mildly bullish and a touch cooler than three months ago.
Because this report closes the fiscal year, the real verdict may rest less on the quarter itself than on what management says about the year ahead. It explicitly pointed to record backlog as support for fiscal 2027, alongside the pending Astrodyne TDI power acquisition expected to close around year-end. If orders stay at record levels and margins keep expanding, the acceleration narrative remains intact. If order growth flattens while the Street is already a few cents above guidance, the conversation shifts quickly from how much higher to how long this lasts.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-23 | |
| Sep-16 | |
| Aug-27 | |
| Aug-18 | |
| Aug-10 | |
| Aug-06 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 |
