Thermo Fisher Extends Its Beat-And-Raise Run As Organic Growth Hits 6%, But Tariff Refunds And A Flat Q4 Guide Temper The Upside
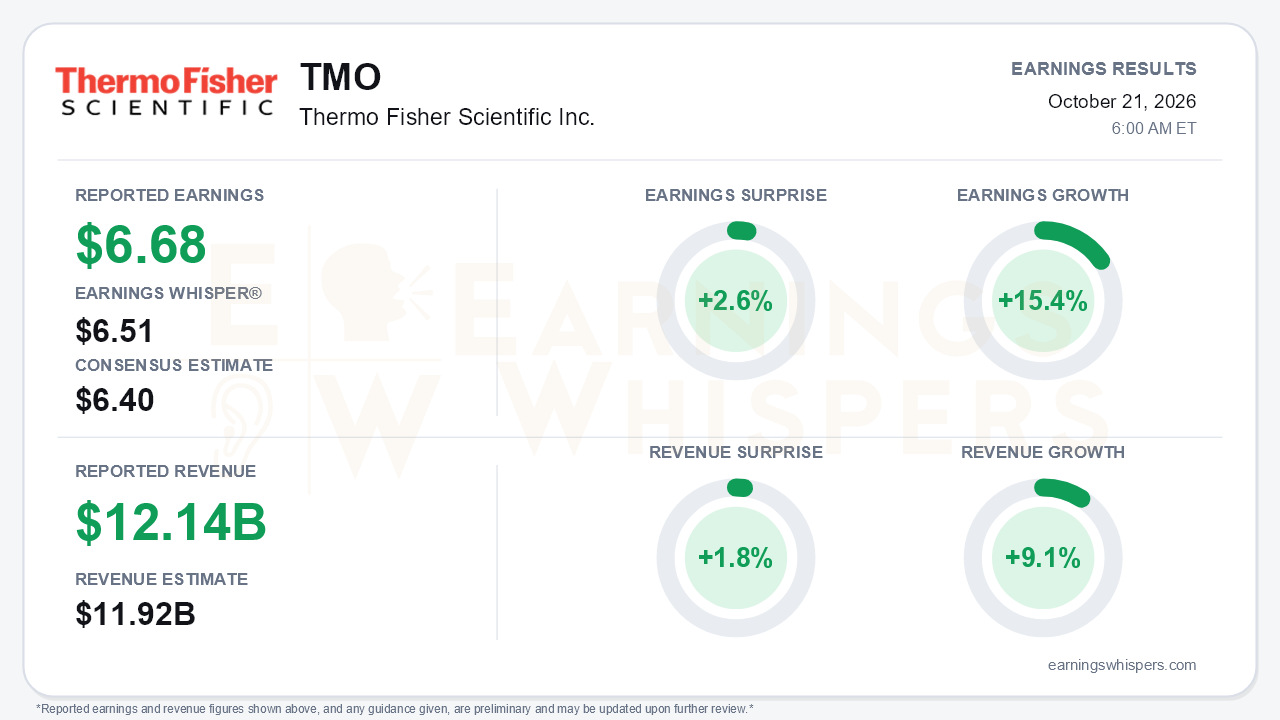
Thermo Fisher Scientific (NYSE: TMO) delivered its third straight beat-and-raise quarter, and its earnings growth is accelerating. Adjusted EPS of $6.68 topped the $6.40 consensus by 2.6% and cleared the $6.51 Earnings Whisper number. Revenue of $12.137 billion beat the $11.92 billion consensus by 1.8%. Earnings grew 15.4% year over year, up from roughly 13% in the second quarter and 6% in the first. Revenue rose 9.1%. Organic growth went from 1% in Q1 to 5% in Q2 to 6% this quarter, which is the cleanest evidence yet that the company's recovery is real. The quality of the beat deserves some scrutiny, however. The full-year outlook was raised but stayed in line with Street estimates, and management held its fourth-quarter organic outlook at 4%. That is the central tension: a strong quarter paired with a forward view that does not extrapolate it.
The composition of the upside matters. Against the company's own prior guidance, the $0.26 EPS beat broke down into $0.08 from operations, $0.03 from currency and $0.15 from one-time tariff refunds. The tariff refunds alone accounted for more than half of the beat against consensus. Even so, the operating improvement is substantive. Adjusted operating margin expanded 120 basis points to 24.5%. GAAP operating margin rose to 18.6% from 17.4%, even as amortization climbed with recent acquisitions. GAAP EPS grew a slower 9% to $4.64, held back by a $244 million held-for-sale loss, a higher tax provision and heavier interest expense. Acquisitions added about 3 points to reported growth. Free cash flow rose to $2.12 billion from $1.84 billion, and the year-to-date total of $4.62 billion is well ahead of last year's $3.32 billion.
The call showed growth that is broadening but uneven. Pharma and biotech customers accelerated to high-single-digit growth from mid-single digits in the first half. Laboratory Products and Biopharma Services posted 10% organic growth on strength in pharma services and clinical research. Analytical Instruments grew 6% organically, and its segment margin jumped 430 basis points to 26.9%. China swung from a low-single-digit decline in Q1 to low-double-digit growth. The softer spots are just as clear:
- Life Sciences Solutions grew only 1% organically, down from 3% in Q2, as research reagents for biotech customers stayed muted.
- Bioproduction growth is slowing against tough comparisons.
- Academic and government demand went flat.
- Specialty Diagnostics organic growth fell to zero from 5% in Q2.
In short, the acceleration is concentrated in pharma services and instruments, not spread evenly across the portfolio.
On guidance, the company raised full-year revenue to $47.7–$48.2 billion and adjusted EPS to $25.13–$25.43. The EPS range is now up about $1.07 from January's initial outlook. Full-year organic growth is now 4%, second-half organic growth is now 5%, and free cash flow guidance rose to $7.0–$7.5 billion. Bears have legitimate ammunition in the fourth-quarter math. Management kept Q4 organic growth at 4% despite an extra selling day, explaining that some pharma services revenue was pulled forward into Q3. The full-year margin expansion assumption also stayed at 80 basis points. Management's tone was notably more expansive. It framed AI as a demand tailwind and pointed to new initiatives as evidence: the Precure proteomics partnership with Mayo Clinic, an AI automation center in South Korea, and AI embedded in its cryo-electron microscopes. Management also outlined a path back to its 7% long-term growth framework by late 2027 or early 2028. On the balance sheet, gross leverage fell to 3.4x despite $8.9 billion in acquisitions and $4 billion in buybacks so far this year.
The market setup is more complicated than the surprise implies. TMO shares rose 19.8% from the open after the July report to $687.37. They sit about 25% above the 200-day moving average and only 2.4% below the $704 52-week high set on October 15. Investor sentiment moved from modestly negative (-0.12) to modestly positive (+0.16). That is a meaningful improvement, though not euphoria. Earnings Whispers trend signals are mostly positive, with sequential growth neutral. The stock entered the report near the top of its range, so a good deal of the acceleration story was already priced in before the numbers arrived.
The bottom line is that Thermo Fisher proved its organic recovery is gaining traction, with margins, cash flow and pharma demand all moving in the right direction. The beat, however, leaned on non-recurring tariff refunds, and the Q4 outlook implies a step back to 4% organic growth. Life-science reagents, academic customers and diagnostics remain soft. After a nearly 20% run, investors will need evidence that the 6% pace is sustainable rather than flattered by pull-forward timing.
Read our earnings preview for Thermo Fisher Scientific Inc.: https://www.earningswhispers.com/article/TMO/20435
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 56 min | |
| 59 min | |
| 1 hour | |
| 1 hour | |
| 1 hour |
Thermo Fisher Slides Despite Third-Quarter Beat - Here's What Happened
TMO
Investor's Business Daily
|
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 6 hours | |
| 7 hours | |
| Oct-15 | |
| Oct-07 | |
| Oct-05 | |
| Sep-28 | |
| Sep-25 |
