Ares Faces A Light Realizations Quarter As Investors Test Its Fee Engine And BDC Outflows
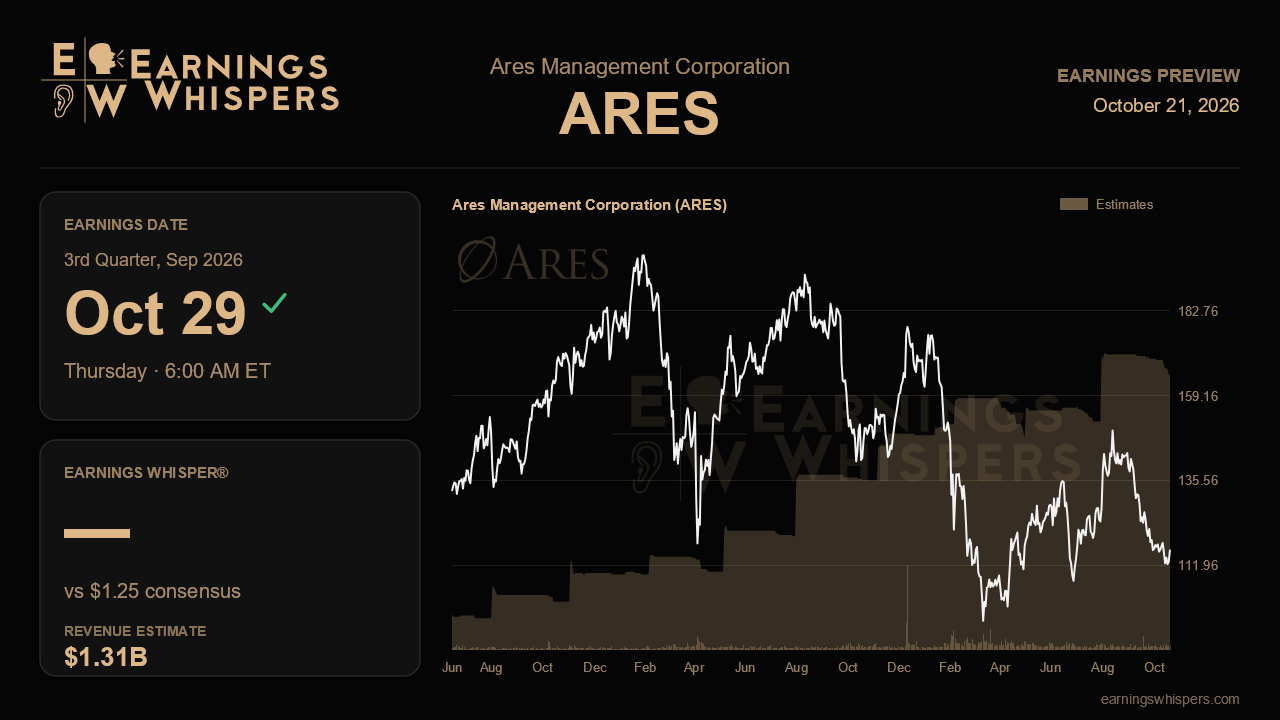
Ares Management heads into its September-quarter report with a curious disconnect. Last quarter the firm posted the biggest fundraising haul in its history, lifted fee-related earnings by 20% and talked more confidently about its franchise than at any point in the past year. Yet the stock has fallen about 9.5% since then, trailing the S&P 500 by nearly 13 percentage points. The question this report must answer is whether that selloff reflects a real crack in the story or simply anxiety about private credit and wealth-channel flows that the operating numbers do not support.
The Street is looking for earnings of $1.25 per share, up a modest 5% from a year ago and a step down from the $1.29 Ares earned last quarter. Revenue is expected at roughly $1.31 billion, a 21% year-over-year decline. That revenue drop looks alarming on its face, but for an alternative manager reported revenue swings heavily with performance income and fund-level accounting, so it says less about the health of the business than the fee line does. The softer EPS bar also lines up with management's own warning that realized net performance income would be only about $10 million this quarter, a sharp drop from the $51 million booked last quarter. In other words, a quiet carry quarter is already baked in, and a miss driven by realizations alone should not surprise anyone.
That puts the spotlight squarely on fee-related earnings, which grew to $491 million last quarter. Management said it now expects margin expansion to approach the upper end of its 0 to 150 basis point range, with year-to-date margin at 42.3%. Holding that trajectory would validate the operating leverage argument. The fuel for it is visible: a record $170 billion of dry powder and $114 billion of AUM not yet paying fees, representing roughly $828 million of potential annual management fees. Evidence that this capital is being deployed and switched on, helped by a forward pipeline management described as a record, would confirm the narrative. A stall in fee-paying AUM growth from the roughly $410 billion level would challenge it, particularly with U.S. direct lending still leaning on incumbent borrowers amid slow sponsor M&A.
Fundraising is the second test. Matching a $36 billion quarter that included an $8.5 billion hard-cap close for the Pathfinder 3 asset-based finance fund is a tall order, so a lower gross figure would not by itself be a red flag. More telling will be the newer pipes management highlighted: meaningful closings for the global digital infrastructure fund expected late in the third quarter, a first close in the fall for the new evergreen senior direct lending product, and continued inflows into the core infrastructure wealth vehicle. Wealth AUM climbed above $76 billion last quarter, and further growth there would ease concerns that management itself raised when it conceded that wealth flows may be more pro-cyclical than once assumed.
The non-traded BDC redemption queue is the swing factor most likely tied to the stock's weakness. It had already halved to about $600 million, concentrated among non-U.S. family offices and smaller institutions, and management expected stasis within two to three quarters. Further shrinkage would support that timeline; a renewed build would undercut it.
Sentiment has swung from roughly neutral before the last report to solidly bullish now, even as the stock sits near the bottom of its post-earnings range of about $110 to $150 and well below its 200-day average near $127. That mix suggests investors who are still engaged see value, while the tape remains skeptical. Ultimately, this report will be judged on whether fee earnings keep compounding near 20% with expanding margins and redemptions keep fading. If both hold, the light realization quarter becomes noise and the recent selloff looks overdone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 7 hours | |
| 14 hours | |
| Oct-19 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-04 | |
| Oct-03 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 |
