Chubb Beats Easily On Record EPS, But Premium Growth Has Nearly Stalled As Casualty Pricing Softens
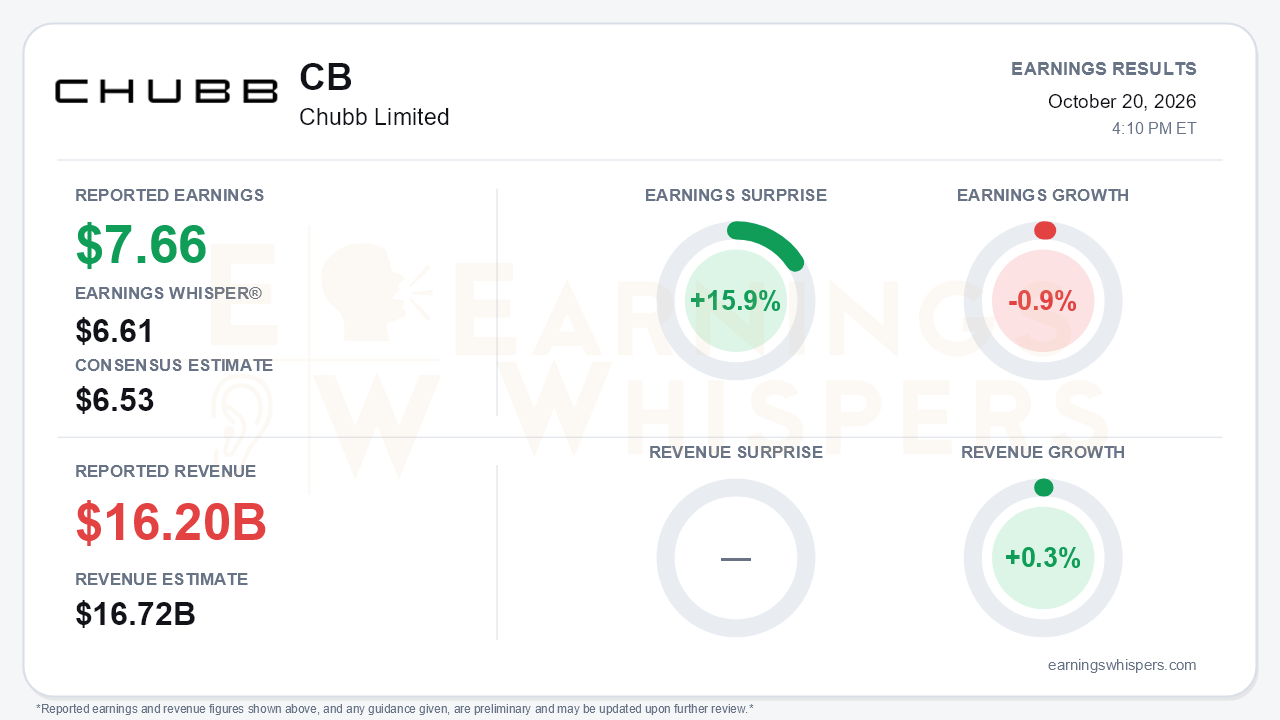
Chubb Limited delivered a clear earnings beat in the third quarter. Core operating EPS was a record $7.66, against a $6.53 consensus and a $6.61 Earnings Whisper number, a 15.9% surprise. The top line did not keep pace. Revenue of $16.195 billion missed the $16.72 billion consensus by 3.1% and grew just 0.3% year over year. On the Earnings Whispers normalized basis, earnings fell 0.9% from a year ago. Chubb's own presentation shows core EPS up 0.8%, against a restated $7.60 in the prior year. That central tension runs through the whole report: profitability, investment income and capital returns are at or near records, while the growth engine in North American commercial P&C is visibly losing momentum.
The quality of the beat deserves scrutiny on three fronts.
- **Accounting change.** Effective this quarter, Chubb redefined core operating income to exclude amortization of most purchased intangibles, which mechanically lifts the reported figure. Prior periods were recast.
- **Reserve releases.** Favorable prior-period development rose to $511 million from $361 million a year ago. That cushion helped absorb catastrophe losses of $705 million, up from an unusually light $285 million.
- **Flat underlying margins.** The reported P&C combined ratio worsened to 84.1% from 81.8%, and underwriting income fell 8.8% to $2.06 billion. The current accident-year ex-cat ratio barely moved, at 82.6% versus 82.5%.
Underwriting margins are holding, then, not improving. North America Commercial's underlying loss ratio rose a full point, which management attributes to mix as property is shed. GAAP net income rose only 1.5%, to $2.84 billion. Net realized losses of $455 million contrasted with $283 million of gains last year.
The call made the deceleration hard to ignore.
- **Total P&C growth.** Net premiums written grew 1.9%, down from 3.0% in Q2, 7.2% in Q1 and 7.7% in Q4.
- **North America Commercial.** The segment fell 2.7%, roughly 4.5 points of which came from deliberate property and financial-lines shedding and added reinsurance.
- **Middle market and small commercial.** Growth slowed to about 1% from roughly 9% in Q2.
- **Casualty pricing.** North American casualty rate increases slipped to 5.7% from 7.1%, 9.6% and 8.5% over the prior three quarters.
Evan Greenberg warned that soft conditions are spreading from property into more casualty lines, where pricing no longer keeps up with loss costs. He blamed "hungry and naive" capacity from sidecars, broker facilities and MGAs. Diversification is doing real work. Overseas General grew 6.7%, led by Latin America at 11.7%, and London wholesale jumped 13.5% on Gulf-related marine activity. Personal lines rose 5.3% with a stellar 60.3% combined ratio. Life segment income climbed 11.4% to $369 million.
The forward catalysts lean toward the balance sheet and investment portfolio rather than underwriting.
- **Investment income.** Adjusted net investment income hit a record $1.89 billion. The new money rate jumped to 6.2% from 5.5%, and duration was extended to about five years, a durable tailwind for future income.
- **USI sale.** The sale of Chubb's USI stake to Aon should produce a roughly $460 million realized gain.
- **North America Commercial outlook.** Management expects growth to improve materially as the shedding laps.
- **Data centers.** The data-center construction pipeline remains largely unbound.
Bears have legitimate ammunition, though. The medium-term outlook still uses the softer "strong growth in operating earnings and EPS" wording adopted in Q2, rather than the earlier double-digit language. Quarterly NII guidance has been discontinued. Rising rates produced $4.48 billion of after-tax portfolio marks, pulling shareholders' equity to $73.2 billion. Management also flagged emerging AI liability as an exposure not contemplated in current casualty underwriting.
Investor sentiment moved the opposite way from the headline beat. Sentiment slid from mildly positive (0.0767) to mildly negative (-0.0945), a meaningful shift for a large-cap insurer. That suggests investors were focused more on slowing premiums and softening pricing than on the EPS print. The stock has held up reasonably well. At $357.75, shares are up 3.5% from the open after the July report and sit about 7.8% above the 200-day moving average of $331.86. Price and AVWAP trend readings remain positive. Repurchases support the share count: $1.18 billion bought back at an average of $344.32, near current levels.
The bottom line is that Chubb remains a high-return franchise. Core ROTE is 21.6%, ex-AOCI tangible book value per share is up 15.4%, and investment income is rising on a structural basis. But this quarter's beat leaned on a redefined earnings measure, heavier reserve releases and investment income, not on underwriting expansion. With premium growth near 2%, casualty pricing decelerating and outlook language still softened, the next leg of the story depends on whether North American commercial growth actually rebounds as management expects.
Read our earnings preview for Chubb Limited: https://www.earningswhispers.com/article/CB/20401
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 12 hours | |
| 14 hours | |
| Oct-20 | |
| Sep-30 | |
| Sep-17 | |
| Sep-17 | |
| Sep-17 | |
| Sep-16 | |
| Sep-11 | |
| Aug-13 | |
| Aug-11 | |
| Aug-10 | |
| Aug-09 | |
| Aug-06 | |
| Aug-04 |
