Bandwidth Needs AI Voice Ramps To Back Up Its Raised Outlook As Street Hugs Guidance
Bandwidth heads into its third-quarter report with something many communications software companies would envy: a story that improved on every call for a year. Revenue growth stepped up from 12% organic in late 2025 to 20% and then 22% last quarter. Management raised full-year sales and EBITDA guidance and described AI voice as moving from pilots into paying production traffic. The question now is whether the quarter delivers evidence that the newest catalysts are converting into revenue, or whether the guided second-half slowdown in cloud communications turns out to be more than conservatism.
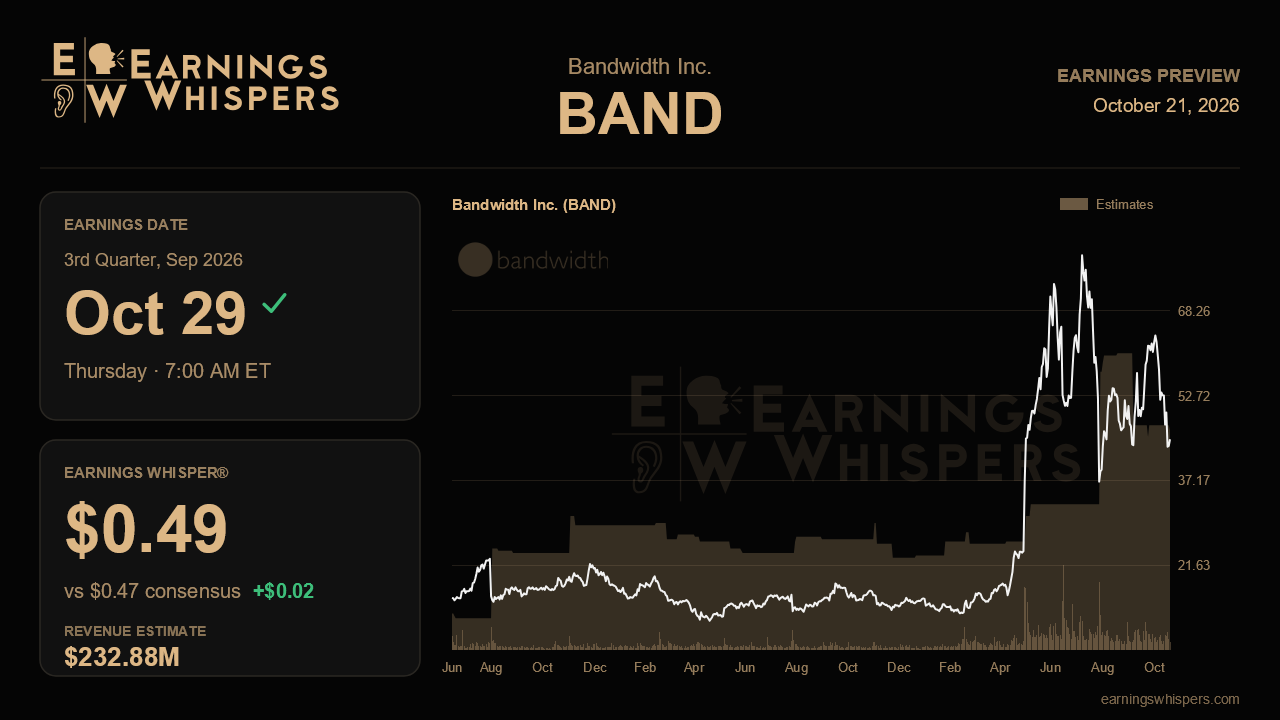
The Street is not asking for heroics. Consensus calls for non-GAAP earnings of $0.47 a share on revenue of $232.9 million, essentially the midpoint of management's guidance of $0.45 to $0.49 and $231 million to $235 million. That revenue figure implies growth of about 21.4% from a year ago, which would keep Bandwidth in the same acceleration band it reached in the first half rather than extend it. The Earnings Whisper of $0.49 sits at the top of the company's range, signaling that the more engaged crowd expects a modest beat but nothing that requires management to have badly underpromised. With EBITDA guided to $32 million to $34 million, up roughly 36%, margins carry real weight in the earnings line, and a repeat of last quarter's record 18.3% EBITDA margin would go a long way toward clearing the whisper.
The more important tests sit beneath the headline numbers. Voice growth slowed to 9% last quarter from 12%, which management blamed on the timing of large enterprise ramps rather than competitive pressure. This report should show whether that explanation holds. A rebound in voice, particularly if tied to the five $1 million-plus contracts signed in the second quarter, would validate the timing argument. Another step down would invite questions about lumpiness becoming a pattern. Salesforce's AgentForce contact center integration, which went from announcement in March to live traffic by midyear, is excluded from guidance, so any measurable contribution counts as upside. The same goes for Bandwidth Build, the June-launched tool that lets AI agents provision services, and the messaging customer that consolidated six vendors onto Bandwidth.
Retention and wallet-share metrics will help separate durable momentum from one-time wins. Average annual revenue per customer climbed to a record $256,000, and commercial net retention improved to 113% from 110%. Holding or extending those figures would support management's claim that AI is now driving nearly every customer conversation. Software services attach revenue, up 66% last quarter, is a smaller line but a key signal of whether Bandwidth can layer higher-margin software on top of its network. On the other side, political campaign revenue was trimmed to $13 million, and the share count rose to roughly 39 million after the June convertible offering, which already pressures per-share results.
The market has rewarded the narrative, though not without turbulence. Shares have gained 16.7% since the last report, outpacing the S&P 500 by nearly 13 percentage points, and sit above the 200-day moving average near $39.62. Yet at $44.71 the stock trades far below its post-earnings high of $67.14 and closer to the low end of its range, after an even wilder prior quarter that spanned roughly $31 to $79. Sentiment has cooled, slipping to mildly bullish from a firmer reading ahead of the last report, which suggests enthusiasm has been tempered by volatility rather than abandoned.
Ultimately, this quarter turns on whether Bandwidth can show that its second-half deceleration was a cushion rather than a forecast. Hitting the guidance midpoint keeps the story intact. Delivering a voice reacceleration, early Salesforce revenue and another nudge higher in full-year targets would confirm that AI demand is broadening into the core business, while a soft voice line paired with merely in-line results would leave the stock's recent gains looking ahead of the evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-12 | |
| Sep-16 | |
| Sep-15 | |
| Sep-04 | |
| Aug-20 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-01 | |
| Jun-23 | |
| Jun-16 | |
| Jun-15 | |
| Jun-09 |
