Brunswick's Raised Outlook Faces A Skeptical Market As Soft Boat Demand Tests Margin Story
Brunswick has done almost everything a cyclical manufacturer can do in a lukewarm market: four straight quarters of sales growth in every segment, three consecutive increases to its full-year earnings outlook, and margin expansion nearly across the board. The stock has gone the other way. Shares have dropped almost 20% since the last report while the S&P 500 gained about 4.5%, which makes the third-quarter release, due before the open on October 29, less about whether Brunswick can hit a number and more about whether the market believes the earnings improvement can outlast tariff refunds and a hesitant boat buyer.
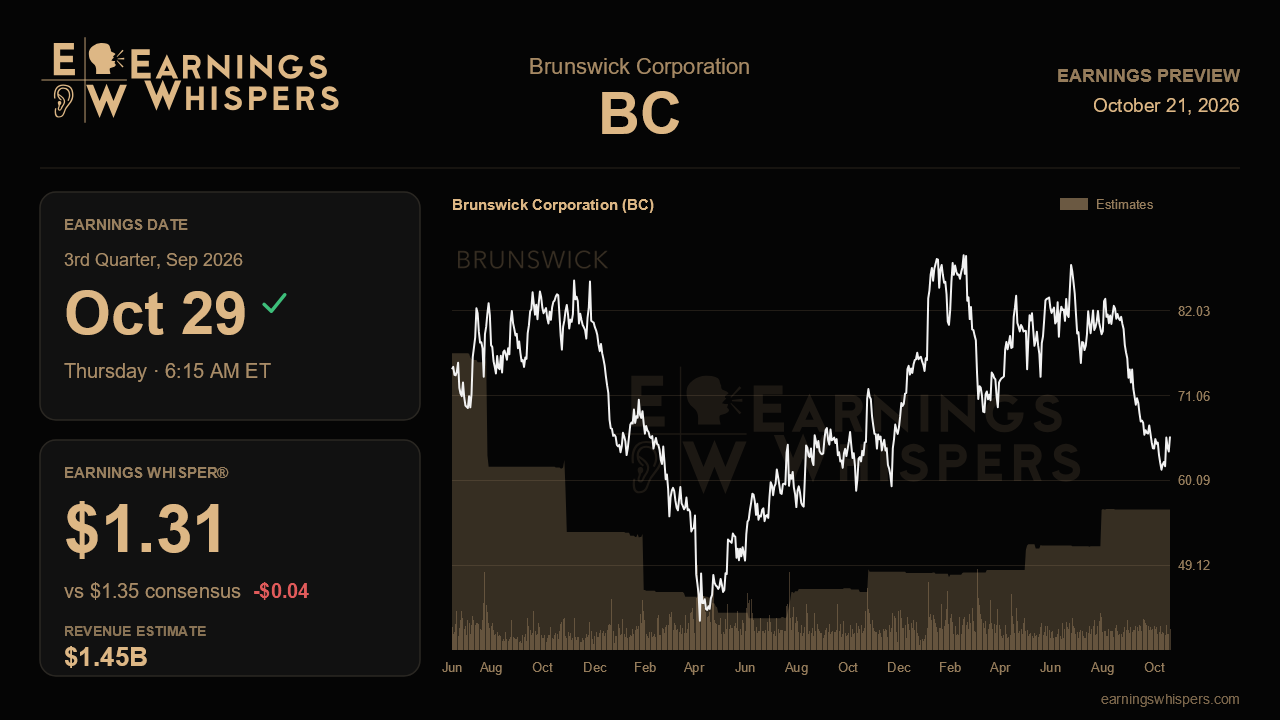
The Street expects $1.35 a share on revenue of $1.45 billion. That would be a 39% jump in earnings from last year's $0.97 on sales growth of about 6.6%, a gap that reflects how much of Brunswick's story now rests on margins rather than volume. Management guided to $1.20 to $1.40 a share and $1.40 billion to $1.50 billion in revenue, so revenue expectations sit right at the midpoint while the earnings estimate leans toward the upper half. Notably, consensus stood at $1.47 when the guidance came out, meaning analysts have already marked their models down toward the company's range. The whisper number of $1.31 sits a bit below consensus, a modest signal that the bar is being set conservatively rather than aggressively.
The full-year math deserves attention. Guidance has moved from $3.80 to $4.40 at the start of the year, to $4.00 to $4.50, and now $4.35 to $4.75. With first-half earnings of $2.26, the $4.55 midpoint implies a back half close to the first half, with the fourth quarter carrying roughly a dollar if the third lands near the middle of its range. The catch is the quality of that last raise. A large share came from timing of refunds tied to the IEPA tariff program, with the gross estimate lifted to $60 million to $70 million, partly offset by about $40 million of incremental tariff costs and roughly $0.15 of new second-half material inflation concentrated at Mercury and Navico. A clean quarter would show the operating business, not refund accounting, doing the heavy lifting. Any word on the additional Phase 4 refunds of more than $0.20 that sit outside guidance could also cushion the outlook.
Operationally, propulsion is the segment to scrutinize. It was the lone margin laggard last quarter, squeezed by tariffs and product spending, and U.S. outboard share slipped to 46% from 47%. Stabilization there, alongside continued international share gains, would validate management's confidence in Mercury's engine pipeline. Navico, where core margins widened sharply, needs to show it can absorb higher memory and component costs while building on its first Simrad AutoCaptain OEM agreement. In parts and accessories, the drag from West Marine store closures is a known headwind, so the question is whether the 200 basis points of margin gains hold. On the boat side, retail was down about 4% through June, with premium buyers steady and value buyers struggling. Evidence that dealer inventories remain lean and that the value-model pruning is not deepening would support the view that demand is stabilizing rather than rolling over.
Sentiment has soured markedly, with bearish readings far heavier than the mild caution ahead of last quarter. The chart reflects it: the stock trades near $66, well below its 200-day average near $78 and only about 7% above its post-report low of $61.20, a range sitting entirely beneath the prior quarter's. That pessimism lowers the hurdle somewhat, though it also signals little patience for a stumble.
The central issue is whether Brunswick can hold its full-year range without leaning harder on refunds. Reaffirming $4.35 to $4.75 with propulsion margins stabilizing and inflation absorbed would keep the improving narrative intact. Trimming toward the low end, or needing refunds to offset weaker operations, would confirm what the market already seems to fear.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-08 | |
| Oct-05 | |
| Sep-29 | |
| Sep-21 | |
| Sep-15 | |
| Aug-24 | |
| Aug-21 | |
| Aug-18 | |
| Aug-18 | |
| Aug-14 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
