Bank OZK Beats On EPS, But The Real Story Is Bolder 2027 Loan-Growth Guidance As 2026 Growth Is Trimmed
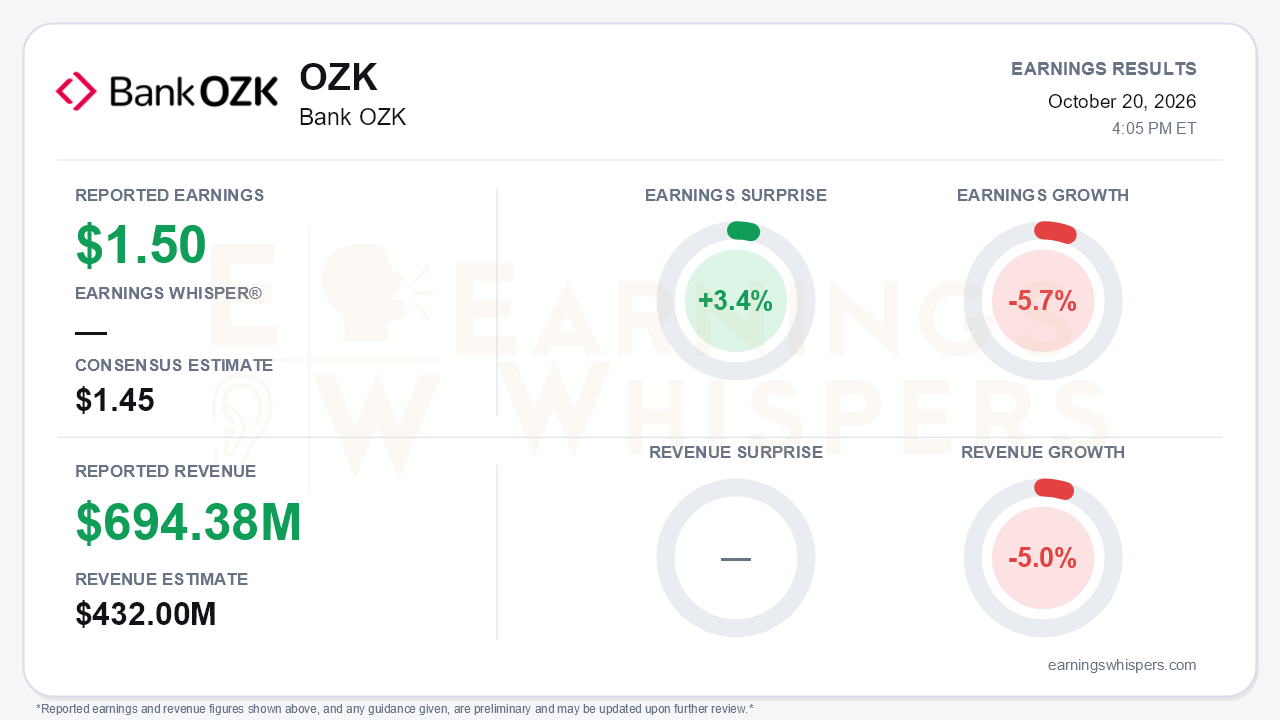
Bank OZK (NASDAQ: OZK) delivered a modest beat in the third quarter. Diluted EPS of $1.50 topped the $1.45 consensus by 3.4%, and revenue of $694.38 million came in 60.7% above the $432.0 million consensus. The headline beat is not the most important development, though. Earnings still fell 5.7% year over year and revenue declined 5.0%, which extends a year of shrinking profits. What changed is the outlook. Management trimmed 2026 loan growth to 3-5% while introducing a notably stronger 2027 framework of 10-12% loan growth and high-single-digit fee growth. That is the central tension. Near-term balances are about to shrink, while the medium-term growth story just got more ambitious.
The quality of the quarter looks better on a sequential basis than a year-over-year one. Net income available to common stockholders was $164.3 million, down 9.0% from a year ago but up 0.6% from the second quarter. EPS edged up from $1.49 to $1.50. Through nine months, EPS of $4.43 is down 4.5%, so the third-quarter decline was slightly steeper than the year-to-date pace. Earnings have stabilized rather than re-accelerated. Profitability remains enviable for a regional bank:
- a 1.55% annualized return on average assets;
- a 4.24% net interest margin;
- a 39.9% efficiency ratio;
- record total assets of $43.2 billion, along with record loans and deposits.
The call explained why management is leaning into 2027. The Corporate and Institutional Banking (CIB) unit is becoming the growth engine. It expanded from seven-plus business lines and 42 industry codes last quarter to nine lines and 44 codes. CIB added 65-plus new relationships with zero past dues and zero net charge-offs, and its deposits rose more than 20% sequentially. Management expects CIB balances to surpass the legacy Real Estate Specialties Group (RESG) book in 2027. Diversification is also showing up elsewhere:
- Power sports indirect lending launched October 1.
- The bank is now below the 300% commercial real estate concentration guideline.
- Construction and development exposure is expected to fall under the 100% guideline within one to three quarters. Management tied that milestone directly to capital efficiency, ROE and buybacks.
Net headcount is down roughly 94 over two quarters even as CIB hiring continues. Securities rolling off at about 3.5% are being reinvested at higher yields.
Credit signals improved at the margin. Special mention loans declined materially, reversing their second-quarter increase, and the net charge-off ratio was the lowest of 2026. The IQHQ San Diego loan, flagged earlier as an August maturity risk, was extended three years with a $121 million paydown and $100 million of new sponsor capital, and it remains pass-rated. Management now describes the CRE cycle as largely behind the bank by year-end 2027, a shift from its earlier 'late stages' framing. Bears still have legitimate ammunition:
- Foreclosed assets have climbed to about $420 million across seven properties, from roughly $150 million in the first quarter, and management signaled no urgency to liquidate them.
- Net charge-offs remain elevated for 2026.
- RESG payoffs ran $690 million in just the first 19 days of October, pointing to near-record or record payoffs and a fourth-quarter loan decline.
- 2027 net interest income is guided only to low-single-digit growth, assuming no further Fed hikes. When an analyst suggested 2027 pre-provision net revenue could be flat to down, management said only that it hopes to beat that estimate.
- An 82-basis-point jump in the 10-year yield produced a sizable securities mark.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated meaningfully, sliding from roughly neutral at -0.03 ahead of the prior report to -0.35 now. Shares have fallen 9.7% since opening at $51.14 after the July report, to $46.16. That leaves the stock about 4.6% below its 200-day moving average of $48.37. Earnings Whispers price and AVWAP trend readings are both negative, consistent with a market that has steadily marked the stock down despite still-strong returns. Investors appear focused on falling earnings, rising foreclosed assets and a 2026 guidance cut rather than on the multi-year diversification narrative.
The bottom line is that Bank OZK delivered a small beat and stabilizing sequential earnings, but the quarter's significance lies in guidance. A trimmed 2026 outlook and a looming fourth-quarter balance decline sit against a credible and more aggressive 2027 growth plan led by CIB, fee income and easing concentration constraints. Credit is improving in some measures but not all, and modest net interest income guidance means loan growth may not quickly translate into earnings growth. With sentiment sharply weaker and shares below their long-term average, the burden is on management to show that the 2027 inflection is real.
Read our earnings preview for Bank OZK: https://www.earningswhispers.com/article/OZK/20412
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-30 | |
| Jul-24 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 |
