BankUnited Misses A Rising Whisper As Margin Gains Outrun Soft Loans, Fees And Rate-Pressured Deposits
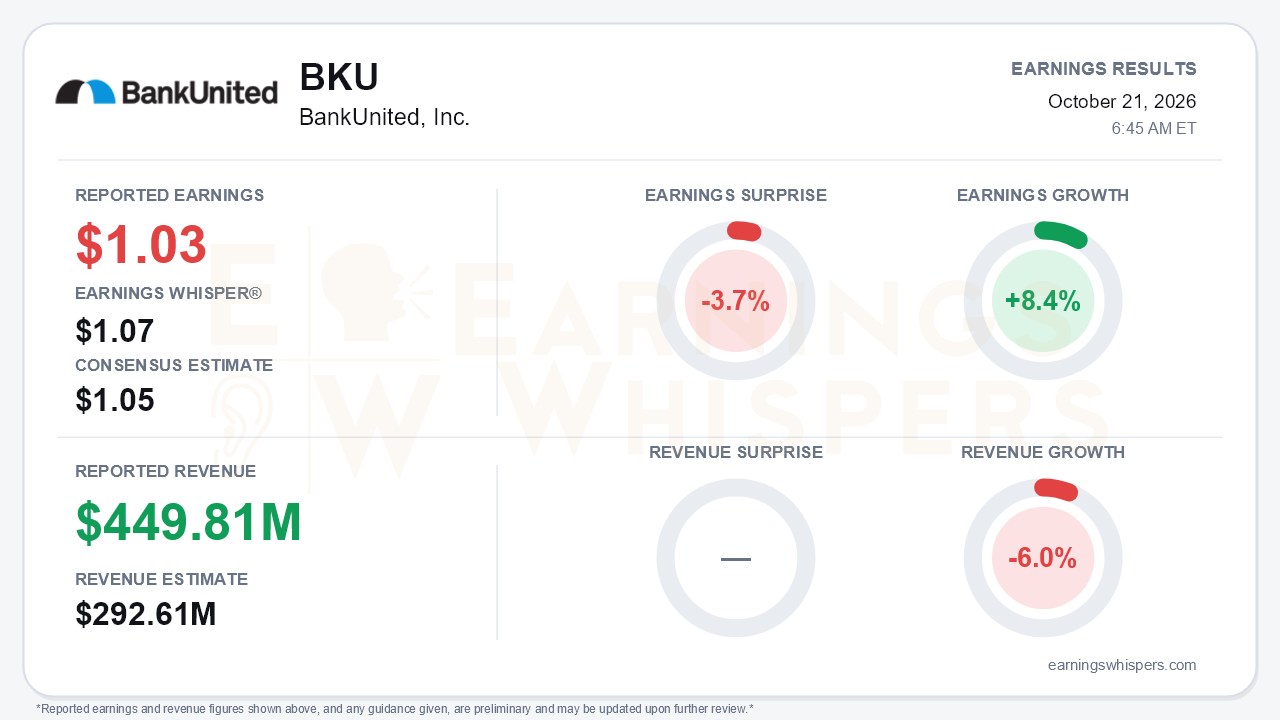
BankUnited reported adjusted earnings of $1.03 per share for the September quarter. That fell short of the $1.05 consensus estimate and the $1.07 Earnings Whisper number, a 3.7% miss. Earnings still grew 8.4% year over year, and the quarter marked a third straight sequential step up in adjusted EPS, from $0.83 in the first quarter to $0.96 in the second and $1.03 now. That is the central tension. The margin engine is running ahead of plan, but investors had priced in more. Much of the improvement came from below the revenue line rather than from a broadening of the franchise.
The headline revenue figures need context. Revenue of $449.81 million beat the $292.61 million consensus by 53.7% yet fell 6.0% year over year. Revenue that far above consensus points to a different reporting basis rather than a blowout. The figure appears to capture gross interest income plus fees. Gross interest income is shrinking as variable-rate loans and securities reprice lower. Net interest income, the more relevant measure, rose 2% sequentially and 4% from a year ago to $260.7 million.
The quality of the beat over last year deserves scrutiny:
- **GAAP versus adjusted EPS:** GAAP diluted EPS was $1.01. The adjusted figure excludes a $2.3 million loss from selling roughly $1.0 billion of lower-yielding securities.
- **Pre-provision earnings:** Pre-provision net revenue actually fell to $105.9 million from $109.9 million. On an adjusted basis it was essentially flat at $108.2 million.
- **Provision and buybacks:** Earnings improvement leaned on a provision that dropped to $9.0 million from $15.6 million. It also leaned on a buyback that cut diluted share count to 70.5 million from 71.8 million.
- **Fee income:** Non-interest income fell to $19.8 million from $29.2 million. Drivers were the securities loss, a $1.1 million equipment-disposition loss in leasing, a $1.9 million BOLI decline and a $1.8 million dip in capital markets.
The call nonetheless preserved a credible margin story. Net interest margin climbed to 3.16%, up 10 basis points sequentially and 16 from a year ago. That hit management's 3.15% exit target a quarter early. Deposit costs fell 6 basis points to 1.99% even as the Fed began hiking in September. Management raised its fourth-quarter margin outlook to roughly 3.20%, restoring the original target that had been trimmed last quarter. It also guided to about $265 million in net interest income and $115 million in PPNR. The securities repositioning, which moved sub-one-year duration into three-to-five-year paper, lifted the portfolio yield to 4.76% from 4.64%. The slightly asset-sensitive balance sheet should benefit if the assumed December hike materializes. Tone was notably confident, with management drawing a "deja vu" comparison to beating its 2025 target early.
Bears have legitimate ammunition beneath that margin progress:
- **Loan growth:** Core loan growth is running about 4% year over year, versus the 6% originally guided. Average C&I balances fell roughly $300 million sequentially on payoffs and slipped closings. Residential runoff continues, though management may address flattening or regrowth in January.
- **Deposits:** Average non-interest-bearing deposits were flat sequentially. Period-end balances fell $821 million as title-related deposits dropped in September on a mortgage-market slowdown. Management also flagged intensifying pricing competition for title, HOA and promotional money-market and CD deposits.
- **Higher-rate side effects:** Management warned of CRE deal retrading that should slow CRE growth in 2027.
- **Credit:** Non-performing loans rose 18% sequentially, including one weather-disaster-recovery credit. Reserve coverage of NPLs slipped to 84% from 97%, though NPLs remain 30% below a year ago and charge-offs held at 0.11%.
- **Capital and book value:** Tangible book value per share fell to $39.10 from $40.48 as AOCI losses widened by $138 million and buybacks accelerated to $97 million. The tangible common equity ratio slipped to 8.0%, and CET1 eased to 12.1%.
Investor expectations had already cooled. Earnings Whispers sentiment remained positive but weakened meaningfully, falling to 0.25 from 0.49 ahead of the report. The stock entered earnings at $42.32, down 8.0% since the open after the July report. It sat 8.8% below its 200-day moving average and 12.6% below its mid-August inter-earnings high of $48.40. It was just 3.6% above the October 14 low of $40.83. Trend readings on price, sequential growth and AVWAP remain negative. The market has clearly been discounting the rate-driven risks to deposits and loan growth rather than rewarding the margin trajectory. A whisper-level miss gives skeptics little reason to change that stance immediately.
The bottom line is that BankUnited delivered a better margin quarter than it promised, and its fourth-quarter guidance points to further improvement. Still, the EPS miss against a rising whisper exposes how narrow the drivers are. Flat pre-provision earnings, lower provisions and buybacks did much of the work. Loan growth, fee income and core deposit momentum all softened just as higher long rates began biting. Until the balance sheet shows it can grow alongside the margin, the stock's discount to its trend levels looks more like caution than oversight.
Read our earnings preview for BankUnited, Inc.: https://www.earningswhispers.com/article/BKU/20418
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-18 | |
| Oct-05 | |
| Sep-24 | |
| Sep-22 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-13 | |
| Jul-07 | |
| Jun-24 |
