Weatherford's 37% EPS Beat Leans On A Tax Benefit, While Margins And Cash Flow Carry The Quarter And Middle East Weakness Trims The EBITDA Outlook
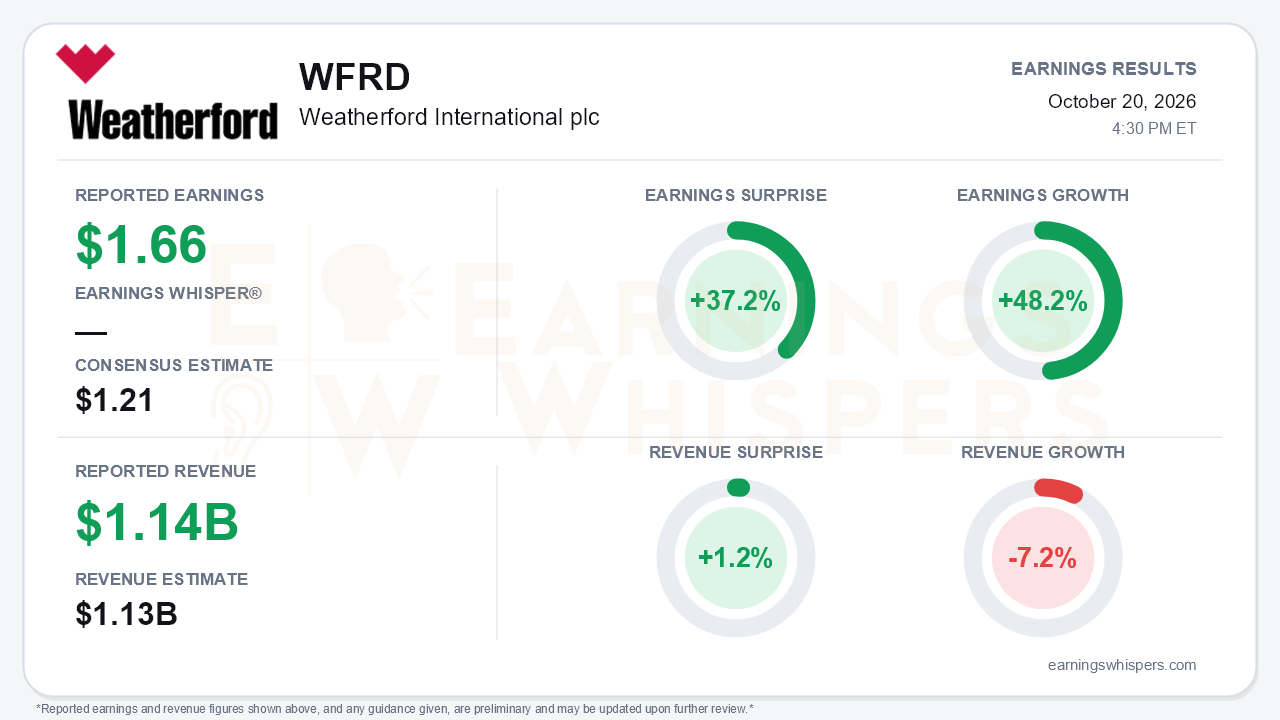
Weatherford International (NASDAQ: WFRD) reported third-quarter earnings of $1.66 per share, beating the $1.21 consensus by 37.2%. Earnings grew 48.2% year over year. Revenue of $1.143 billion topped the $1.13 billion consensus by 1.2% but fell 7.2% from a year ago. The headline looks like a blowout. The quality of the beat deserves scrutiny, however, because much of the per-share upside came from below the operating line. The tax provision dropped to just $4 million, compared with $52 million a year earlier and $33 million in the second quarter, helped by a $44 million deferred tax benefit. Pre-tax income actually slipped to $129 million from $139 million a year ago. GAAP operating income fell 14% year over year to $153 million. The EPS surprise reflects a favorable tax quarter far more than a sudden step-change in earnings power.
That does not make the quarter weak. It means the real story is margins and cash, not EPS. Adjusted EBITDA of $254 million rose 14% sequentially and landed near the top of management's $235–265 million guide. Adjusted EBITDA margin expanded 204 basis points sequentially to 22.2%, and it was up 39 basis points year over year even as revenue shrank. Adjusted free cash flow of $155 million rose 57% from a year ago, the second straight quarter above 60% conversion. Net leverage fell to 0.28x. The segment mix was uneven, though:
- **Drilling & Evaluation:** margin jumped 726 basis points sequentially to 27.2%, but the call acknowledged that lumpy MPD capital sales flattered the result.
- **Well Construction & Completions:** the largest segment saw margin fall 449 basis points year over year to 22.2% on weaker North American fall-through.
- **Production & Intervention:** a steadier contributor, with margin up 515 basis points year over year to 23.2%.
The central tension is that execution keeps improving while the top-line environment keeps eroding. Middle East/North Africa/Asia revenue fell 16% year over year on geopolitical disruption. On the call, management said the region had weakened relative to July expectations, with rig counts trending lower, tender cycles slipping and a recent escalation. It now assumes no recovery. Saudi Arabia has shrunk to roughly 20% of the region after a contract ended, and Iraq is substantially down. That is why the full-year adjusted EBITDA range was narrowed around a midpoint implied near $990 million. The midpoint has now been trimmed at every call this year, from $1.05 billion in February. Against that, free cash flow conversion guidance was raised for the third time, to the high-40% range.
The forward catalyst list grew meaningfully. Management guided fourth-quarter revenue to $1.28–1.33 billion and EBITDA to $270–290 million, citing four drivers:
- a full quarter of the newly closed NCS Multistage acquisition, which is targeting at least $15 million in cost synergies;
- Brazil deepwater MPD deliveries;
- seasonal North American strength;
- a Venezuela startup, which produced first revenue in the third quarter and could reach triple-digit millions in 2027.
The redemption of $236 million of 8.625% notes saves roughly $20 million in annual interest. The Delaware redomestication, still subject to court approval, should add $20–30 million in annual cash savings from 2027. Management's preliminary 2027 framework calls for mid-single-digit global activity growth, outperformance by Weatherford, year-over-year margin expansion and 50% free cash flow conversion. Bears have legitimate ammunition, too:
- fourth-quarter margin is guided modestly below 22.2% on mix and Venezuela startup costs;
- fourth-quarter free cash flow is guided only above $100 million;
- capex steps up to $70–80 million;
- working capital rose to 29.2% of revenue;
- planned divestitures will distort reported revenue for a couple of quarters;
- Pemex collections remain the largest swing factor for cash flow.
Investor sentiment shifted sharply heading into the report. It improved from -0.50 after the July release to roughly -0.04, moving from clearly negative to essentially neutral. The stock has not followed. Shares at $79.34 are down 9.5% from the opening price after the prior report and sit 14.7% below the 200-day moving average of $93.02. The Earnings Whispers price and AVWAP trend readings remain negative. Expectations have thawed, but the market has been pricing in the Middle East drag and the shrinking EBITDA outlook rather than the margin and cash flow progress.
The bottom line is that Weatherford delivered a genuinely strong operational quarter, with better margins, better cash conversion and a cleaner balance sheet, wrapped in an EPS beat that overstates the earnings improvement because of an unusually low tax charge. The call preserved a credible 2027 growth narrative built on NCS, Venezuela, MPD and cost savings. But the full-year EBITDA midpoint keeps drifting lower, and the Middle East has no recovery assumed. Until fourth-quarter guidance converts and international activity stabilizes, the gap between improving execution and a still-weak share price is likely to remain the defining feature of the setup.
Read our earnings preview for Weatherford International plc: https://www.earningswhispers.com/article/WFRD/20438
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 9 hours | |
| 12 hours | |
| Oct-20 | |
| Oct-08 | |
| Sep-25 | |
| Sep-03 | |
| Sep-01 | |
| Aug-24 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-20 | |
| Jul-14 | |
| Jul-13 |
