Metropolitan Bank's Earnings Surge On Margin Expansion And Lower Provisions, But Rate Hikes Cap The NIM Outlook
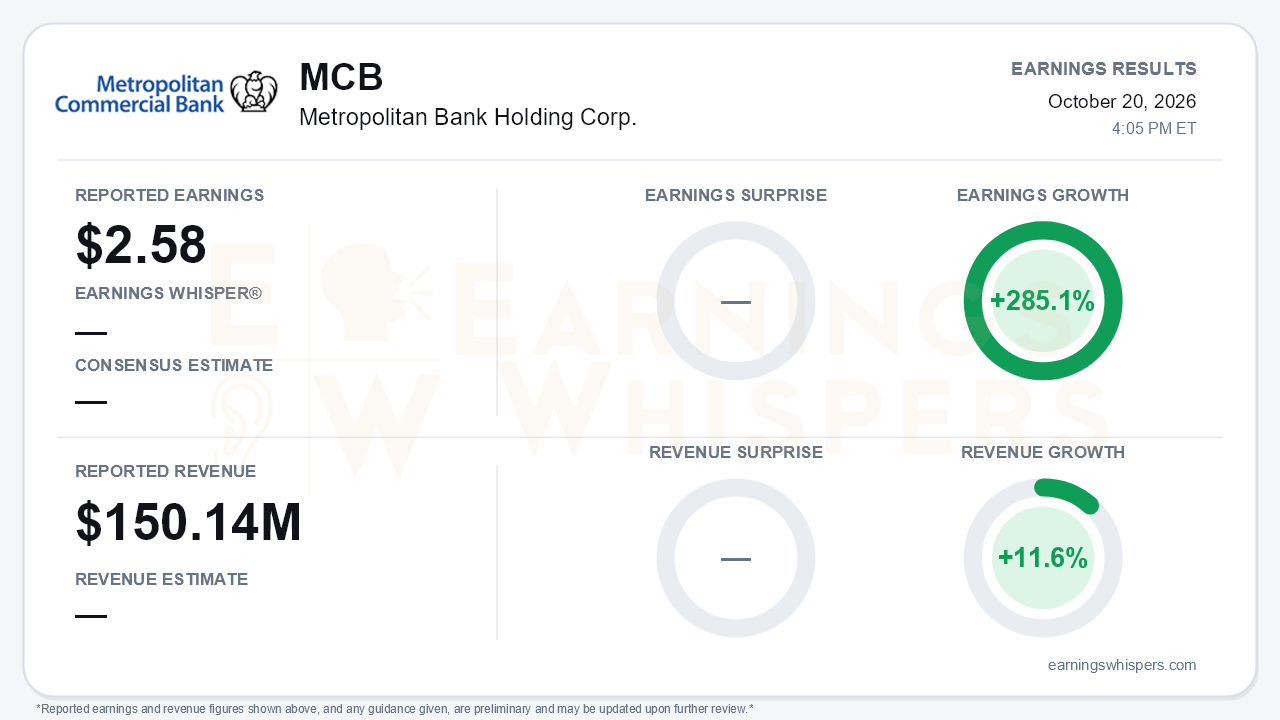
Metropolitan Bank Holding Corp. (NYSE: MCB) delivered its strongest quarter of the year. Diluted EPS was $2.58, up from $1.54 in the second quarter and $0.67 a year earlier, with earnings growing 285.1% year over year. Earnings Whispers revenue of $150.14 million rose 11.6%. The company's own definition of total revenue, net interest income plus non-interest income, was $100.6 million, up from $79.8 million a year ago. No consensus figures were available, so this quarter has to be judged on its trajectory rather than a beat or miss. That trajectory was impressive. The net interest margin expanded 28 basis points to 4.36%, return on average equity rose to 13.1% from 8.0%, and the efficiency ratio fell to 49.2%. The central tension is that the rate backdrop has turned against a liability-sensitive balance sheet just as the margin peaked, so the outlook management offered was more defensive than the print.
The quality of the beat deserves scrutiny. Pre-tax income rose about $18 million sequentially. Roughly $8 million of that came from a lower provision for credit losses, which fell to $5.1 million from $13.3 million in the second quarter and $23.9 million a year ago. Part of the margin gain was also non-recurring. The company attributed some of the expansion to elevated prepayment penalties and deferred fee recognition from loan payoffs, and management put the normalized NIM at 4.20%-4.25%. Two other items helped:
- **Tax rate:** a new tax-credit investment program lowered the effective rate to 29.5% from 31.1%.
- **Expenses:** operating expenses fell to $49.5 million from $51.8 million, though that was still above the roughly $48.5 million run rate management had guided on the second-quarter call.
Investors should also note that the allowance-to-loans ratio sits at 0.85%, versus 1.39% a year ago. That decline largely reflects a methodology change made in the first quarter, along with charge-offs of previously reserved loans.
The underlying franchise trends were genuinely better. Net interest income grew 7.9% sequentially, accelerating from 5.3% in the second quarter, and management nudged its full-year growth guide to "more than 20%." Loan production reached $918 million, up from $719 million, and loans are up $724 million year to date. That keeps the $1 billion full-year target intact, with roughly $700 million of signed term sheets at around 7% coupons. Deposits rebounded by $589 million after a flat second quarter. Non-interest-bearing balances rose about 12%, and the cost of deposits fell 8 basis points to 2.49%. Credit also normalized. Net charge-offs fell to 18 basis points after heavy cleanups in the first half, and management expects recoveries in the fourth quarter. The one blemish was a single CRE loan moving to non-accrual, which nudged non-performing loans up to 0.95% of total loans.
The forward picture is where bears have legitimate ammunition. Management said:
- **Rates:** the Fed hiked on September 16, and MCB models further hikes in December and March. It estimates roughly 5 basis points of NIM compression per 25-basis-point hike.
- **Margin guidance:** the fourth-quarter NIM guide is 4.15%-4.20%, and the CFO described holding that level as the best case for 2027.
- **Hedges:** $1 billion of swaps roll off in April and August 2027, pushing the deposit beta toward 65%-75%.
- **Deposit growth:** about three-quarters of the third-quarter deposit inflow came from EB-5 money tied partly to an application cutoff, so management expects that growth to decelerate.
- **Funding costs:** deposit-program fees are projected to rise about 25% in the fourth quarter.
The payments initiative slipped again. Gaming go-live moved from the fourth quarter to the first quarter of 2027, and the fee-income uplift is now expected in the back half of 2027. Returns are tracking in the low teens, below the original 16% exit target.
Management still struck a confident tone. It raised the quarterly dividend 14% to $0.40 and executed its first buyback above book value, about $10 million at roughly 109% of estimated year-end book. Management called the shares "on sale," has $40 million of authorization remaining and said it is committed to further purchases. It also described 2027 as potentially "transformative" on AI and payments. Tangible book value rose to $78.54 per share. However, accumulated other comprehensive loss widened by about $15.6 million as rates rose. Investor sentiment and current price data were not available. The stock opened at $87.30 after the July report, a level below the current 200-day moving average of $89.68, which suggests the market had not been paying up ahead of this quarter's improvement.
The bottom line is that MCB proved its core earnings power this quarter, with accelerating net interest income, cleaner credit, stronger deposits and better efficiency. But the headline EPS was flattered by lower provisions, prepayment fees and a lower tax rate. Rate hikes, swap roll-offs and slowing EB-5 inflows point to a flat-to-lower margin from here, and the payments catalyst keeps sliding. Capital returns and buybacks give the story support, but the next leg of earnings growth depends on loan volume and fee initiatives that have yet to show up.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-01 | |
| Sep-23 | |
| Aug-20 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-20 | |
| Jul-20 | |
| Jul-15 | |
| Jul-09 |
