Bankwell's Margin Breakout Faces A Durability Test As Street Models A Sequential Earnings Dip
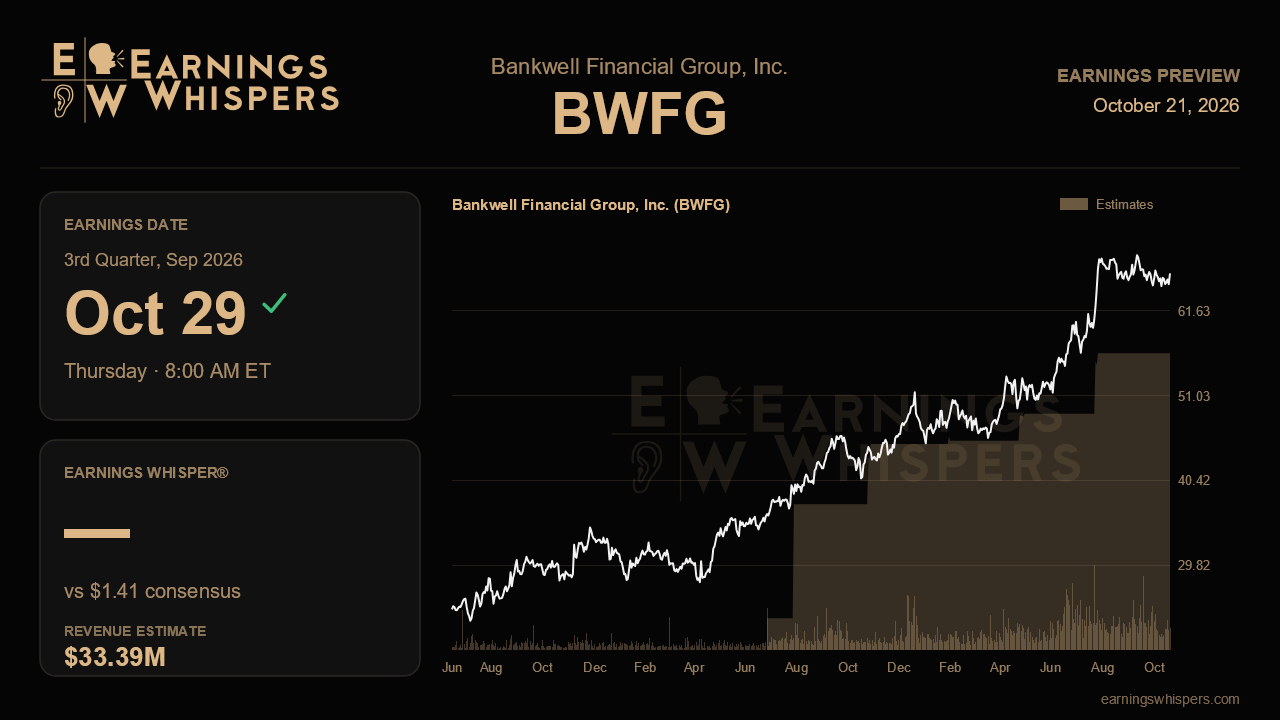
Bankwell Financial Group delivered the kind of quarter last time that changes how a small bank is valued: a 30-basis-point jump in net interest margin to 3.58%, re-accelerating loan growth and the first raise to full-year net interest income guidance in this stretch. The awkward part of the setup heading into the October 29 report is that Wall Street does not seem to fully believe it will repeat. Consensus calls for earnings of $1.41 a share, below the $1.52 posted last quarter. That would still be about 11% better than a year ago, but it implies analysts see some of the second quarter's strength as a high-water mark rather than a new floor.
The revenue consensus of $33.4 million, which screens as a 37% year-over-year decline, needs context. It appears to reflect a net revenue measure rather than the gross figures in the prior-period comparisons. Management's raised guidance of $115 million to $117 million in net interest income plus $12 million to $13 million in fee income works out to roughly $32 million to $33 million a quarter, so the Street is sitting near the upper end of what the full-year outlook implies. In other words, the bar on the top line is not low.
The most important question is whether the margin holds near 3.58%. Last quarter's expansion came from deposit costs falling 16 basis points to 2.94% while asset yields rose, and management flagged that the time-deposit repricing tailwind will fade starting in the fourth quarter as remaining maturities near market rates. That makes this report the last clean read before the book becomes more rate-neutral. A stable or modestly higher margin would validate the raised guidance; a give-back toward the 3.30s would suggest the second quarter benefited from timing that will not recur.
Loan growth is the second test. Management lifted its full-year target to 5% to 7% after a soft first quarter, saying it had primed the pump. Hitting that range likely requires another solid quarter of net growth, ideally closer to the $93 million posted last quarter than the $27 million before it. Competition is creeping back into healthcare and senior-housing lending, a niche that has been important to Bankwell, so pricing on new loans matters as much as volume. On funding, continued growth in core checking, aided by the new Bay Ridge branch in Brooklyn, and further cuts to brokered deposits would show the deposit-cost improvement is structural.
Expenses and fees round out the picture. Non-interest expense guidance rose to $65 million to $67 million on incentive pay and technology investment, and the 47.5% efficiency ratio last quarter will be hard to match if SBA gains, which management is deliberately capping for risk reasons, cool from the $2.4 million pace. That, along with a possible normalization in provisioning after credit improved to nonperforming assets of 46 basis points, may explain the softer EPS estimate.
The market has rewarded the story so far, with shares up nearly 10% since the last report against a 4% gain for the S&P 500. At $66.31, the stock sits well above its 200-day average of $56.01 and in the upper part of its post-earnings range, though still about 5% below the $69.59 high. Sentiment has turned more bearish, at -0.31 versus -0.20 a quarter ago, an interesting divergence from the price action. Ultimately, the report hinges on whether Bankwell can show its margin and loan growth are durable enough to support the raised outlook as the deposit-repricing tailwind begins to fade. Reaffirming or nudging up the NII guide would keep the inflection narrative intact; trimming it would suggest the second quarter was the peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-20 | |
| Oct-15 | |
| Aug-10 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-09 | |
| Apr-24 | |
| Apr-23 | |
| Apr-22 | |
| Apr-08 | |
| Feb-23 | |
| Jan-30 | |
| Jan-29 |
