Federal Signal Faces Backlog And SSG Order Test After Two Straight Guidance Raises
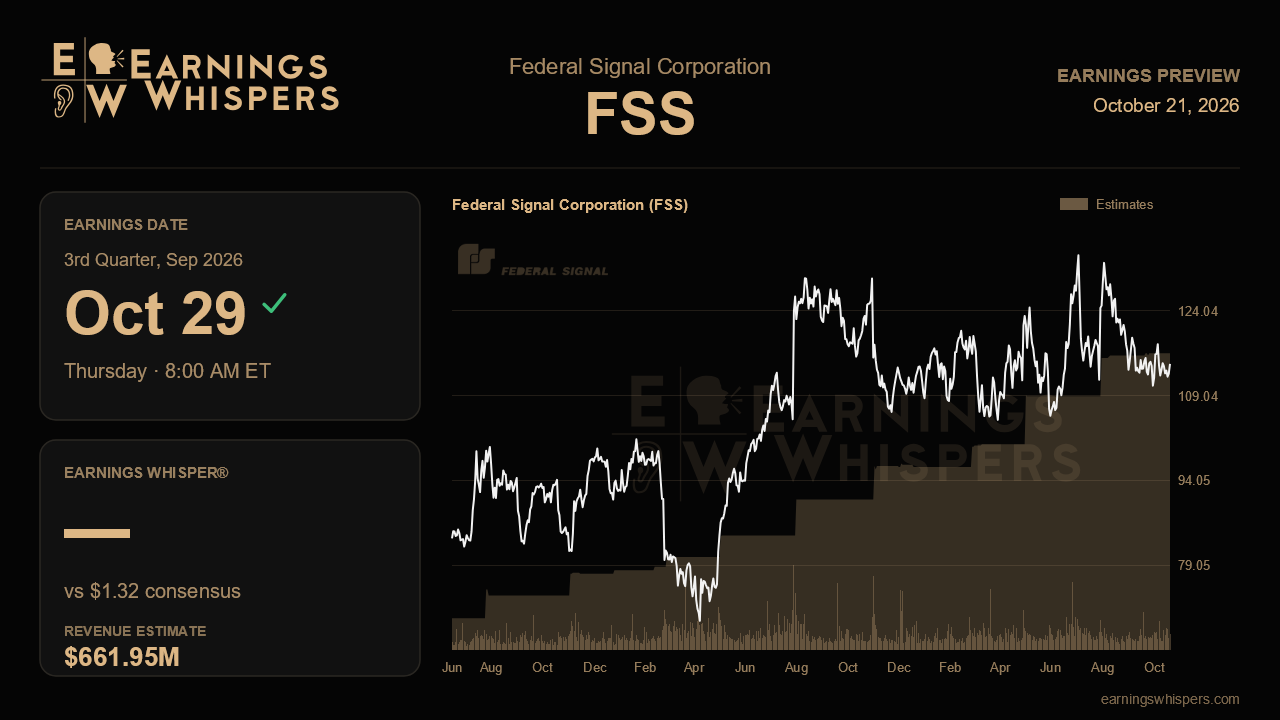
Federal Signal has spent 2026 doing almost everything a bull could ask for. It has raised full-year earnings guidance twice, expanded margins, generated cash at a striking clip and integrated its New Way and Mega acquisitions faster than planned. Yet the stock has slipped about 5% since its last report while the S&P 500 gained 4.5%. That gap suggests the market is less focused on the record quarter behind it than on the softer signals underneath: a shrinking backlog, slipping Safety and Security Systems orders and a refuse market management itself expects to decline. The third-quarter report on October 29 is the first real chance to show those soft spots are noise rather than a turn.
The Street is looking for adjusted earnings of $1.32 a share on revenue of $662 million. That would be up 15.8% and 19.3% from a year ago, which is strong growth on paper. Context matters, though. Both figures sit below the second quarter's $1.42 and $670.2 million, and much of the year-over-year revenue lift comes from acquisitions rather than organic demand, which ran closer to 6% last quarter. The sequential step down looks deliberate. Management warned of extra second-half SG&A spending to scale its centers of excellence, corporate costs are running higher on post-retirement and medical expenses, and capacity investment for its push to build more parts in-house is landing now. Consensus appears to bake that in rather than assume the second-quarter pace simply continues.
The bigger question is whether the raised full-year outlook of $5.12 to $5.30 in adjusted EPS, on sales of $2.58 billion to $2.67 billion, still holds after another quarter of evidence. Guidance has climbed about 60 cents at the midpoint since the initial range, so the bar for a third raise is higher, and a simple reaffirmation could be read neutrally or even mildly negatively by a skeptical tape. Management tied the low end of the sales range partly to the $44 million of remaining third-party Labrie refuse backlog, whose timing customers control. Any color on how much of that shipped in the quarter will help investors judge whether the range is tightening upward or drifting toward the bottom.
Backlog is the cleanest scorecard. It fell to $1.0 billion last quarter, down 8% from a year earlier, but management attributed roughly $75 million of the decline to the planned Labrie exit. If backlog stabilizes or rebuilds excluding Labrie, that validates the claim that underlying demand across Environmental Solutions remains broad and diversified across funding sources. Another meaningful drop would be harder to explain away. In Safety and Security Systems, orders of $89 million trailed the prior year and margin fell to 25.1% on mix, a sharp contrast with the first quarter's 26.6%. A rebound in orders, plus the first contribution from the Western Technology lighting acquisition that closed in early July, would support the newly lifted 22% to 28% through-cycle margin target. Street sweeper orders, the company's one pure municipal exposure, also deserve a look after last quarter's decline.
The aftermarket business offers a counterweight. It makes up roughly a quarter of Environmental Solutions revenue and grew 24% last quarter, with rental income up 16%. Continued double-digit growth there would cushion any equipment softness and support margin durability heading into 2027, which is where management increasingly wants the conversation to go.
Sentiment is essentially neutral, a hair less bearish than before the last report, and the stock at $114.66 sits just below its 200-day moving average and closer to the bottom of its post-earnings range than the top. Expectations are not stretched. The central issue is whether Federal Signal can show that orders and backlog, excluding the deliberate Labrie wind-down, are holding up well enough to justify a guidance range that has already been raised twice. If they are, the recent underperformance looks like an opportunity the numbers can correct. If they are not, the market's caution will have been early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-16 | |
| Jun-12 | |
| Apr-29 | |
| Apr-29 | |
| Apr-29 | |
| Apr-21 | |
| Apr-15 |
