Establishment Labs Faces A Seasonal Test Of Its US Boom After A 32% Slide
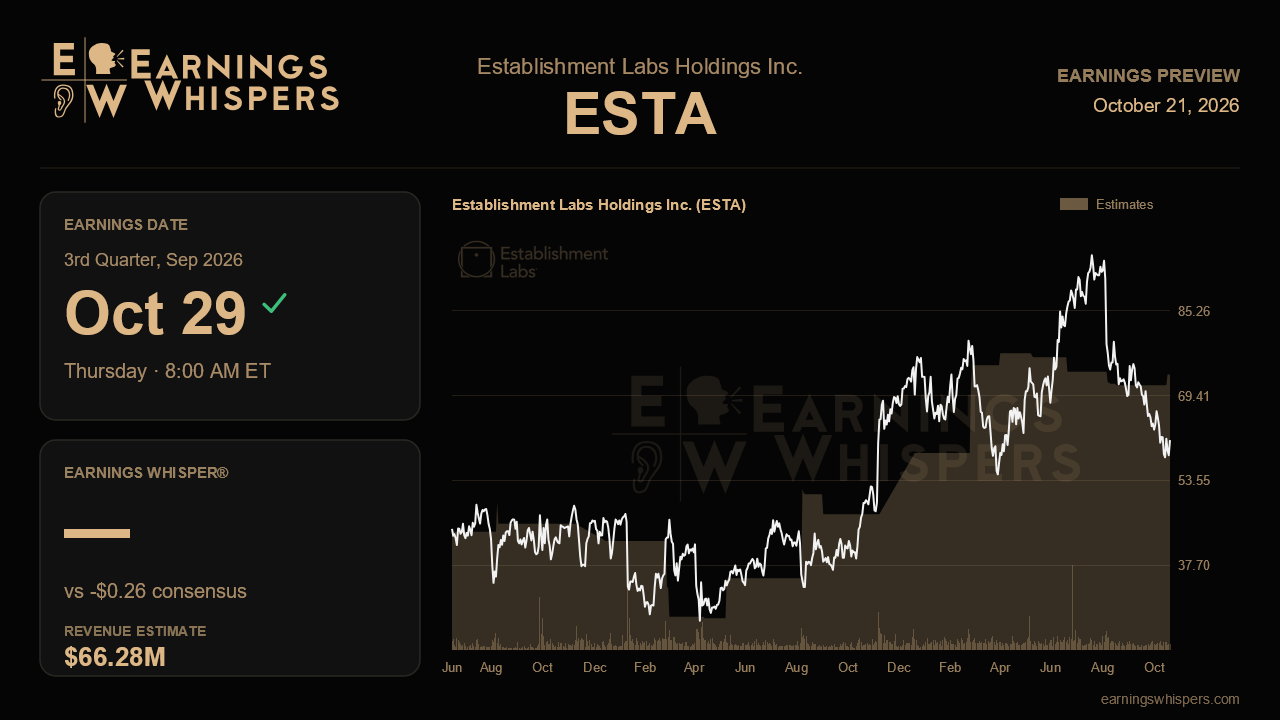
Establishment Labs heads into its third-quarter report with an odd disconnect. Management has raised its full-year revenue outlook three times in a row, US sales more than doubled last quarter, and the company finally produced positive overall cash flow. Yet the stock has lost nearly a third of its value since that report. The October 29 release, due before the open, has to show whether the American growth engine can carry the business through what management itself flagged as the seasonally softest quarter of the year, while a slowing international business drags on the totals.
The Street expects a loss of 26 cents a share, a meaningful improvement from the 38-cent loss a year ago, on revenue of about $66.3 million. That would be a solid 23% gain from the prior-year quarter but a slight dip from the $67.5 million booked in the second quarter. The seasonality explains the sequential step back. Full-year math matters more. Management now guides to $269 million to $271 million, yet consensus sits near $268 million, below the bottom of that range. Analysts are effectively discounting the company's own forecast. With the first half totaling roughly $127 million, hitting the midpoint requires about $143 million in the back half. A third quarter at or above consensus would leave a manageable fourth-quarter hurdle. A shortfall would put a heavy load on the final months and invite doubts about a fourth raise.
The US business is the core of the bull case, and the prior call gave plenty of metrics to track. US revenue reached $24.7 million, up about 141%, and rose to nearly 37% of sales from roughly 27% two quarters earlier. Accounts topped 2,000, and certified surgeons for Preserve, the minimally invasive procedure that carries a 30% to 50% premium for surgeons, passed 300 against a raised full-year target of 500. Validation this quarter would mean continued gains in US accounts and certified surgeons despite summer softness, along with minimally invasive revenue tracking toward management's goal of about 15% of sales and well above $35 million. Momentum there also supports the 2027 plan, which calls for roughly 25% growth and assumes reconstruction approval, where FDA site audits were already underway.
The risk is outside the US. International growth slowed to about 4% from roughly 15% in the first quarter. European direct markets still grew in the mid-teens, but distributor demand weakened, and Middle East orders, under 5% of revenue, are expected to stay depressed through year-end because of the regional conflict. If international sales slow further, or if weakness spreads beyond the Middle East, the narrative of a temporary pocket of softness gets harder to defend. Profitability is the other swing factor. Gross margin held flat near 70.6%, and second-quarter adjusted EBITDA of $3.7 million absorbed $2.2 million of one-time restructuring and refinancing costs. Without those charges, investors will look for operating leverage even in a lighter revenue quarter, and for cash to stay steady around the $71 million level, given management's statement that no further equity raises are needed.
Sentiment has soured noticeably, moving from mildly bullish before the last report to clearly bearish now. The shares, at about $61, sit well below their 200-day moving average near $72.50 and closer to the post-earnings low of $55 than to the $94 high. That deflated setup lowers the bar somewhat, though it also signals real skepticism.
The question is whether the US ramp is strong enough to outrun a cooling international business. If US growth and Preserve adoption keep compounding while international results stabilize, the guidance raises look credible and the selloff overdone. If seasonality and overseas weakness together pull the quarter short, the market's discount to management's outlook may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-19 | |
| Oct-05 | |
| Sep-21 | |
| Sep-05 | |
| Sep-01 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| Jun-29 | |
| Jun-25 | |
| Jun-16 | |
| May-07 | |
| May-07 | |
| Apr-30 |
