Granite's Record Backlog Faces A Peak-Season Test As Shares Lag Its Raised Outlook
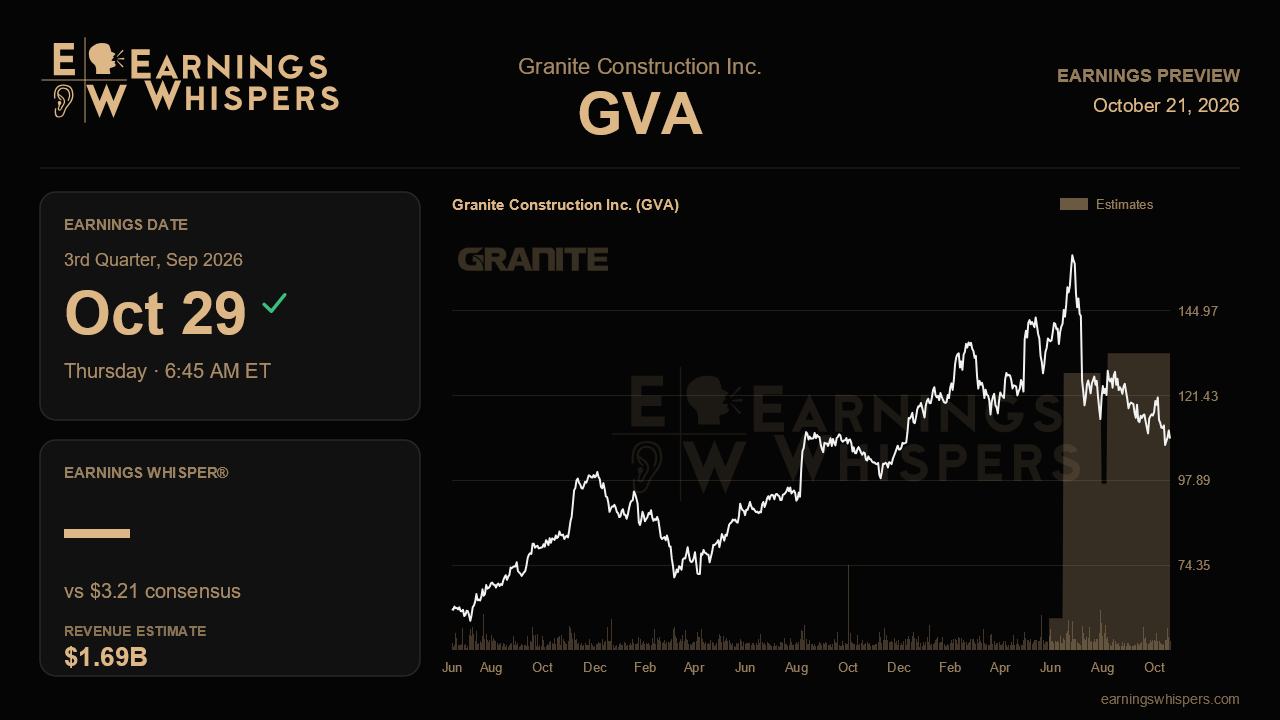
Granite Construction heads into its third-quarter report with an odd disconnect. Management has raised its 2026 revenue outlook at every opportunity, lifted its 2027 organic growth target above 10%, and built a record pipeline of contracted work. The stock, by contrast, has slipped 4.3% since the last report while the S&P 500 gained 4.5%. The peak construction season now has to show whether the operating story deserves more credit than the market has been willing to give.
The Street expects earnings of $3.21 per share on revenue of $1.69 billion, gains of roughly 19% and 18% from a year ago. That is strong growth, and a big step up from the second quarter's $2.10 on $1.46 billion. Some of the jump is normal: the third quarter is when paving crews and quarries run hardest. Management's full-year range of $5.3 billion to $5.5 billion was raised from $5.2 billion to $5.4 billion. That followed earlier increases from a range that once sat near $4.4 billion. Consensus of $5.32 billion sits near the bottom of the current band, so analysts have not fully bought the latest raise. A solid quarter that pushes the full-year math toward the midpoint would close that gap. If results only keep the low end in reach, the guidance momentum would look less convincing.
The biggest single thing to check is the materials business. Second-quarter materials gross margin fell 800 basis points. Management pinned the damage on roughly $10 million of severe Southeast weather and about $5 million of quarry development costs. It called both temporary, said the delayed tons would shift into later quarters, and said it expected no similar drag in the second half. It also reaffirmed its 2026 and 2027 materials margin targets. The third quarter is the cleanest test of that claim. Strong volumes, aggregate pricing still holding in the mid-single digits, and a sharp margin rebound would confirm the weather explanation. Another soft margin in the busiest months would suggest something more structural.
On the construction side, the backlog of contracted work is the scoreboard. That backlog, which Granite calls CAP, reached a record $7.4 billion, its fourth straight quarterly increase. Further growth would support the higher 2027 target. A flat or shrinking total would make that target harder to defend, particularly because the main federal highway funding law has lapsed. Its proposed successor, the Build America 250 Act, faces uncertain timing and funding levels. Data centers are a newer swing factor. Data center CAP climbed to $223 million from about $65 million a year earlier, and Granite has launched a dedicated division for that work. Continued growth there would show diversification beyond public highway spending. Cash flow matters too, since management raised its operating cash flow target to 11% of revenue after a strong first half.
The headline numbers may also be noisy. A $270 million debt discount tied to the called convertible notes is set to hit third-quarter interest expense, which will distort reported results. Calling the notes should also cut the adjusted diluted share count by about 2 million, a modest help to per-share figures. Management also flagged $200 million to $400 million of additional acquisitions in the second half. Any deal announcements, and early returns from the recently closed Kenny Saine acquisition, will shape how much growth comes from buying versus building.
Sentiment has swung sharply, with bullish readings jumping to 78.2% from 30.6% before the prior report. The tape tells a more skeptical story. At $109.51, shares sit well below the 200-day moving average of $126.84 and near the bottom of their post-earnings range of $104.59 to $129.46. That entire range sits beneath the prior quarter's band. Optimism is high among those surveyed, but the stock price already reflects plenty of doubt. Ultimately, the report turns on whether the materials margin snaps back as promised while backlog keeps climbing. If both happen, the raised outlook looks earned. If either stalls, the market's caution may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Oct-15 | |
| Oct-06 | |
| Oct-01 | |
| Sep-29 | |
| Sep-17 | |
| Sep-10 | |
| Sep-09 | |
| Aug-26 | |
| Aug-12 | |
| Aug-07 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
