Fortrea's Raised Outlook Faces Its First Real Test As Street Stays Below Guidance
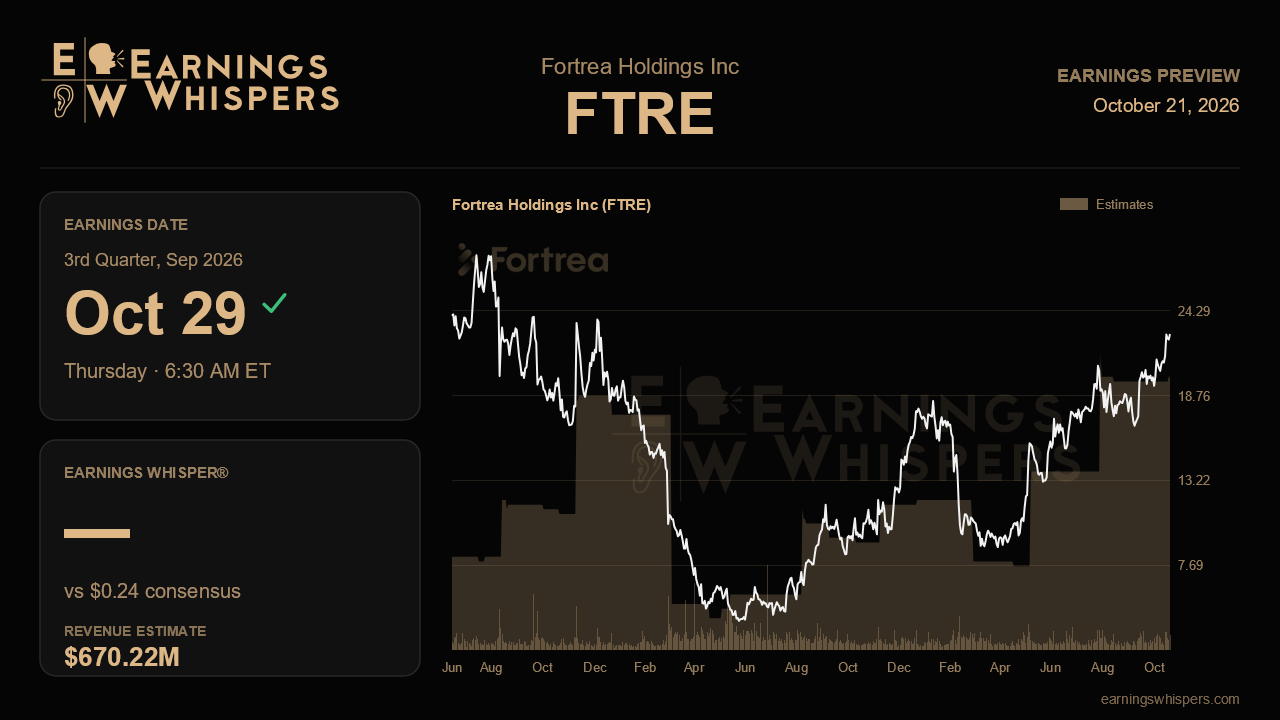
Fortrea enters its third-quarter report with an unusual setup: management raised its full-year outlook three months ago, yet Wall Street still has not fully bought in. The contract research organization lifted its 2026 revenue forecast to $2.62 billion to $2.69 billion, up from $2.55 billion to $2.65 billion, while the consensus sits at roughly $2.61 billion, below even the bottom of the new range. That gap between what the company says and what analysts are willing to model is the central tension heading into the October 29 release before the opening bell.
For the quarter itself, analysts expect earnings of $0.24 per share, double the $0.12 earned a year ago, on revenue of about $670.2 million, down 4.4% from $701.3 million. That pairing tells the story of Fortrea's current phase. The top line is still shrinking, weighed down by lower pass-through costs and lingering weakness in its functional service provider business, but profitability is moving the other way as cost actions, better mix and operating leverage take hold. The revenue estimate is also slightly below the $678.2 million reported last quarter, so a modest sequential dip is already baked in.
The margin side looks well supported. Adjusted EBITDA climbed to $58.7 million in the second quarter from $47 million in the first, putting the first half at roughly $106 million. With full-year guidance raised to at least $205 million, the back half needs only about $50 million per quarter, comfortably below the recent run rate. Either management built in a cushion or it anticipates some cost pressure, and the third-quarter figure should clarify which. A result near the second-quarter level would make the floor look conservative; a meaningful slide would raise questions about how durable the cost savings are. Free cash flow, which swung from negative $25 million in the first quarter to positive $19.9 million in the second, also needs to stay in positive territory to show the improvement is not just timing.
The demand picture is where the narrative gets its toughest test. Trailing twelve-month book-to-bill rose to 1.12x, the fourth straight quarter above 1.0x, and first-half net new awards grew 19%. But the quarterly ratio slipped to 1.06x from 1.15x, and backlog sat flat at $7.8 billion. Management attributed much of the dip to stronger revenue inflating the denominator, an explanation that holds up only if bookings rebound now. A quarterly figure back above 1.1x alongside backlog growth would confirm that strength in clinical pharmacology, new biotech customers and the China out-licensing pipeline is translating into future revenue. Another soft print would suggest the guidance raise borrowed from faster burn rather than broader demand. Commentary on whether its AI-enabled trial tools are actually winning bids, rather than just appearing in proposals, would add color.
The finance leadership situation is the wild card. The incoming CFO was blocked by litigation tied to a prior employer, a board member is serving on an interim basis, and the longtime finance chief is leaving. Any update on a permanent hire would ease concerns about continuity at a delicate moment.
The market has already leaned in. Shares are up 16.3% since the last report, beating the S&P 500 by more than 12 points, and at $22.78 the stock trades far above its 200-day average of $15.45 and within about 3% of its post-earnings high of $23.55. Sentiment, meanwhile, has cooled slightly to 16.9% bullish from 20.9%, hinting that the rally has outrun conviction. Ultimately, the report hinges on whether bookings reaccelerate enough to justify the raised revenue range, because steady margins alone may not be enough to push the stock through resistance.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-19 | |
| Oct-05 | |
| Sep-22 | |
| Sep-10 | |
| Sep-10 | |
| Sep-02 | |
| Aug-13 | |
| Jul-29 | |
| Jul-29 | |
| Jul-13 | |
| Jun-26 | |
| Jun-10 | |
| Jun-02 | |
| May-05 |
