OFG Bancorp Beats On EPS, But The Margin Story Turns As Fed Hike Lifts Funding Costs
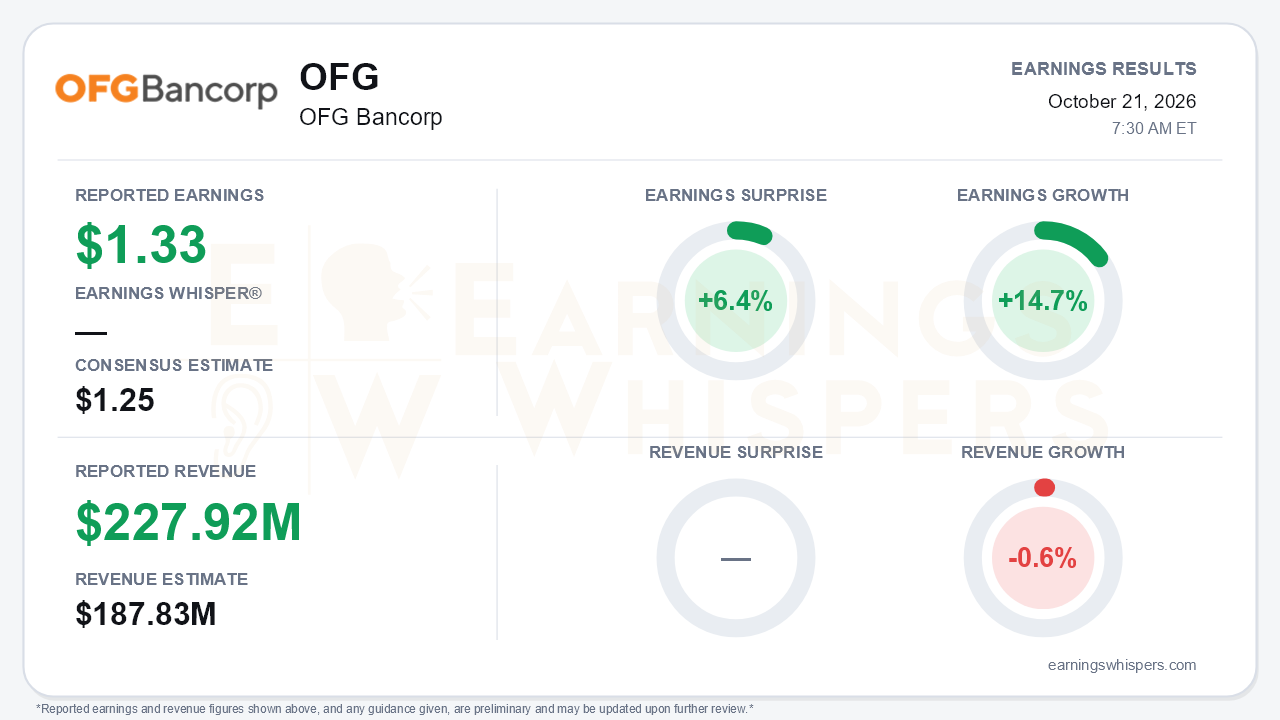
OFG Bancorp delivered a clean headline beat in the third quarter, earning $1.33 per share against a $1.25 consensus, a 6.4% surprise, with earnings up 14.7% year over year. That growth is decelerating, though. Year-over-year EPS growth has slowed from 26% in the first quarter to 21% in the second and now 15%, and EPS slipped from $1.39 in 2Q26. More important, the net interest margin story that had driven three straight guidance raises has reversed. Margin is the central tension. Commercial lending and credit improved this quarter, but an unexpected September Fed hike pushed funding costs higher, and management trimmed its second-half margin outlook to the bottom of its prior range.
The revenue comparison needs context. Earnings Whispers shows revenue of $227.92 million, 21.3% above the $187.83 million consensus but down 0.6% year over year. That figure appears to be a gross measure: $195.7 million of interest income plus $32.2 million of banking and financial service revenues. On the company's own core revenue basis, which nets out interest expense, revenue was $185.7 million. That is up 1.0% from a year ago, down from $190.3 million in 2Q26, and slightly below the consensus figure. The large revenue surprise therefore looks more like a difference in definitions than genuine top-line outperformance. Core revenue was essentially flat. Pre-provision net revenue rose modestly to $89.9 million from $87.5 million, but only because non-interest expense fell to $96.3 million after $5.8 million of operational charges in 2Q26 did not recur. Interest income fell $1.4 million sequentially, mostly because the second quarter included a $4.1 million benefit from commercial loan payoffs. Interest expense rose $2.3 million as deposit balances repriced higher.
The call explained what changed beneath the numbers. Reported net interest margin fell to 5.23% from 5.45%. Management now expects about 5.25% for the rest of the year. Its guidance had climbed from 4.95%–5.05% to 5.10%–5.20% and then to 5.25%–5.35%, so this is the first step backward. Core deposit costs rose 5 basis points to 1.34%, driven by two forces:
- clients moving into time deposits;
- government deposits linked to the 3-month T-bill repricing higher.
In the second quarter, management had expected deposit costs to stay flat. End-of-period core deposits fell $80 million as demand and savings balances declined. OFG added $131 million of borrowings and brokered deposits for liquidity and cut cash by $179 million to fund loans and a $216 million mortgage-backed securities purchase. The balance sheet is becoming less liquid at the margin.
The offsets are real. Loans held for investment grew $151 million, or 1.8% sequentially and 4.1% year over year, on a late-quarter surge in Puerto Rico commercial lending. That already meets the low-single-digit growth guidance. Management called it a "banner year" for Puerto Rico commercial lending and cited a strong pipeline, although new production fell to $694 million from $755 million. Credit improved:
- The commercial nonperforming loan rate fell to 0.68% from 0.90%.
- Total net charge-offs declined to 0.70% and nonperforming loans to 0.74%.
- Both rates were lower sequentially and year over year.
Rate hikes could help over time. About $550 million of a $1.7 billion variable-rate commercial book repriced late in the quarter, and management assumes another 25 basis point hike in December. Buybacks resumed at $13.5 million, with $180 million of authorization remaining. Bears still have legitimate ammunition:
- Auto delinquencies rose seasonally and were modestly higher year over year.
- Provision guidance moved to $18–20 million.
- Management flagged energy costs, inflation and local economic "noise."
- Tangible book value fell to $29.66 from $31.12 on securities marks, and the tangible common equity ratio dropped to 10.34% from 10.90%.
Investors grew noticeably more cautious ahead of the report. Earnings Whispers sentiment fell from -0.23 to -0.45, deepening a negative reading. The stock has not reflected that pessimism. Shares closed at $52.95 before the release, up 2.5% from the open after the July report and 14.2% above the 200-day moving average. They sit 2.8% below the 52-week high of $54.47 set in August, after rebounding 8.1% from an October 1 low. Momentum and AVWAP trend readings are positive. The market setup is more complicated than the surprise implies: the stock entered the report near the top of its range while sentiment was souring.
The bottom line is that OFG beat earnings estimates on solid commercial growth, cleaner credit and lower expenses. But the margin expansion that underpinned its earnings acceleration has stalled under rising funding costs and deposit migration, and EPS growth keeps decelerating. With shares near their highs and sentiment deteriorating, the next leg depends on whether variable-rate loan repricing can outrun deposit costs.
Read our earnings preview for OFG Bancorp: https://www.earningswhispers.com/article/OFG/20431
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Sep-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-21 | |
| Jul-21 | |
| Jul-12 | |
| Jun-22 | |
| Apr-22 | |
| Apr-22 | |
| Apr-21 |
