Lithia Beats On Used-Car Profits And A Shrinking Share Count, But Lower Adjusted Net Income Tempers A Clean-Looking Quarter
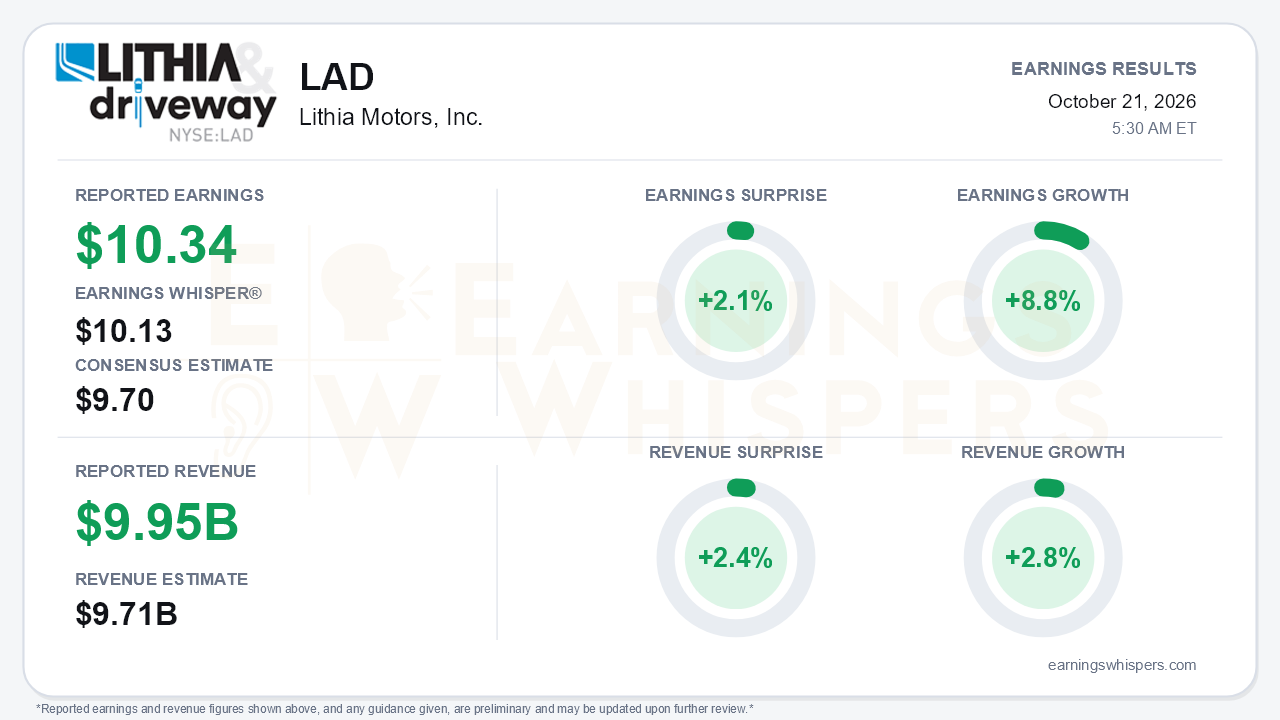
Lithia Motors delivered a beat that holds up better at the per-share level than at the business level. Adjusted EPS of $10.34 topped the $9.70 consensus and cleared the $10.13 Earnings Whisper by 2.1%. Revenue of $9.947 billion beat the $9.71 billion consensus by 2.4%. Adjusted earnings grew 8.8% from a year ago, and revenue rose 2.8%. Both are faster than the company's nine-month pace of 4% adjusted EPS growth and 2% revenue growth, so the quarter marks a modest acceleration. That is the central tension: adjusted net income fell 5% to $229.3 million, while diluted shares dropped 12.7% to 22.0 million. Lithia's EPS growth this year has come from capital allocation more than operating expansion, and the call suggested that lever is now being used more sparingly.
The headline GAAP figure deserves a discount. Diluted EPS of $13.22, up 54%, includes a $2.95 per-share unrealized gain on the Pinewood Technologies stake, which came as Ridgeview Partners' acquisition of Pinewood AI closed. Strip that out and the core business barely moved. Adjusted EBITDA rose just 1.3% to $443.5 million, and trailing-twelve-month adjusted EBITDA is down 4.4%. Operating income was essentially flat. Floor plan interest expense climbed 21.6% as inventories grew. On a same-store basis, revenue fell 1.4% and gross profit declined 1.6%. New and used retail units were each down roughly 3%, and domestic new units fell 8.8%.
The mix shift beneath those numbers is where Lithia earned its beat. Same-store used vehicle gross profit per unit jumped 13.3% to $1,993, up from $1,680 in the first quarter. Management described roughly $2,000 as a floor heading into 2027. Aftersales gross margin expanded to 59.5% from 59.2% in the second quarter and 58.7% in the first. North America SG&A improved to 65.7% of gross profit from 66.2%. Driveway Finance posted record originations of $937 million at an 18.3% penetration rate. Its loan-loss allowance improved to 2.8% from 3.1%, and management raised its midterm financing-income outlook for a second straight quarter.
Bears still have legitimate ammunition. Aftersales gross profit growth has decelerated every quarter, from 9.8% in the fourth quarter of 2025 to 2.4% now. U.S. customer-pay was flat and repair orders were slightly lower. F&I per unit fell to $1,736 from $1,811 in the second quarter, partly because affordability-pressured buyers are skipping service contracts. UK gross profit growth slowed to 7% from 12%. New vehicle gross profit per unit dropped 6%, and total vehicle gross profit per unit slipped to $3,958 from $4,119. Financing operations income fell sequentially to $32 million from $37 million, which management attributed to seasonality. Net interest margin edged down to 4.7%, and management flagged that rising rates could lift Driveway Finance funding costs faster than it can reprice loans. Management also warned that the fourth quarter is seasonally the toughest.
The capital story is changing as well. Buybacks fell to $85 million from $242 million in the second quarter and $259 million in the first. Net debt to adjusted EBITDA stands at 3.07x, above the sub-3x target and up from 2.63x a year ago, and management signaled a near-term tilt toward deleveraging. With the share count already 8.7% lower this year, the per-share tailwind should fade unless operating profit starts growing on its own. Forward catalysts include:
- the Memphis Hyundai/Kia acquisition, adding about $250 million in annualized revenue;
- the hiring of former Toyota Financial Services CEO Scott Cook as Operations President;
- AI-driven service pre-sales in the UK;
- possible Chinese OEM franchises in Canada.
The market had already turned skeptical. Shares spiked to a 52-week high of $439.49 on the first trading day after the July report and then gave all of it back. The stock entered this report at $299.53, down 20.5% from that session's open and 31.8% below the high. It sits 3.1% below its 200-day moving average and only 7.9% above the October 14 low of $277.59. The second-quarter buybacks at an average of $345 now look early. Investor sentiment weakened from 0.12 to 0.02, leaving it close to neutral rather than outright negative. Price and AVWAP trend readings remain negative, although momentum has turned positive.
The bottom line is that Lithia delivered a credible beat driven by used-vehicle profitability, aftersales margins and a growing finance arm, but the per-share growth rests heavily on a smaller share count while adjusted net income and same-store gross profit declined. With buybacks slowing to prioritize leverage, the next leg of EPS growth has to come from the operations. That makes the durability of the $2,000 used-vehicle profit floor and a stabilization in aftersales growth the metrics that matter most for a stock still trading near its post-July lows.
Read our earnings preview for Lithia Motors, Inc.: https://www.earningswhispers.com/article/LAD/20426
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 8 hours | |
| 15 hours | |
| 15 hours | |
| 15 hours | |
| Oct-15 | |
| Oct-09 | |
| Oct-08 | |
| Oct-06 | |
| Sep-29 | |
| Sep-08 | |
| Sep-01 | |
| Aug-25 | |
| Aug-18 | |
| Aug-04 | |
| Jul-31 |
