IDACORP's Summer Quarter Tests Whether Data Center And Fab Load Can Outrun Dry Hydro
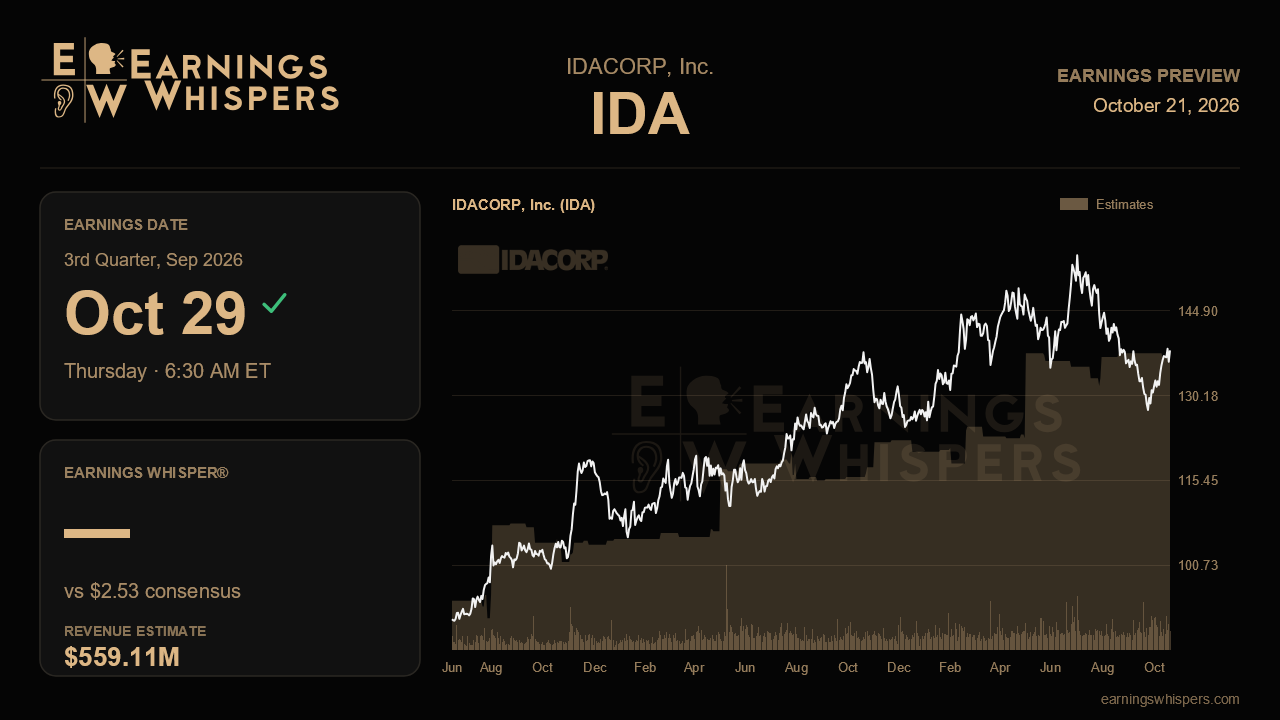
IDACORP heads into its seasonally most important quarter with a story that has finally moved from promise to proof. Last quarter management argued that years of planning for large industrial customers had begun turning into real revenue, and it backed that claim by lifting the bottom of its full-year earnings range. The stock has not followed the narrative. Shares have fallen 5.7% since that report while the S&P 500 gained 4.5%, leaving IDACORP about 10 points behind the market just as the summer quarter puts the large-load thesis to its biggest test yet.
Wall Street expects third-quarter earnings of $2.53 a share on revenue of $559.1 million. That would be 12% EPS growth from $2.26 a year ago on revenue growth of 6.6%, a solid result for a regulated utility. The gap between the two figures matters. Earnings growing nearly twice as fast as sales suggests analysts expect new industrial volumes and recently added rate base to carry operating leverage, not just higher fuel or power cost pass-throughs. Management's full-year range now sits at $6.30 to $6.45, narrowed from $6.25 to $6.45, and the $6.39 consensus lands slightly above the midpoint. With $3.00 already earned in the first half, the Street is implicitly assuming a strong summer followed by a modest fourth quarter. A third-quarter miss would quickly push that full-year figure toward the lower half of the range.
The cleanest proof of the thesis will be the new reconciliation line management created for large contract customers, which added $6.5 million to operating income in the second quarter and was expected to grow in the back half. This quarter should include a full three months of Micron's first fab, which contributed only about a month last quarter, along with further ramping at Meta. Industrial revenue rose 17% year over year in the second quarter. Another double-digit gain, plus a clearly larger contribution from the large-customer line, would confirm that the ramp is arriving on schedule. A flat or shrinking contribution would raise questions about how fast these customers are really drawing power.
Earnings quality is the second test. In the first half IDACORP used only $6.3 million of its tax-credit amortization cushion, compared with $36.5 million a year earlier, and management halved its full-year expectation to less than $15 million. That leaves roughly $8.7 million of headroom, so investors should watch whether the summer result leans on that cushion. Hydro is the obvious swing factor. Management trimmed its generation outlook for the third straight quarter, to a top end of 6.5 million megawatt-hours, after a dry May and June. Less hydro typically means more purchased power during peak demand. Power cost adjustment mechanisms soften that blow, but they do not remove it entirely.
Several loose threads could also shape the conversation. The company expected a shortlist for its 2032 resource solicitation during the third quarter, with several of its own projects competing, and any self-build wins would add to a capital budget already heading toward the top of its $1.3 billion to $1.5 billion range. A signed power agreement for Micron's second fab remains the largest piece of upside not yet in the plan. Updates on the Mountain Home wildfire investigation and on whether last quarter's soft operating cash flow really reflected timing also deserve attention, as does the outlook for a likely mid-2027 rate case.
Sentiment has improved modestly from the prior quarter but remains only mildly bullish, and the stock trades at $138.04, just under its 200-day moving average and in the middle of a post-earnings range that sits below last quarter's band. Expectations have reset lower even as fundamentals appear to have improved. The question for this report is straightforward. Can large-load revenue grow fast enough to deliver double-digit growth through a dry summer without leaning on tax credits? If it does, the gap between the operating story and the share price becomes hard to justify.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Sep-18 | |
| Sep-10 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-22 | |
| Jul-16 | |
| Jul-16 | |
| May-30 | |
| May-01 | |
| May-01 | |
| Apr-30 |
