Northpointe Misses Badly On Rate Marks And Fraud Loss, But The Real Story Is Its Exit From Mortgage Origination
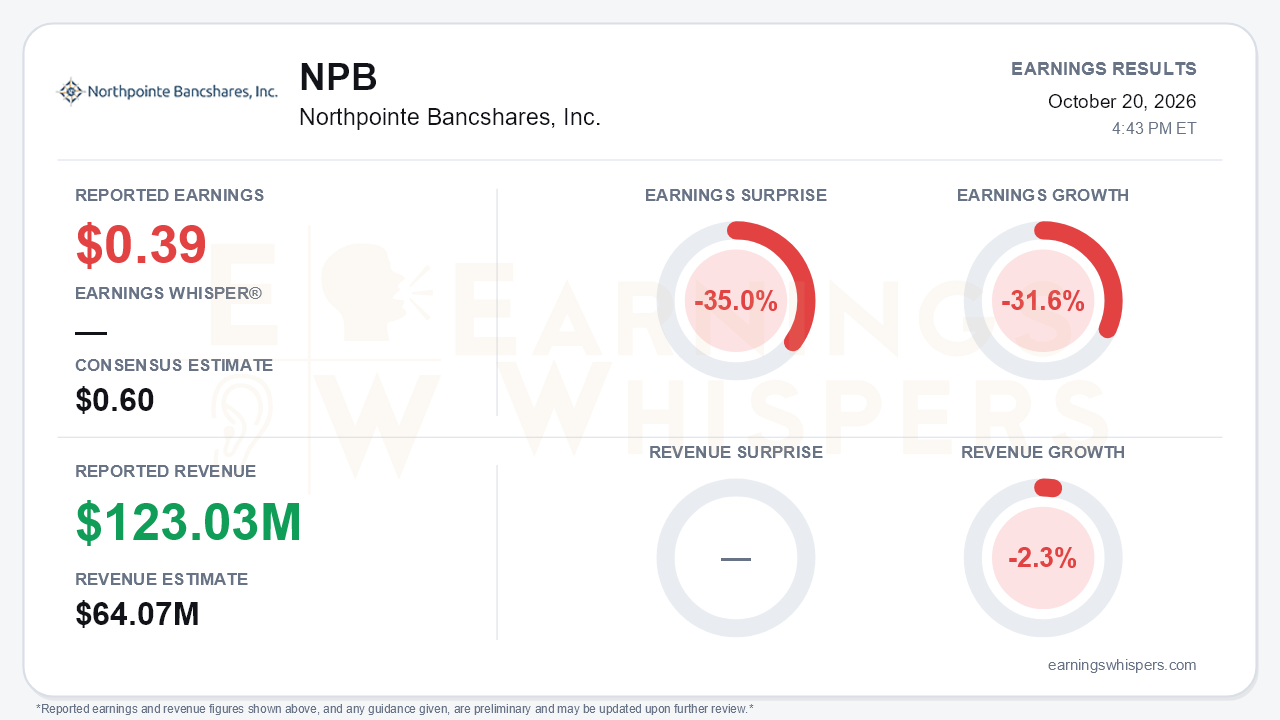
Northpointe Bancshares (NYSE: NPB) delivered a clear third-quarter miss. It earned $0.39 per diluted share against a $0.60 consensus, a 35.0% shortfall, and earnings fell 31.6% from a year ago. The deterioration is also sequential: EPS has slid from $0.62 in the first quarter to $0.60 in the second and now $0.39. The headline miss, however, is not the most consequential news in the release. Management announced a non-binding letter of intent to sell its distributed retail and consumer direct mortgage origination channels to CMG Financial. That effectively ends a gain-on-sale business that has defined a large part of the company's earnings profile. The central tension is whether a smaller, balance-sheet-driven model built around the Mortgage Purchase Program (MPP) and All-in-One (AIO) loans can earn more than the volatile franchise it replaces.
The quality of the miss deserves scrutiny, because a meaningful share of it came from two items. A $9.3 million decline in the fair value of held-for-investment loans and the lender risk account was only partly offset by a $5.0 million gain on mortgage servicing rights, leaving a net $4.3 million hit tied to higher long-term rates. A separate $3.1 million operational loss stemmed from an external deposit fraud at a retail banking center. Insurance recovery is being pursued but is uncertain. Even so, the core mortgage engine was weak. Originations fell 26% sequentially to $493 million. Gain on sale excluding fair-value items dropped to $11.5 million from $16.4 million in the second quarter. The efficiency ratio jumped to 64.47% from 54.76%. On revenue, the supplied $123.03 million beat consensus by 92.0%, but that figure appears to be measured on a broader basis than the estimate. Net interest income plus non-interest income, a narrower measure, actually fell to about $55.9 million from roughly $64.3 million in the second quarter. Investors should not read the revenue surprise as a sign of top-line strength.
Beneath the noise, the spread business held up reasonably well. Net interest income rose $1.2 million to $43.7 million on a $157 million increase in average earning assets. Net interest margin slipped only 1 basis point, to 2.32%. MPP balances grew $262.7 million, a 27% annualized pace and far stronger than the $77.3 million added in the second quarter, as participations fell to $368.3 million and capital was redeployed onto the balance sheet. AIO balances rose $100.4 million. That increase included an $85.4 million seasoned loan purchase at a discount, at a roughly 7.5% effective yield, which management framed as a repeatable sourcing model. Credit remained benign on losses, with net charge-offs of just 2 basis points. Non-performing assets, however, rose $8.9 million to $95.5 million.
The call supplied the forward case. Management guided to $50-55 million of annualized expense savings and 2027 non-interest expense of $80-95 million, versus $140-146 million in 2026, and said those savings exceed the lost revenue. Initial 2027 targets call for:
- net interest margin of 2.4-2.6%;
- MPP balances of $4.7-5.0 billion;
- AIO and consumer loans of $1.3-1.5 billion.
The quarterly dividend rises to $0.03, and a buyback plan is in development. Bears have legitimate ammunition, though. MPP yields have compressed from 6.98% in the fourth quarter of 2025 to 6.27% amid competition from large originators. New MPP client additions slowed to four clients totaling $185 million, from 11 clients totaling $380 million. The 2026 margin guide has been stepped down repeatedly over the year. Other near-term changes also cut against the story:
- MPP fee guidance was cut;
- wholesale funding ticked up to 63.94%;
- 2027 provision expense is expected to rise to $5-6 million;
- restructuring charges of $6-7 million will land mostly in the fourth quarter.
Management's tone shifted noticeably, from confident growth earlier in the year to restructuring language, including an admission that origination was no longer viable.
The market had already been skeptical. Shares closed at $15.78 on report day, down 9.8% since the open after the July report and about 9.4% below the 200-day moving average of $17.42. They also trade below tangible book value of $17.32. Investor sentiment, already negative, weakened modestly from -0.40 to -0.45, and the AVWAP trend reading remains negative. Investors have been treating NPB as a deteriorating story rather than a transition, and this print gives that view near-term support.
The bottom line is that Northpointe's quarter was poor on its face, and the exit from origination removes a revenue line with no near-term replacement. The 2027 framework of sharply lower expenses, a higher margin, and continued MPP and AIO growth offers a credible path to a steadier earnings profile. Execution is the key variable. The CMG deal is still non-binding, MPP pricing is under pressure, and management's margin guidance has slipped all year. Until those risks ease, the restructuring is a promise rather than a proven improvement.
Read our earnings preview for Northpointe Bancshares, Inc.: https://www.earningswhispers.com/article/NPB/20410
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-06 | |
| Sep-21 | |
| Aug-28 | |
| Aug-06 | |
| Jul-22 | |
| Jul-22 | |
| Jul-21 | |
| Jul-06 | |
| Jun-22 | |
| May-20 | |
| Apr-23 | |
| Apr-22 |
