Marcus Corp Needs Hotels To Carry A Nearly 50% Earnings Jump As Caution Builds
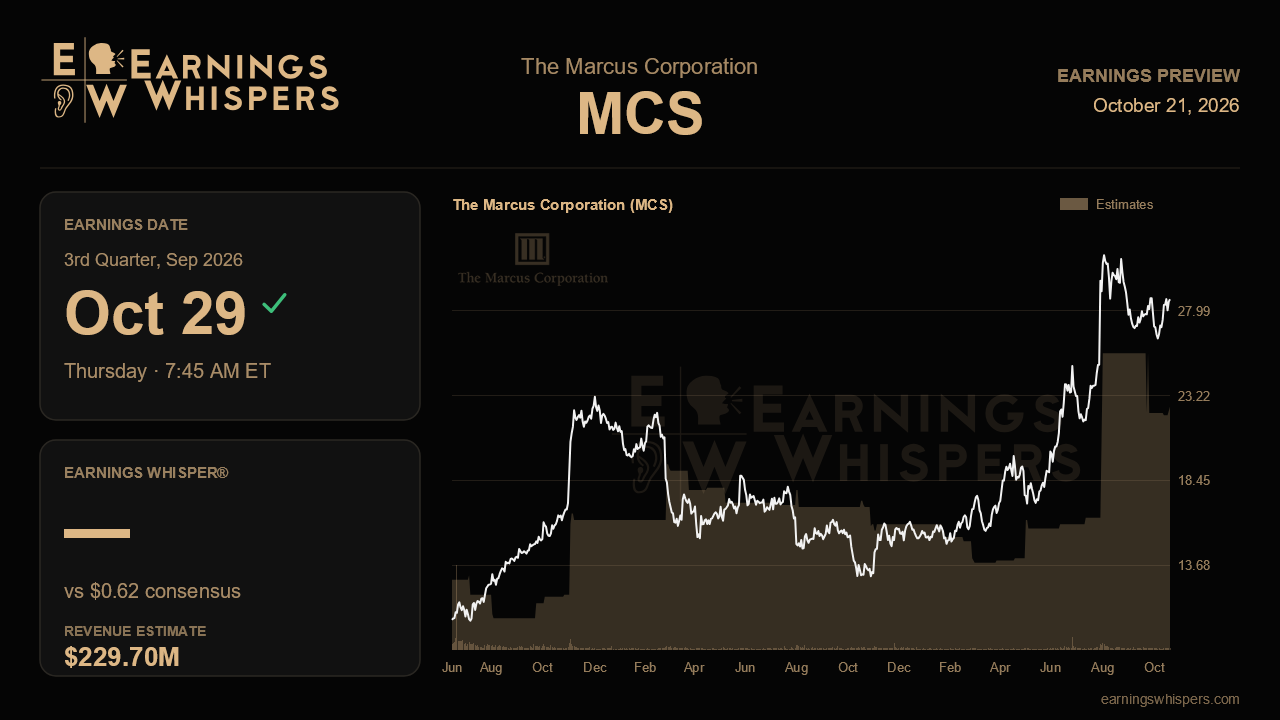
The Marcus Corporation enters its September-quarter report with an odd mismatch. The stock has re-rated sharply and the hotel business is running hotter than it has in years, yet management refused to lift its full-year outlook last time, and trader sentiment has swung decisively negative. The October 29 release, due before the open, will show whether that caution was prudent conservatism or an early sign that the hotel surge is cooling.
The Street is asking for a lot. Consensus calls for earnings of $0.62 a share, up about 48% from $0.42 a year ago, on revenue of $229.7 million, a gain of roughly 9%. That revenue figure is actually a touch below the $231.7 million posted last quarter, so the bet is less about top-line acceleration than about converting sales into profit far more efficiently than a year ago. Margin expansion is doing the heavy lifting in that forecast, and it leaves little room if costs or mix move the wrong way.
Hotels are where that leverage should come from. Revenue per available room was up about 15% through the first half, building on a 13.7% gain in the first quarter, as renovated properties such as the Pfister, Grand Geneva and Hilton Milwaukee took share. The year-ago third quarter also looks like a forgiving comparison: reported RevPAR slipped 1.5% then because the business was lapping the prior year's convention-driven surge in Milwaukee, even though underlying growth ran about 7.5%. With roughly 80% of the remaining year's group business already booked, and management describing those incremental dollars as high margin, a strong hotel print would validate the thesis. The warning signs would be a meaningful slowdown in RevPAR growth, or commentary that group pace has slipped further from the low-to-mid single-digit lead it held earlier this year after starting near 14%. Management flagged short booking windows and sensitivity to broader economic activity, and it noted the World Cup did nothing for its markets, so any softness in transient demand will get scrutiny.
Theaters are the slower story. Studios including Universal, Sony and Paramount have begun putting longer exclusive windows into practice, which management called clearly positive while cautioning that the benefit would take more than a year to show up. Investors should not expect this quarter's attendance to reflect that shift, but any early read on whether longer windows are supporting per-film performance or concession spending would strengthen the case. On cash, the heavy renovation cycle is over, with capital spending guided to $50 million to $55 million this year versus $75 million to $85 million last year. Continued free cash flow improvement, and any word on how that cash will be deployed given that acquisitions remain stalled by costly theater leases and a sluggish hotel deal market, matters for valuation.
The expectations backdrop has shifted. Sentiment has flipped from moderately bullish heading into the last report to clearly bearish now, even as the stock has gained 7.8% since then, beating the S&P 500 by about 3 points. Shares trade at $28.64, well above the 200-day average near $21.45 and comfortably above last quarter's entire range, though they sit closer to the middle than the top of the post-earnings band between roughly $26 and $32.42. The market has already priced in much of the turnaround, and skeptics appear to be positioning for a stumble.
Ultimately, the report hinges on whether hotel strength persisted into the summer quarter strongly enough to justify a near 50% earnings gain, and whether management now feels confident enough to firm up its full-year view. Another cautious hold with decelerating hotel metrics would challenge the improvement narrative, while robust RevPAR and steady group pace would suggest last quarter's restraint was simply conservatism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Sep-28 | |
| Sep-09 | |
| Sep-08 | |
| Aug-25 | |
| Aug-04 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-17 | |
| Jul-16 | |
| Jul-01 |
