Sonic Automotive's 39% Slide Puts Echo Park Volume Push And Fixed Ops Under Scrutiny
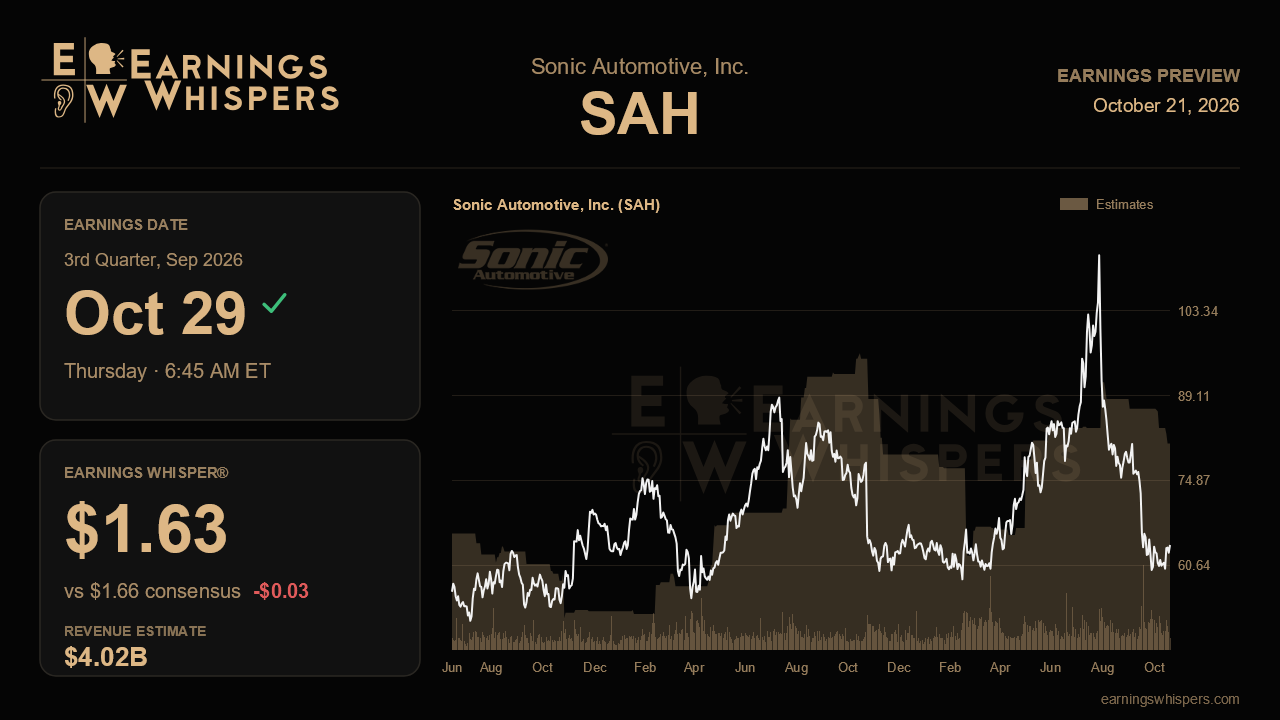
Sonic Automotive heads into its third-quarter report with a striking disconnect. Three months ago management sounded more confident than it had in years, raising its floor for new-vehicle gross profit per unit, restarting Echo Park store growth and describing the richest acquisition pipeline of the CEO's career. Since then the stock has fallen about 39%, trailing the S&P 500 by nearly 44 percentage points. The October 29 report, due before the open, has to show whether that optimism still holds or whether the market correctly saw softer margins coming.
The Street expects adjusted earnings of $1.66 a share on revenue of about $4.02 billion. That would be roughly 18% earnings growth from the $1.41 earned a year ago, but revenue would rise only about 1%. The gap shows the story is about margins and costs, not a sales boom. The forecast is also below the $1.82 Sonic earned last quarter, so analysts are already building in the second-half per-unit profit compression management flagged. The Earnings Whisper of $1.63 sits slightly below consensus. The difference is small, but it suggests the informal bar is no higher than the published one.
The cleanest test is new-vehicle profitability. Management raised its full-year range for new-vehicle gross profit per unit to $2,850 to $3,000, citing less downside risk. Yet same-store new GPU in the second quarter was $2,872, down 16% from a year earlier as Sonic lapped pre-tariff buying. That figure is already near the bottom of the raised range. A third-quarter number that holds near or above $2,850 would support the case that new-vehicle margins have found a floor. A reading below it would undercut the raised guidance only one quarter after it was issued.
Echo Park is the growth story, and management is accepting lower margins to get more volume. Used units rose 17% in the second quarter, and July was running 20% to 25% ahead. Management also cut its full-year Echo Park gross profit per unit range to $3,100 to $3,300. More vehicles sourced outside auctions, which reached 42% of sales, should help cushion the margin hit. What would validate the strategy is volume growth staying in that 20%-plus range with per-unit profit inside the guided band. Weak front-end grosses or further erosion in finance and insurance income per unit, already pressured by more electric and high-mileage vehicles, would challenge it. The roughly $20 million marketing campaign and the Orlando opening planned for the fourth quarter also mean expenses could rise before new stores contribute.
Fixed operations may be the most important number in the release. Same-store parts and service growth slowed to 2% last quarter from 8% a year earlier. Customer-pay work rose just 1%, and management called the slowdown an industry-wide wobble it could not fully explain. Service is the steadiest, highest-margin part of a dealership's earnings. A rebound toward the mid-single-digit pace of earlier quarters would ease concern that the slowdown is structural. Another quarter near 2% would make the earnings base look less durable. Power sports, where segment revenue jumped 53% after the Harley-Davidson acquisitions, is a smaller but useful sign of how well Sonic executes deals.
Sentiment has shifted from moderately bullish before the last report to slightly bearish now. The stock trades at $64.03, well below its 200-day moving average of $73.21 and closer to its post-earnings low of $58.46 than its high of $105.16. That leaves room for relief if margins hold, but little trust in management's outlook. Affordability is the backdrop, with new-vehicle prices around $60,000 and one in five monthly payments above $1,000. The central question is whether Sonic can grow Echo Park volume and keep new-vehicle margins at its raised floor while service revenue steadies. If it can, last quarter's confident tone survives. If not, the selloff may have been the earlier warning.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-07 | |
| Sep-09 | |
| Aug-27 | |
| Aug-14 | |
| Aug-06 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 | |
| Jul-09 | |
| Jul-07 | |
| May-27 | |
| May-21 | |
| May-07 |
