Quanta Services Must Show Its Record Backlog And Raised Outlook Can Outrun A Sliding Stock
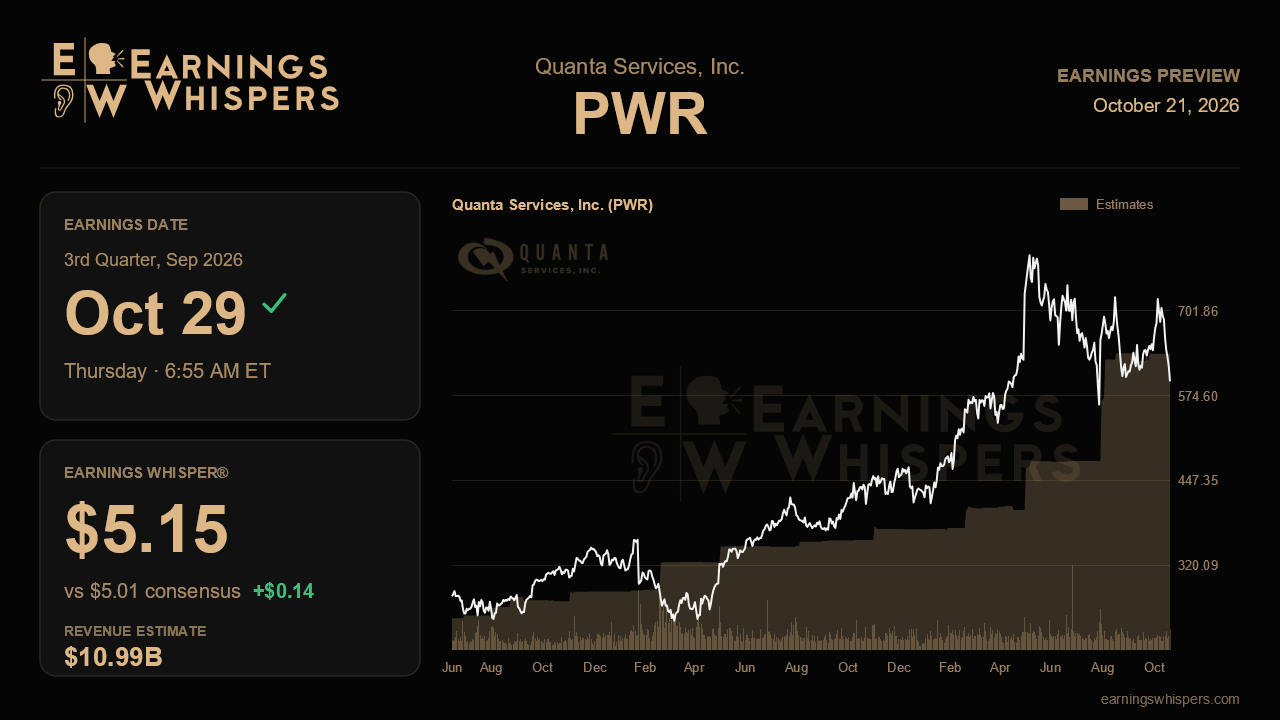
Quanta Services enters its third-quarter report with an odd disconnect. Last quarter, management delivered one of the most aggressive guidance raises in the company's recent history, posted a fourth straight record backlog and closed four acquisitions. Since then, the stock has fallen about 8% while the S&P 500 gained roughly 4.5%. The fundamental story got stronger and the share price got weaker, so this report has to show the market that the momentum is real and durable.
The bar is high in absolute terms. Analysts expect adjusted earnings of $5.01 a share on revenue of about $10.99 billion, a 44% jump from the $7.63 billion reported a year ago. Earnings would be up more than 60% from the $3.08 a share earned in the same quarter last year. The whisper number of $5.15 sits modestly above consensus. That gap is not dramatic, but it suggests the more engaged part of the market expects another clean beat rather than a simple in-line print. Management now guides to 2026 adjusted EPS of $16.45 to $16.95 on revenue of $39.3 billion to $39.7 billion, up sharply from the prior $13.55 to $14.25. The full-year consensus still on record, around $14.02, sits well below even the low end of that new range. That leaves room for estimates to keep rising if the quarter confirms the trajectory.
The most important thing to untangle is how much of the growth is organic. The four acquisitions that closed in July are expected to add roughly $1.2 billion to $1.4 billion of revenue and $120 million to $140 million of adjusted EBITDA this year, and the third quarter is their first full contribution. A big top-line number driven mostly by acquired revenue would be less persuasive than strength in the core electric business. Margins are the companion test. Management has reiterated that electric margins can reach 10% to 12%, and the underground business has been improving. Steady progress toward that range, along with free cash flow consistent with the newly raised 55% to 60% conversion framing, would validate the idea that Quanta is gaining operating leverage and not just volume.
Backlog is the other pillar. It climbed from $39.2 billion a year ago to $53.3 billion last quarter, and management said the large 765kV transmission programs and generation work were finally just starting, with more to stack in coming years. Another record would support that view. A flat or declining figure would not break the thesis, but it would invite questions about whether awards are getting lumpier or whether interconnection queues and permitting delays are slowing conversion. Commentary on the gas generation pipeline also matters, since management has repeatedly stressed selectivity and contract de-risking on combined-cycle work. Any sign of cost overruns or labor-driven delays there would hit a nerve, given that craft labor tightness remains the main governor on growth.
Sentiment has swung sharply, with bullish readings rising to about 73% from roughly 32.5% ahead of the last report. That optimism contrasts with the chart. At $596, the shares trade below their 200-day moving average near $619 and only about 1.5% above the post-earnings low of $587.23, well off the $724.80 high. The stock is pressing on support, not challenging resistance.
The main question is whether Quanta can show that last quarter's step-change raise was a floor, not a peak. A beat driven by organic electric growth, firmer margins and another backlog record would support a reaffirmed or higher outlook and challenge the stock's recent weakness. A quarter that leans on acquisitions, or guidance that merely holds steady after such a large raise, could leave the market treating last summer's optimism as fully priced.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 | |
| Sep-25 | |
| Sep-24 | |
| Sep-24 | |
| Sep-21 | |
| Sep-19 | |
| Sep-11 |
