Stagwell's Promised Second-Half Acceleration Faces Its First Real Test As Street Lags Guidance
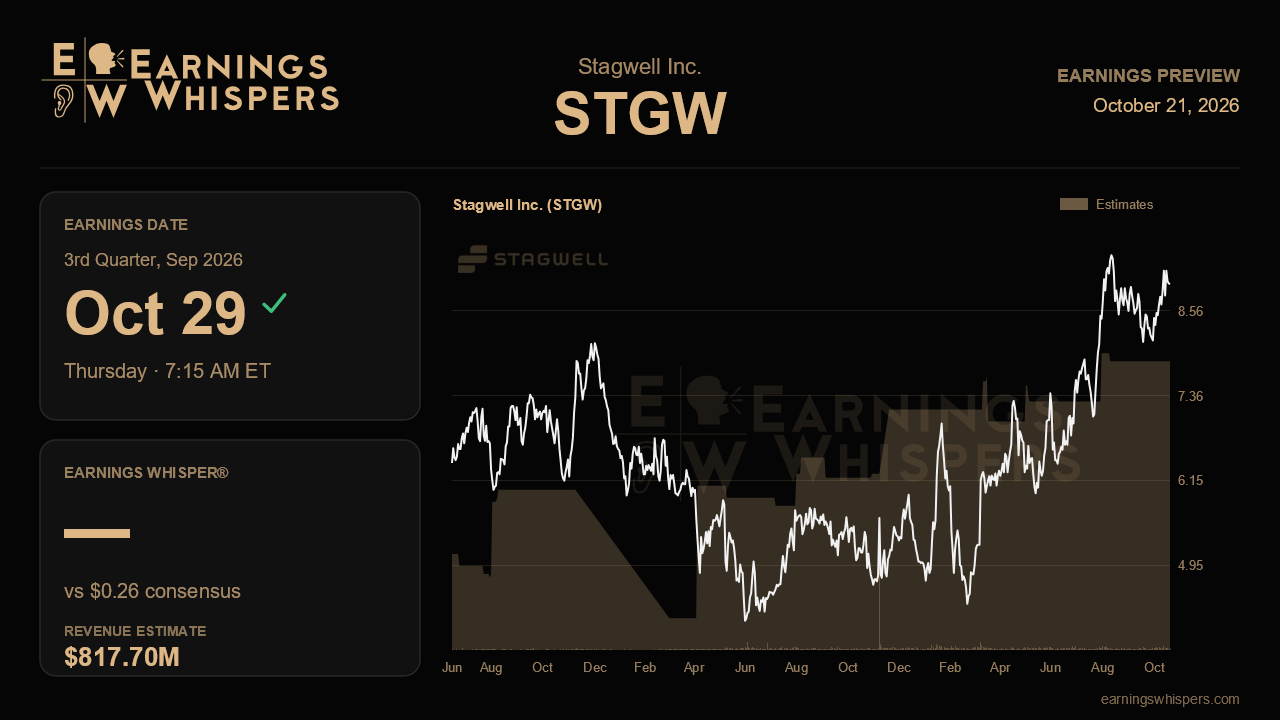
Stagwell walked out of its last report with the most confident message it has delivered in years: organic growth at a six-quarter high, a record haul of new business and a raised earnings outlook. Management also promised double-digit organic growth in the back half of the year. The third-quarter report, due before the open on October 29, is the first chance to see whether that promise is turning into revenue or whether it was a forecast built mostly on timing and hope.
Analysts expect earnings of $0.26 per share, up 30% from the year-ago quarter, on revenue of roughly $817.7 million, a 10.1% increase. That top-line figure matters because it lands right where management said the second half would go. It also implies a meaningful step up from the $786.3 million reported last quarter. Even so, the Street appears unconvinced by the full-year outlook. Stagwell lifted its 2026 adjusted EPS range to $1.03 to $1.17, yet consensus sits at $1.00, below the bottom of that range. On revenue, the $3.14 billion consensus matches the low end of the company's $3.14 billion to $3.26 billion target. Analysts, in other words, are not paying for the guidance. That gap gives Stagwell room to surprise if the acceleration is real, and it tells you how much skepticism remains.
The operational story rests on a few engines. Digital transformation was the standout last quarter, with organic growth of 18% and a 30% segment margin, the best since the merger. Communications reaccelerated to 12% organic, and management argued that political and public-relations work still has much of the midterm election cycle ahead of it. Strength in both segments, along with evidence that recent flagship wins such as IBM's creative account, Visit California, Hershey, Mondelez and Heineken are beginning to bill, would go a long way toward validating the double-digit organic guide. A slowdown in either leader would challenge the thesis, because the other two segments are not pulling their weight. Marketing Services grew just 0.5% organically and Media and Commerce about 1%. Any sign of life there would broaden the recovery. Continued stagnation would leave the story dependent on a narrow set of businesses and a single election season.
Margins and the quality of the EPS raise deserve equal scrutiny. Adjusted EBITDA margin expanded to 17.2% last quarter as the labor ratio fell, and annualized cost savings actioned climbed to about $70 million. Yet the company held its EBITDA and net revenue guidance steady, which means the EPS increase was driven largely by buybacks that have reduced the share count by 6.4% from a year earlier. Upgrading EBITDA guidance would show that operations, not financial engineering, are carrying the improvement. Progress on net leverage, which stood at 3.04 times against a mid-2s year-end target, will show whether repurchases and debt reduction can coexist. Updates on enterprise technology bookings, already $16 million against a $25 million goal, and on the agentic Media Machine products will help gauge whether the newer bets are gaining traction.
Sentiment has warmed but remains cautious, with the bearish reading easing to about 13.8% from 24.7% ahead of the prior report. The stock has climbed 7.3% since then, modestly ahead of the S&P 500. At $8.94, it trades well above its 200-day average near $7.01 and within a higher range than last quarter. It is still about 7% below its post-earnings high of $9.64, so this is constructive positioning rather than a breakout.
The central question is simple. If organic growth moves into double digits and the recent wins show up in the numbers, consensus below the guidance range looks too conservative. If the acceleration stalls, last quarter's inflection will look more like a peak than a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-21 | |
| Oct-20 | |
| Oct-18 |
Business People: Former Colle McVoy president Obele Brown-West to lead Folklore
STGW
Pioneer Press, St. Paul, Minn.
|
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-02 |
