Stagwell Narrowly Misses On Normalized EPS, But Accelerating Tech Growth And A Guidance Raise Recast The Story
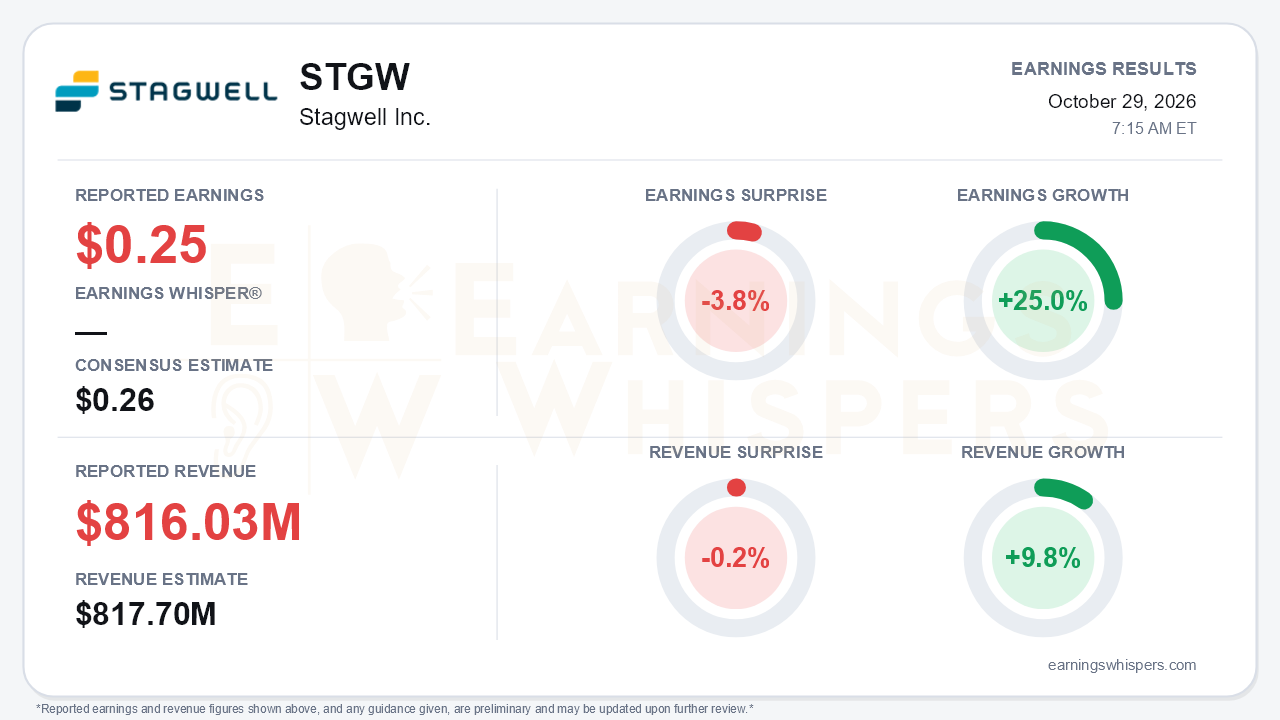
Stagwell's third quarter produced a small headline miss and a much stronger operating story. On an Earnings Whispers normalized basis, the company earned $0.25 per share, a penny below the $0.26 consensus, a 3.8% shortfall. Revenue of $816.03 million missed the $817.7 million estimate by 0.2%. Year over year, though, earnings grew 25.0% and revenue rose 9.8%. Stagwell's own figures are higher: it reported adjusted EPS of $0.34, up 42%, and GAAP EPS of $0.07, down from $0.09. That three-way gap matters. The miss against the normalized estimate was marginal. The real development is that growth is accelerating, led by the technology and transformation businesses management wants investors to value the company on.
The quality of the quarter deserves scrutiny. Organic net revenue rose 7.4% to $664 million, up from roughly 5% in the second quarter and about 3.6% in the first. Adjusted EBITDA climbed 25% to $145 million, and the margin on net revenue widened about 290 basis points to 21.8%. GAAP results moved the other way. Operating income fell to $48 million from $61 million because office and general expenses jumped 24%. Stock-based compensation more than doubled to $28.9 million. Deferred acquisition consideration also swung to a $7.7 million charge from a $13.3 million benefit a year ago. Cash flow was the strongest rebuttal to skeptics: year-to-date operating cash flow reached $152 million versus $31 million last year. Capitalized software spending also rose to $76 million from $45 million, a reminder that the software pivot requires real investment.
Beneath the consolidated numbers, Stagwell is splitting into two businesses moving in opposite directions.
- **Growth engines:**
- Digital Transformation grew 23% organically, up from 18% in the second quarter and 9% in the first, with margins above 32%.
- The Marketing Cloud more than doubled organically to $56 million and swung from a small EBITDA loss to $24.7 million of segment EBITDA, a margin above 44%.
- Communications rose 20% organically, helped by midterm political spending.
- **Laggards:**
- Marketing Services fell 7.5% organically after modest growth earlier in the year. Management cited tough comparisons, timing of wins, and industry-wide creative turmoil.
- Media & Commerce slipped 2.1%.
- The Middle East declined 35%, or $9 million, which management said cost roughly two points of organic growth.
The labor ratio improved to 57.6% from 60.9% in the second quarter, and actioned cost savings rose to $78 million. Together these suggest the margin gains reflect structural change as well as revenue mix.
The call added a meaningful list of catalysts:
- **Federal work:** Stagwell won its first major federal contract, serving as prime subcontractor to Kaki for U.S. Central Command on a $1.5 billion, five-year program with roughly 10% expected fee capture. A second federal assignment followed weeks later.
- **Partnerships and clients:** An expanded Palantir partnership and a ServiceNow multi-agency win, which management called its largest ever.
- **M&A:** Deal-making has resumed with the Freestar acquisition and a larger RealClearPolitics stake.
- **Bookings:** Enterprise technology bookings reached $59 million against an initial $25 million goal, and management doubled its 2027 target to $150 million.
Bears still have legitimate ammunition. Political revenue will fade after the midterms before the presidential cycle ramps in the second half of 2027. Building a software sales force could pressure margins. Management's valuation framing on the call was promotional rather than guidance.
Guidance moved in the right direction, but it was not a blowout. Full-year adjusted EBITDA guidance rose to $490-$540 million from $475-$525 million. Adjusted EPS guidance rose to $1.07-$1.21, the second consecutive increase. The 8%-12% net revenue growth range and the 50%-60% free cash flow conversion target were only reaffirmed. The guidance raise appears in line with estimates rather than ahead of them, so the improved outlook may largely be recognized already. Net leverage fell to 2.73x from 3.04x last quarter, although long-term debt rose to $1.41 billion. Buybacks slowed sharply to about 260,000 shares from 5.9 million in the second quarter.
Investor sentiment improved into the report but remains negative, rising from -0.25 to -0.13. Skepticism has eased without disappearing. The stock tells a similar story. Shares were up about 6% since the open after the July report and sat nearly 24% above the 200-day moving average. They had pulled back about 8% from the 52-week high of $9.64 set on October 13 during this inter-earnings period. Most Earnings Whispers trend readings are positive, with sequential growth and momentum improving, while the price trend is neutral. The market has already rewarded part of the turnaround, which raises the bar for the tech narrative to keep delivering.
The bottom line is that Stagwell's slight miss on normalized EPS matters far less than the mix shift underneath it. Digital Transformation and The Marketing Cloud are accelerating, margins are widening, cash generation has improved dramatically, and new federal and enterprise wins have strengthened the pipeline. The GAAP decline, Marketing Services erosion, the coming political air pocket, and an unchanged revenue range keep the setup from being clean. Investors entered with improving but still cautious sentiment, and they will need proof that software bookings convert into durable revenue before fully buying the transformation story.
Read our earnings preview for Stagwell Inc.: https://www.earningswhispers.com/article/STGW/21131
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 9 hours | |
| 11 hours | |
| 11 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-20 | |
| Oct-18 |
Business People: Former Colle McVoy president Obele Brown-West to lead Folklore
STGW
Pioneer Press, St. Paul, Minn.
|
| Oct-15 | |
| Oct-14 | |
| Oct-14 |
