TriNet's Raised Outlook Meets Its First Test As Insurance Costs Turn Seasonal
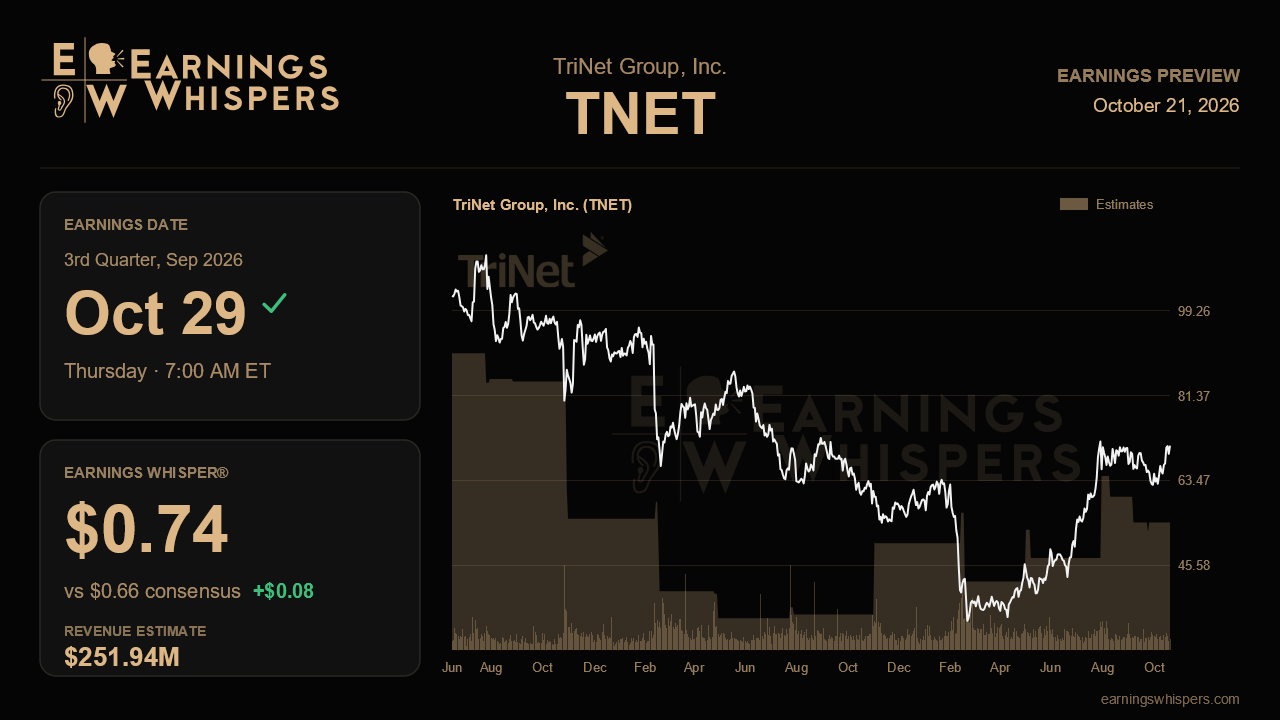
TriNet spent the first half of 2026 convincing investors that its pricing repair was real, and the market listened: the stock roughly doubled off its lows during the prior quarter. Now comes the harder part. The third quarter is when management said insurance costs would worsen seasonally and growth spending would ramp, so this report will show whether the earnings recovery can hold up once the easy tailwinds fade.
Wall Street expects non-GAAP earnings of $0.66 a share, down from $0.83 a year ago and well below the $1.34 posted last quarter. That drop is largely by design. Management guided to a tougher second half, and the consensus seems to reflect it. The Earnings Whisper of $0.74 sits meaningfully above consensus, though, suggesting the people closest to the stock expect TriNet to clear the published bar comfortably. The $251.9 million revenue consensus implies an almost 80% year-over-year decline, which does not line up with the roughly $1.2 billion in quarterly total revenue TriNet has been reporting. It most likely reflects a different revenue basis. A better yardstick is management's unchanged $4.75 billion to $4.9 billion full-year range, which it said is trending at or slightly below the midpoint because of softer insurance service revenue.
The guidance story is where the setup gets interesting. TriNet lifted its 2026 adjusted EPS outlook to $4.50 to $5.10 from $3.70 to $4.70, raised its EBITDA margin target to 8.5% to 9.0%, and tightened its insurance cost ratio range to 88.5% to 89.5%. Yet the full-year consensus of $4.54 sits near the bottom of that range. Analysts are effectively discounting management's own forecast, likely because about half of the first-half insurance favorability came from one-time items such as prior-year claims development and a recovery of administrative costs. That caution creates room for upside. If the third-quarter insurance cost ratio comes in near the year-ago level rather than deteriorating further, the low-end positioning starts to look too conservative.
The operating questions go beyond the cost line. Retention was the standout last quarter, with overall attrition down 36% and health-fee-related attrition down 58%. Holding those gains now that the January repricing catch-up is behind the company would confirm that customers have absorbed the higher prices. The weak spot is volume. Worksite employees fell 12%, new sales were flat, and management conceded that hiring within existing clients had not yet accelerated. Signs of stabilization in employee counts, early productivity from the first Ascend sales class, and continued strength in the broker channel, where requests for proposals jumped 54%, would support the argument that growth is coming. Updates on Cocoon client migrations and the AI assistant, which now handles half of chat sessions, matter mainly as evidence that service costs can keep falling while investment rises.
Sentiment has turned modestly bullish from bearish heading into the last report, but the stock has slightly lagged the S&P 500 since then. Shares sit far above the 200-day moving average and about 3% below their post-earnings high of $73.08, so a convincing report could push the stock toward a breakout. A stumble, however, would test a stock that has already priced in a lot of recovery.
Ultimately, this quarter hinges on whether insurance costs behave as management predicted, or better, while spending rises. If they do, and volumes show even tentative signs of bottoming, the Street's low-end positioning will look stale. If costs spike or employee counts keep sliding, the first-half margin rebound may start to look more like a one-off than a lasting turnaround.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-15 | |
| Oct-13 | |
| Sep-28 | |
| Sep-28 | |
| Sep-22 | |
| Sep-14 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 | |
| Jul-16 | |
| Jul-16 | |
| Jul-08 |
