TriMas Needs Resin Recovery And A Norris Fix To Back Its Raised Earnings Floor
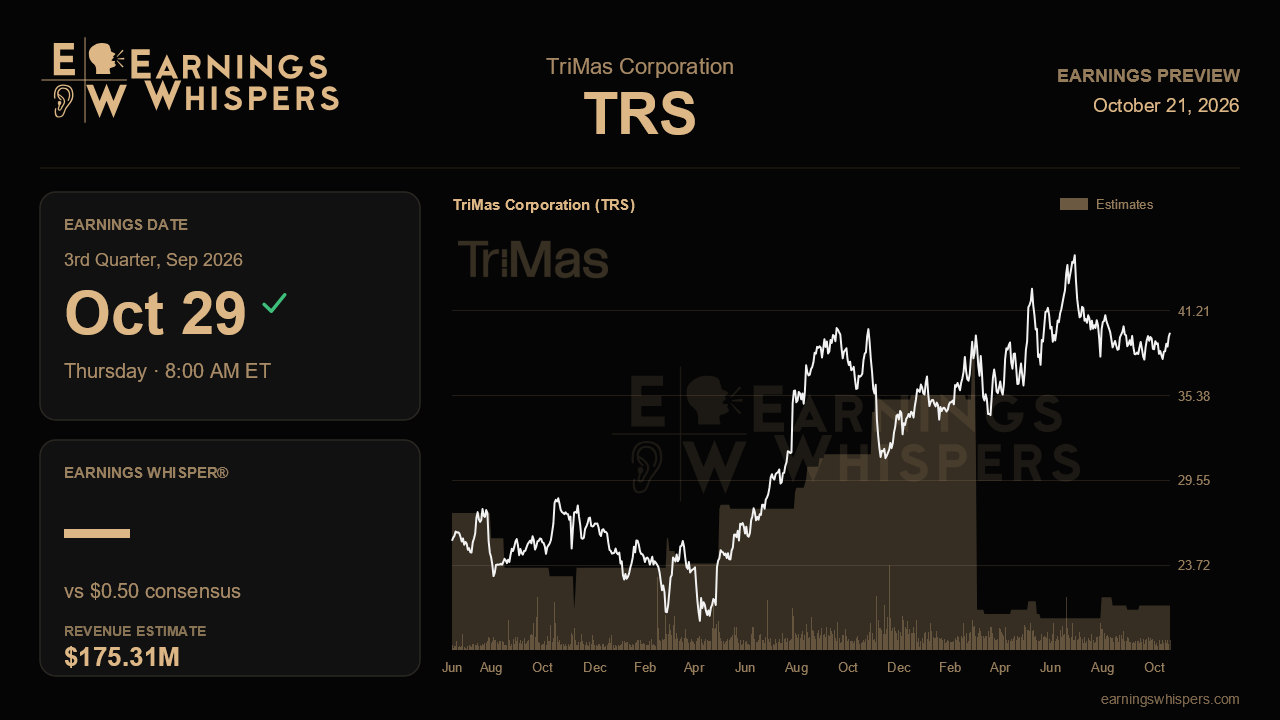
TriMas heads into its third-quarter report with a promise to keep. Three months ago, management lifted the bottom of its full-year earnings range on the strength of cost cuts and interest income, even as organic growth stalled and its Specialty Products margins slipped. The quarter ending in September is where several of those deferred fixes are supposed to show up, most notably the recovery of resin costs that went unrecouped in the spring. This report should reveal whether the post-aerospace TriMas is a self-help story with traction or one still waiting on the second half.
Wall Street expects adjusted earnings of $0.50 a share on revenue of about $175.3 million. On paper that looks ugly: an 18% drop in earnings and a roughly 35% slide in revenue from the year-ago $0.61 and $269.3 million. The comparison is distorted, though, because last year's figures still included the aerospace business TriMas has since sold. The more useful yardstick is the prior quarter, when the company earned $0.52 on $174.6 million. Against that baseline, the Street is penciling in essentially flat sales and a slight sequential dip in profit, a cautious bar given that cost savings are meant to build through the year.
Management now guides to full-year adjusted earnings of $1.60 to $1.70 a share, narrowed from $1.50 to $1.70. Consensus sits at $1.67, in the upper half of that range. That leaves limited cushion. Analysts are effectively assuming the second-half levers work as advertised, so a modest third-quarter result paired with a reaffirmed range would probably be read as neutral, while any hint that the company is drifting toward the midpoint could sting.
Packaging, which generated roughly $143 million of second-quarter sales, is the business that matters most. Sales there were flat as beauty and personal care and food and beverage softened, and about 100 basis points of margin were lost to resin costs the company had not yet passed through. Management pushed that recovery into the third and fourth quarters. Visible margin improvement in packaging, alongside any return to organic growth after the flat second quarter, would validate the narrative. Continued softness in consumer end markets, or another delay on pricing, would challenge it. Progress on the One TriMas brand consolidation and the new sales and operations leadership will be harder to measure but worth listening for.
Specialty Products presents the opposite problem: demand is fine, execution is not. Norris Cylinder's orders were strong enough, helped by its Made in USA positioning, that management raised segment sales growth guidance to 6% to 9%. Yet Norris margins fell to 2.2% on temporary labor, overtime and inefficiencies, forcing a cut in the segment margin outlook to 6% to 8%. The key test is whether throughput is stabilizing. A further margin cut would suggest the ramp is harder than management conceded. Investors should also look for free cash flow to swing back after a second-quarter outflow of about $12.9 million, for updates on the additional Atkins-sized cost actions flagged for the back half, and for how the $1.2 billion cash pile is deployed between buybacks and packaging or life science acquisitions.
Sentiment has cooled, with readings slipping to 19.3% bearish from 13.3% bearish ahead of the last report, even as the stock has gained 6.4% since then, about two points better than the S&P 500. At $39.70, shares sit above their 200-day average of $38.49 but well below the post-earnings high of $42.08, inside a narrower range than the prior quarter. The verdict likely rests on whether resin recovery and Norris efficiency begin converting into margins. If they do, the raised floor looks conservative; if they slip again, the earnings story starts leaning too heavily on interest income and buybacks.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-05 | |
| Sep-14 | |
| Aug-04 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jun-30 | |
| May-05 | |
| Apr-30 | |
| Apr-30 | |
| Apr-30 | |
| Apr-23 |
