West Pharmaceutical Faces A Planned Trough Quarter As New CEO Inherits Raised Targets
West Pharmaceutical Services heads into its third-quarter report with an unusual combination: a business that has raised its full-year outlook twice in a row, and a quarter that management itself has framed as a step down. The company now expects 10% to 11% organic growth for 2026, up from an initial 5% to 7%, and adjusted EPS of $8.85 to $9.05, up from $7.85 to $8.20. Yet the third quarter absorbs the start of a contract manufacturing roll-off, the loss of the divested SmartDose 3.5mL business and lingering effects of a May cyber incident. The question is whether that softer headline masks a core franchise that is still accelerating.
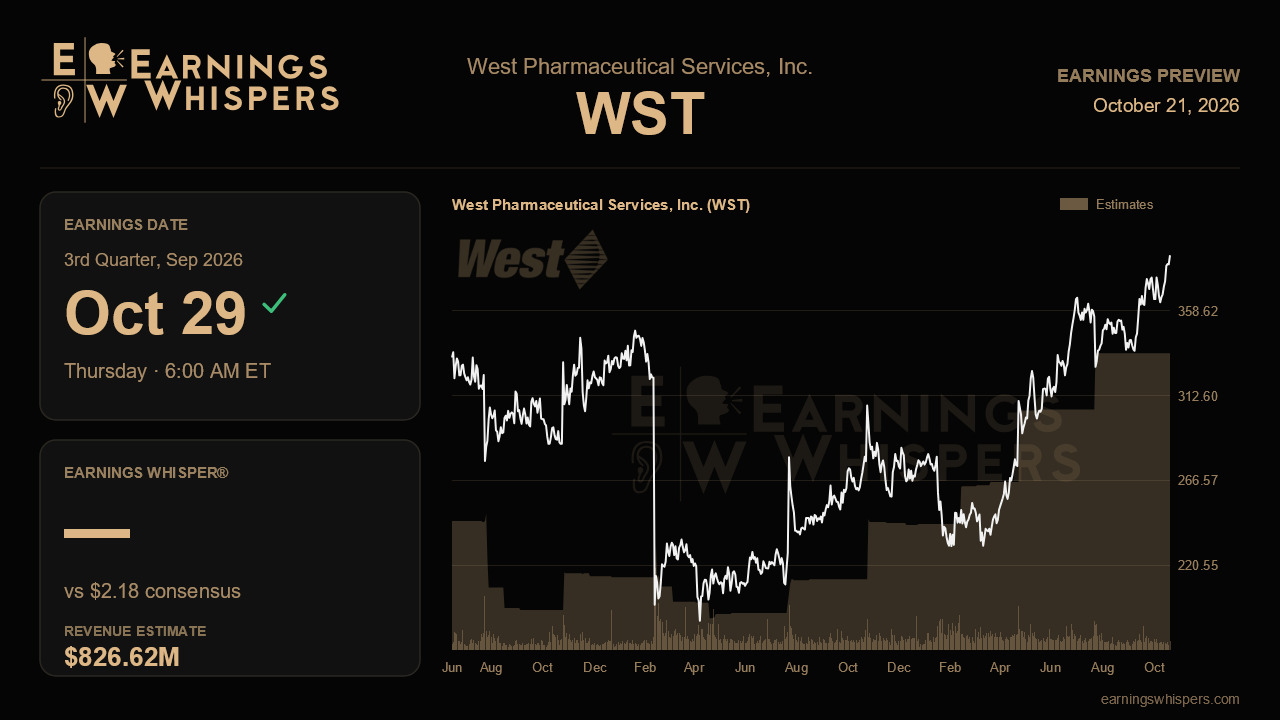
Consensus calls for EPS of $2.18 on revenue of $826.6 million. That compares with $2.37 and $872.3 million last quarter, and it implies year-over-year growth of about 11% in earnings but under 3% in revenue. The Street sits essentially at the middle of management's guidance of $2.14 to $2.24 per share and $820 million to $835 million in sales, a hair below the EPS midpoint. That positioning matters. West beat its second-quarter EPS guide midpoint by $0.28, and analysts have not stretched toward the top of the range, leaving room for another clean beat if the patterns of the first half hold.
The heart of the story is high-value product components, where West sells premium stoppers and syringe parts used with biologics and GLP-1 drugs. These grew 18.4% organically in the second quarter, with the biologics market group up 29%. Management lifted its full-year view for non-GLP-1 components to high-teens growth from low double digits, a sign that demand is broadening beyond weight-loss drugs. Supporting evidence would include continued strength in NovaPure and FluroTec lines, further growth in the roughly 800 Annex 1 upgrade projects in hand, and Asia-Pacific momentum tied to generic and biosimilar GLP-1 launches. Pricing is another tell: it contributed 4 points in the second quarter, up from 3.5 points, and holding that level would show West can offset higher commodity and oil-linked costs.
Margins are the second test. Adjusted operating margin reached 22.6% last quarter, up 230 basis points, and management now targets more than 200 basis points of full-year expansion, double its earlier aim. With the low-margin SmartDose line gone, the mix should help further in the back half. Confirmation would come from gross margin holding near the high-30s despite lower contract manufacturing volume. The risks sit in WestVantage, which grew less than 1% organically last quarter after the cyber disruption and now faces an estimated $40 million second-half headwind from the CGM contract exit. Management called the third quarter the trough for that unit, so investors should look for evidence that deferred revenue is being recaptured and that operating cash flow, which dipped to $124 million on receivables timing, is normalizing.
The report is also the first under new chief executive Michele Lagarde, who took over at the end of August. Any shift in tone toward the guidance, or toward the Annex 1 opportunity possibly expanding into the U.S., will be closely parsed. Sentiment has improved modestly to 33.4% bullish from 30.6% before the last report. The stock gained just 1% after that report while the S&P 500 rose 4%, but it has since climbed to $388.78, within a whisker of its post-earnings high of $389.75 and well above its 200-day average near $308. That puts shares at a potential breakout point, where execution will likely decide the next leg.
Ultimately, the narrative stays intact if West shows the third-quarter dip is purely mechanical, with high-value components still growing in the high teens and margins expanding despite WestVantage weakness. A reaffirmed or nudged-higher full-year outlook would signal that management's prudent second-half framing was conservative. A miss in components growth or a margin stall, by contrast, would suggest the first half marked the peak rather than a new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-19 | |
| Oct-08 | |
| Oct-05 | |
| Aug-26 | |
| Aug-26 | |
| Aug-25 | |
| Aug-07 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-21 | |
| Jul-17 | |
| Jul-17 |
