Asure Heads Into Q3 Needing Margin Proof As Backlog Shrinks And Shares Sag
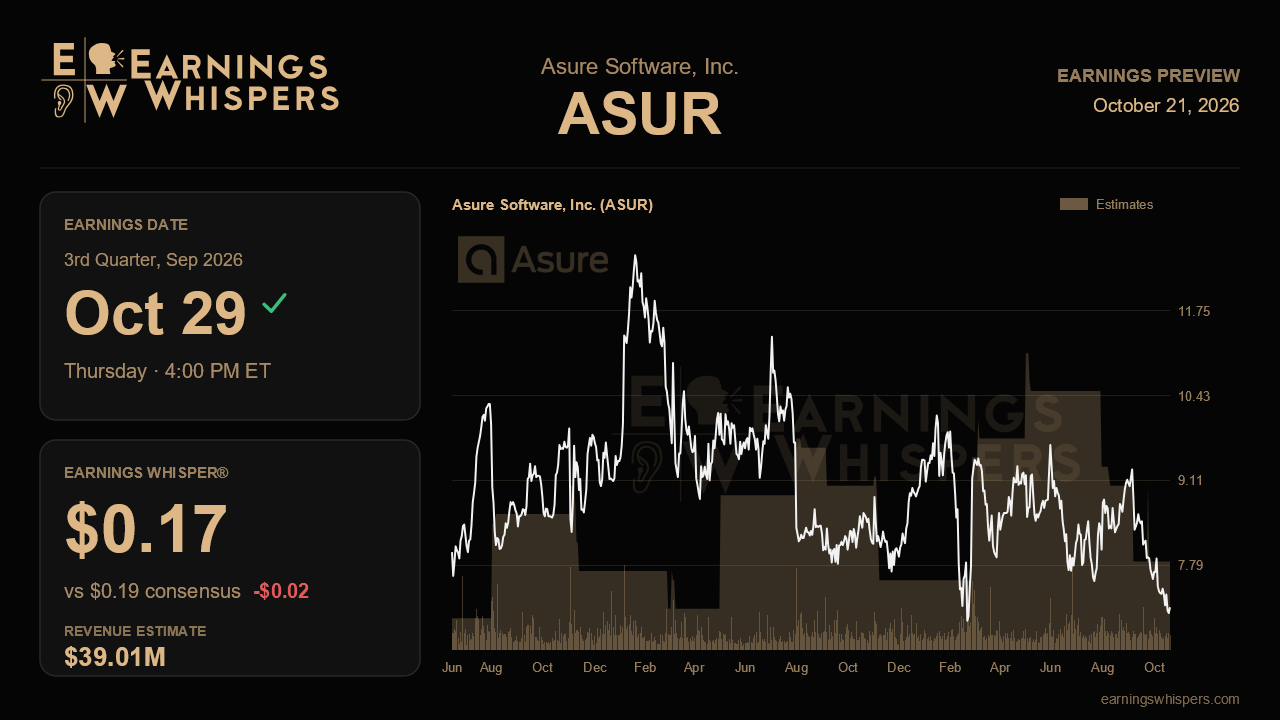
Asure Software enters its third-quarter report with an odd disconnect. Management spent last quarter's call describing a business gaining momentum on nearly every operating measure, nudged up the floor of its full-year profitability target, and celebrated a major enterprise tax go-live. Yet the stock has fallen 7.2% since then, lagging the S&P 500 by more than 10 percentage points and drifting to $7.13, just above its post-earnings low of $7.02 and well beneath its 200-day moving average of $8.54. The report due after the close on October 29 needs to show that the improving story is translating into numbers the market can trust.
The Street is looking for non-GAAP earnings of $0.19 a share on revenue of $39.0 million, which would be growth of about 7.6% from the year-ago quarter. That is respectable but hardly a sprint, and it lands squarely at the midpoint of management's $38 million to $40 million quarterly guidance. Notably, the revenue consensus has slipped from roughly $39.6 million when the guide was issued, so analysts have quietly tempered their hopes. The earnings whisper of $0.17 sits a couple of cents below consensus, a modest gap that suggests some skepticism about how much profit flows through this quarter rather than a call for a blowout.
Profitability is the cleanest test of last quarter's narrative. Second-quarter adjusted EBITDA margin climbed to 21% from 17% a year earlier, and management raised the low end of its full-year margin target to 24% to 25%. Because the first half ran below that range, hitting the target requires a meaningful step-up in the back half. A third-quarter margin that moves clearly toward the mid-20s would validate the raise; one stuck near second-quarter levels would put pressure on the fourth quarter and invite doubts about whether the floor was lifted too eagerly.
On growth, the key distinction is between recurring and non-recurring revenue. Management warned that second-half non-recurring revenue, mostly large tax professional services and hardware, should come in around $5 million to $6 million versus about $10 million last year, which mechanically mutes reported growth. That makes organic recurring growth the number that matters. Organic growth slowed to 5% in the second quarter from 7% in the first, attributed to seasonality, and both sit well short of the double-digit organic ambition management has floated. Evidence of reacceleration, aided by the 2 million Venture Employer Services employees now live on the Enterprise Payroll Tax platform, would go a long way.
Backlog deserves close scrutiny too. It has fallen from roughly $100 million at year-end to about $85.6 million and then about $80 million, even as the share expected to convert within 12 months rose to 41%. Faster conversion is good news for near-term revenue, but continued shrinkage would raise the question of whether new enterprise wins are replenishing the pipeline. Management called that enterprise tax pipeline exceptionally strong and hinted at second-half announcements, so concrete signings would be the most persuasive rebuttal. Payroll bookings growth of 14%, a shifting mix toward selling into the existing base, and AssureWorks clients generating up to five times the revenue of payroll-only customers are other threads worth following, along with any progress on the few reseller acquisitions management expects this half.
Sentiment has warmed, with the reading improving to 19.2% bearish from 32.5% bearish heading into last quarter, though it remains net negative. Combined with a stock pinned near its lows, that sets a bar that is not especially high. The central issue is whether Asure can show margin expansion and recurring growth strong enough to look past the non-recurring drag. If it can, the gap between operating progress and share price becomes hard to ignore; if not, the market's caution will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Oct-13 | |
| Oct-07 | |
| Sep-30 | |
| Sep-29 | |
| Sep-15 | |
| Sep-09 | |
| Sep-01 | |
| Aug-31 | |
| Aug-27 | |
| Aug-26 | |
| Aug-21 | |
| Aug-21 |
