Amazon's AWS Surge Faces A Margin Test As Prime Day Timing Muddies Third-Quarter Sales
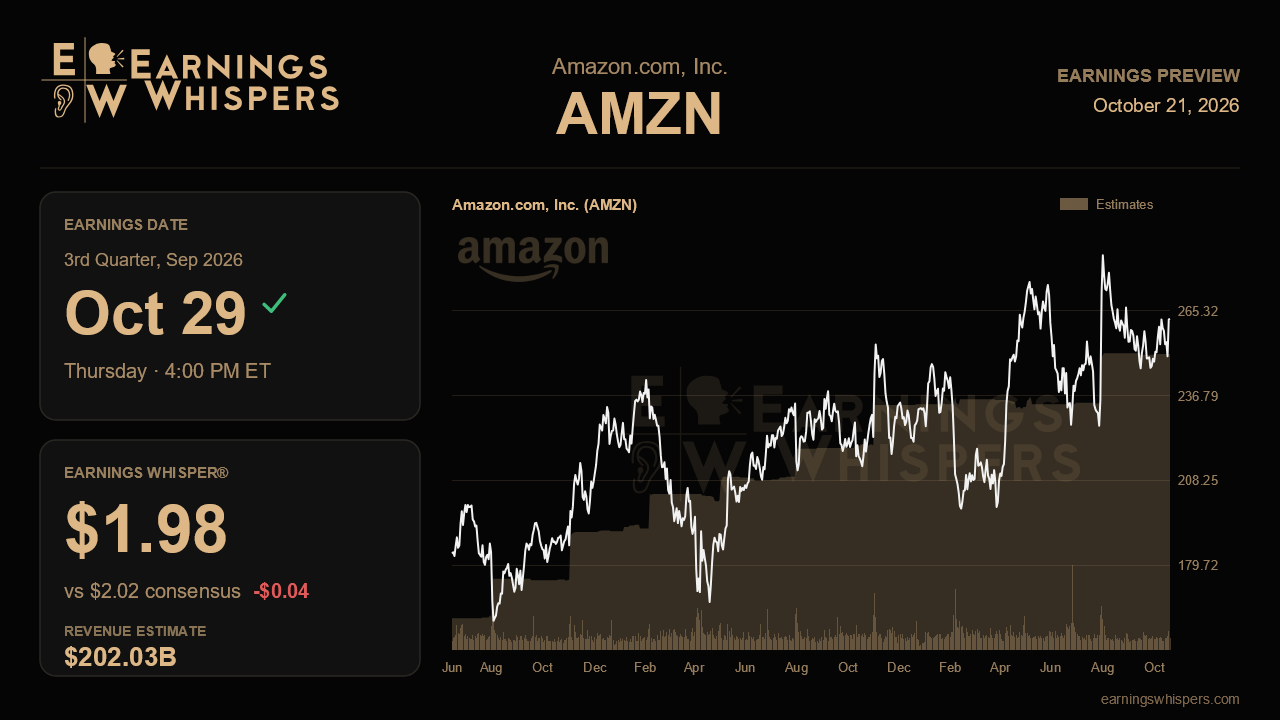
Amazon heads into its third-quarter report with an awkward split screen. Its cloud business just posted its fastest growth in 18 quarters along with margins that skeptics said AI would never allow, yet the stock has slipped since that report while the broader market climbed. The October 29 release, due after the close, needs to show that the AWS inflection was a trend rather than a one-quarter spike, and that heavy spending and rising costs are not quietly eating the gains.
The Street expects earnings of $2.02 per share on revenue of about $202.03 billion. Revenue growth of 12.1% looks like a sharp slowdown from the roughly 20% pace of the second quarter, and earnings growth of just 3.6% from last year's $1.95 looks almost flat. Both figures are distorted. Management guided to sales of $197 billion to $202 billion and explained that Prime Day shifted into the second quarter, shaving about 400 basis points off reported growth, with currency costing roughly another 80. Analysts have trimmed their numbers since that outlook, but consensus still sits at the very top of the range, a bit above it in fact. That leaves little room for an ordinary result to read as a beat on sales. The earnings whisper of $1.98 sits slightly below consensus, a sign that the informal bar for profit is a touch lower than the published one.
AWS is the main event. Growth stepped up from about 20% a year ago to 24%, then 28%, then 36.7% last quarter, lifting the annualized run rate to $169 billion. Backlog has swelled to roughly two and a half times its level of a year ago, custom silicon has passed a $25 billion run rate, and management said capacity into 2027 is largely spoken for. With that much contracted demand, a sharp deceleration would be hard to explain. Growth holding in the mid-30s would support the story, while a drop back toward the 20s would raise doubts about whether supply, not demand, is setting the pace. The margin line matters nearly as much. AWS margins reached about 39%, though roughly 130 basis points came from a one-time energy derivative gain. Holding the high 30s without that help would back management's claim that AI workloads are ramping profitably.
The company-wide profit picture is less tidy. Second-quarter operating income benefited from about $1.2 billion of one-time items, including a tariff refund. Management also flagged sharply higher prices for memory, solid-state drives and hard drives, along with rising fuel and line-haul costs from tight driver capacity. North America margins of about 7.9% in each of the past two quarters set a clear benchmark, and any meaningful slip would point to cost inflation outrunning efficiency gains. Cash capital spending climbed to $53.1 billion last quarter, prompting debt issuance, so the funding outlook will get close scrutiny. Updates on third-party Tranium rack sales, the in-house frontier model, grocery delivery expansion and the Amazon Leo satellite launch offer upside, but they are unlikely to outweigh the core numbers.
Sentiment has improved, with the bearish reading easing to 22% from 37.5% a quarter ago, yet the shares are down 0.9% since the last report and trail the S&P 500 by more than four points. At $262.63 the stock sits above its 200-day moving average of about $243, near the middle of its post-earnings range and well short of the $287.20 high. The market seems to accept the AWS story but has not decided whether the capital needed to sustain it will pay off.
That is the question this report must answer. If AWS keeps growing in the mid-30s with margins near 39% and no derivative gain, and the retail business absorbs higher component and freight costs without margin erosion, the spending case gets stronger. If cloud growth cools or cost pressure shows up in segment margins, the slowing headline numbers may start to look like more than a Prime Day calendar quirk.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 |
Anthropic Has Over $600 Billion in Compute Contracts And It's Not Enough
AMZN
Benzinga Private Markets
|
| Oct-21 |
Amazon's Nvidia Chips Are Sitting in Warehouses Without Power as AI Spending Soars, Business Insider Reports
AMZN
Benzinga Prediction Markets
|
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 |
Meta Earnings Prediction Market Preview: What Will Mark Zuckerberg Say?
AMZN
Benzinga Prediction Markets
|
| Oct-21 |
