Axos Must Prove Credit Hiccups Are Isolated As Margin Tailwinds Fade
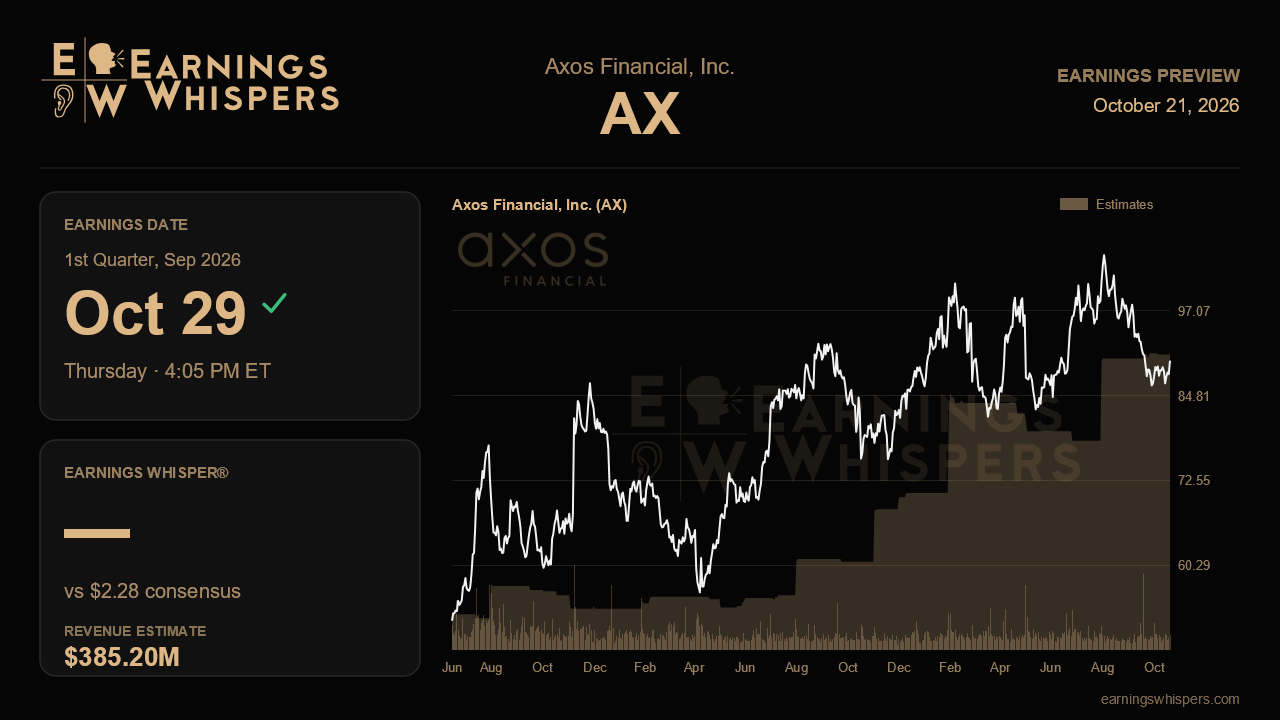
Axos Financial heads into its fiscal first-quarter report with a growth story that still looks intact on paper and a stock that has been treated as if it isn't. Since the last report, shares have fallen 12.3% while the S&P 500 gained 3.3%. That gap suggests the market cares less about the bank's double-digit loan growth than about two worries that surfaced last quarter: a net interest margin coming off its highs and a cluster of commercial credit problems. The October 29 release, due after the close, is a test of whether those issues were growing pains or the start of a less profitable chapter.
The Street expects earnings of $2.28 per share, up about 10% from $2.07 a year ago but below the $2.53 posted last quarter. Part of that sequential step down is reasonable. The prior period was helped by a one-time legal settlement of roughly $22 million, so a cleaner quarter would naturally print lower. Consensus revenue of $385.2 million implies a 22.7% year-over-year decline. That figure is hard to square with a balance sheet still growing at double-digit rates, so earnings per share and net interest income are the better gauges of how the core franchise is performing.
Margin is the first place to look. Net interest margin slid from 4.94% in December to 4.57% by March as rate cuts pushed down loan yields and accretion from previously purchased FDIC loans nearly ran out, with only about 5 basis points of benefit left. Management guided to a roughly flat organic margin, less about 5 basis points of drag from the premium paid on acquired deposits, and warned analysts not to model much upside from the deposit deals. A margin holding in the mid-4% range would support that guidance. A further meaningful drop would suggest pricing pressure on loans or deposits that management has not yet acknowledged.
Credit is the bigger swing factor and likely the main reason for the stock's weakness. Net charge-offs jumped to 31 basis points from just 4 basis points two quarters earlier, driven by a $14 million commercial charge-off. A syndicated shared national credit also went delinquent and added $33 million to nonperforming assets, and Axos has since stepped in as agent. Provisions climbed to $41 million. The key question is whether that loan resolves without fresh losses and whether nonperforming assets stabilize. Management's 1.3% to 1.4% reserve target offers a benchmark. A provision that falls back toward earlier levels would ease concerns, while another commercial and industrial surprise would make the problem look systemic rather than isolated.
On the growth side, management has reaffirmed loan growth in the low-to-mid teens, with organic net additions of roughly $600 million to $800 million a quarter and a pipeline that stood near $2.6 billion in April. Results inside that band would confirm demand remains broad across capital call, fund finance, lender finance and equipment lending. Investors should also look for early evidence from the Genius Bank deposit acquisition, which has regulatory approval and about 60,000 clients to onboard, along with any update on timing for the Capital One IRA and CD purchase. Management has flagged that acquired deposits may arrive before loans can absorb them, temporarily inflating the balance sheet and diluting returns. Continued fee momentum from Verdant and custody assets, which reached $44 billion, would help cushion that effect.
Sentiment has cooled noticeably, with bullish readings falling to 8.4% from 34.4% ahead of the prior report. The stock sits at $89.86, below its 200-day moving average of $92.31 and closer to the bottom of its post-earnings range of $84.03 to $105.74 than the top. That leaves a modest bar. In the end, this report will be judged on credit. If losses recede and the margin settles where management said it would, the double-digit compounding story stays intact. Another commercial loan surprise would give the skeptics more ammunition.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-02 | |
| Sep-29 | |
| Sep-02 | |
| Aug-25 | |
| Aug-13 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-09 | |
| Jul-08 | |
| Jun-23 | |
| Jun-03 | |
| May-04 |
