QCR Holdings Posts Record EPS But Misses The Whisper As Guidance Holds Steady And The Rate Backdrop Shifts
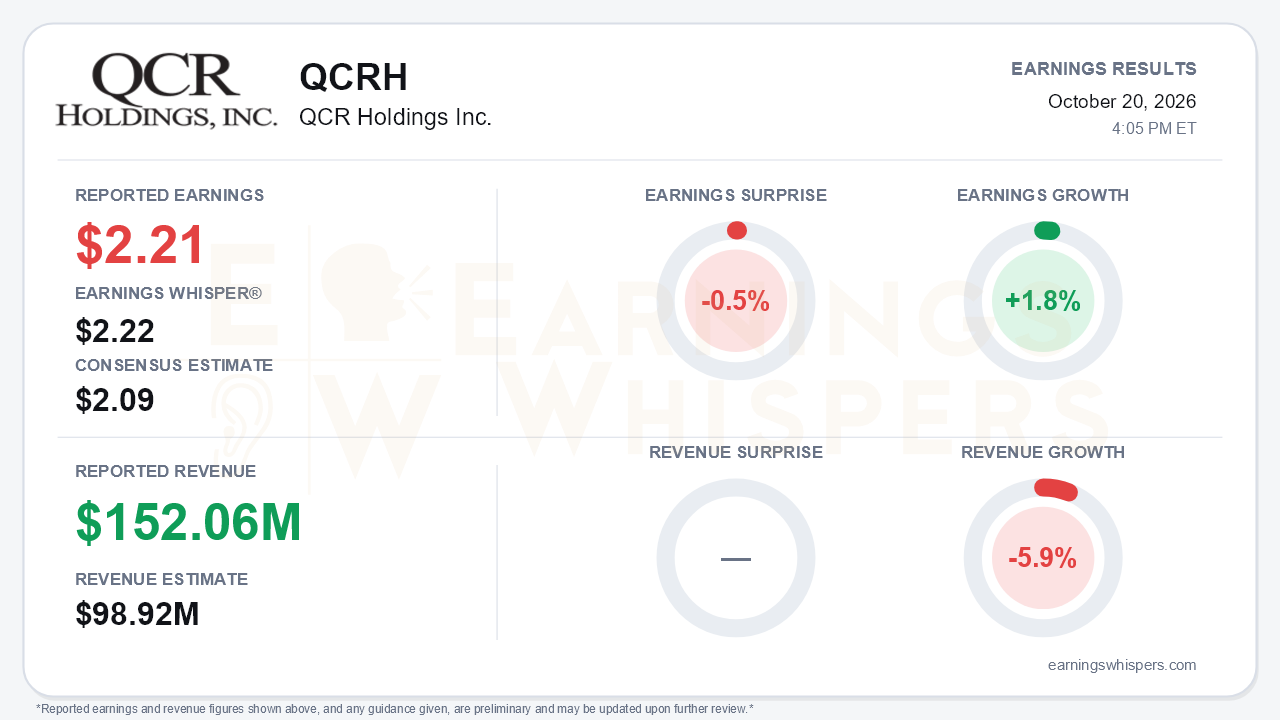
QCR Holdings (NASDAQ: QCRH) delivered record diluted EPS of $2.21 for the September quarter. That cleared the $2.09 consensus comfortably but fell a penny short of the $2.22 Earnings Whisper number, a 0.5% miss against the expectation that mattered most to engaged investors. Revenue of $152.06 million beat the $98.92 million consensus by 53.7% but fell 5.9% from a year ago. Earnings grew just 1.8% year over year. That is a sharp slowdown from the nine-month pace, when diluted EPS rose from $5.38 to $6.39. The central tension is that the bank keeps improving on nearly every balance-sheet and credit metric. Yet the forward story this quarter was one of reaffirmation rather than upgrade, against a rate backdrop that has turned less friendly.
The quality of the beat deserves scrutiny. Pre-tax income of $40.0 million was slightly below the $40.6 million earned a year ago. Net income of $36.4 million was essentially flat against $36.7 million. Per-share growth came largely from the share count, as diluted shares fell to 16.45 million from 17.02 million after steady buybacks. The effective tax rate of 8.91% remained a meaningful support, and management guided to 8% to 10% for the fourth quarter. The top-line decline reflects lower gross interest income as asset yields fell from 6.29% to 5.98%. It also reflects capital markets revenue of $16.9 million, well below the $23.8 million booked a year earlier. Underneath, the core banking engine looked healthier:
- Net interest income rose to $68.7 million from $64.8 million a year ago.
- Cost of funds dropped to 2.60% from 3.01%.
- Tax-equivalent NIM expanded 3 basis points sequentially to 3.58%, ahead of guidance.
The conference call reinforced that operating momentum. Loans grew 11% annualized excluding planned m2 runoff, and traditional banking posted its strongest production for a second straight quarter. Credit was the standout:
- Nonperforming assets fell to 0.39% of assets.
- Criticized loans dropped to 1.67%, the lowest since 2019.
- Net charge-offs of $3.1 million were the year's low.
Capital strengthened as well, with CET1 up 33 basis points to 11.01% and tangible book value per share up 11% year over year to $61.79. Expenses landed near the low end of guidance, and the fourth-quarter range sits at $54 million to $57 million. That is below the $55 million to $58 million framed on earlier calls, with data processing costs already down 11% year to date.
The forward signals were more restrained. Several LIHTC transactions slipped into the fourth quarter as rising long rates forced developers to rework capital stacks, leaving Q4 to deliver $18 million to $20 million in capital markets revenue. The $60 million to $70 million four-quarter guide had been raised on three straight calls. This time it was only reaffirmed, and management explicitly withheld upgrades, citing a LIHTC equity shortfall. Fourth-quarter NIM is guided static, down from the expansion ranges offered earlier in the year. The September Fed hike should be slightly accretive near term. However, the balance sheet is modestly liability sensitive, so further hikes trend toward neutral or negative for margin. Tangible common equity to tangible assets fell 28 basis points to 10.43% on AOCI pressure. Quarter-end core deposits also dipped to $7.0 billion from $7.3 billion, though management said they recovered by more than $500 million in October.
There are credible catalysts beyond the next quarter. QCRH plans to shift from Freddie Mac securitizations toward direct whole-loan sales without retaining first-loss B-pieces, with the first transaction targeted for Q1 2027. Selling roughly $100 million of existing B-pieces could free about 100 basis points of CET1. The final core conversion in April 2027 should unlock operating leverage, and management sounded more open to M&A afterward, while stressing a high bar. Longer term, crossing $10 billion in assets brings an expected Durbin interchange hit of about $3 million a year starting in mid-2028.
Investor sentiment moved decidedly more negative, falling from -0.44 to -0.63. That suggests skepticism about whether the fee engine and margin can keep compounding as rates rise. The stock has not reflected that pessimism. Shares are up 5.8% since the open after the July report and sit about 6% above the 200-day moving average near $93.69. The AVWAP trend remains negative, and the price trend is neutral.
The bottom line is that QCRH produced a clean, record quarter with better margins, pristine credit, and rising capital. However, flat pre-tax earnings, a whisper miss, reaffirmed rather than raised guidance, and a liability-sensitive balance sheet in a hiking cycle give bears legitimate ammunition. The fourth-quarter LIHTC deal closings and the new whole-loan sale structure are now the key proof points.
Read our earnings preview for QCR Holdings Inc.: https://www.earningswhispers.com/article/QCRH/20414
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-20 | |
| Oct-20 | |
| Sep-30 | |
| Sep-18 | |
| Aug-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-01 | |
| May-26 | |
| Apr-24 | |
| Apr-23 | |
| Apr-22 |
