Equity LifeStyle Hits FFO Target As Manufactured Housing Strength Offsets Another Cut To RV Outlook
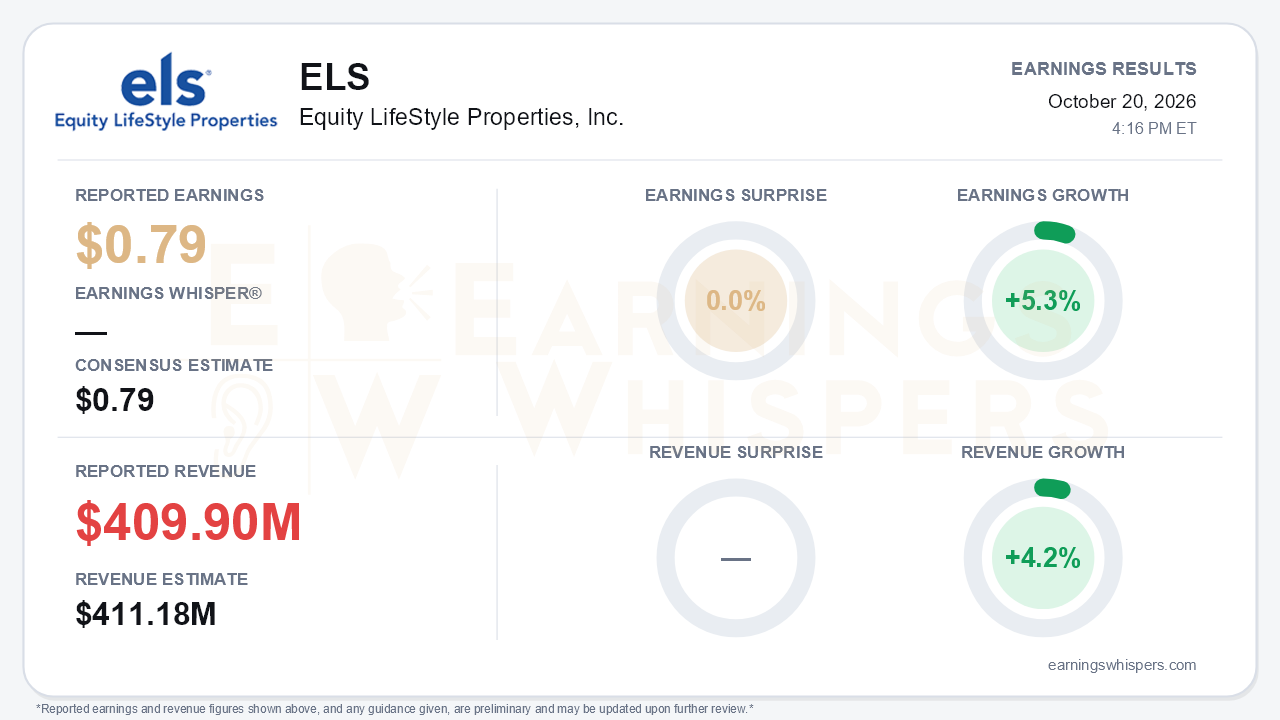
Equity LifeStyle Properties delivered the quarter it promised, but not more. Normalized FFO of $0.79 per share matched the consensus estimate exactly and landed at the midpoint of management's $0.76 to $0.82 guidance range. Earnings grew 5.3% year over year by Earnings Whispers' calculation; the company's own unrounded figure is 4.6%. Revenue of $409.9 million rose 4.2% but missed consensus by 0.3%. The central tension is this: the manufactured housing business is accelerating, and expense control is unusually strong. Yet the seasonal and transient RV business keeps eroding, and that erosion absorbed the upside. As a result, the full-year normalized FFO midpoint stayed at $3.18 rather than moving higher.
The GAAP picture looks weaker than the operating picture, and the gap is explainable. Net income fell to $0.45 per share from $0.50, and NAREIT FFO slipped to $0.72 from $0.77. Both were depressed by a $12.1 million deferred tax valuation allowance, which the company excludes from normalized FFO. Beneath that charge, core property operations were strong. Core revenue rose 4.4% while core operating expenses rose just 1.3%, lifting core NOI 6.7%. That compares with 6.5% in the second quarter and 4.9% in the first, so property-level profit growth has accelerated through the year. Lower insurance and bad-debt costs helped, as insurance and other expense fell 8.8%. Utilities, repairs and real estate taxes still rose.
Manufactured housing drove the quarter. Core MH base rent grew 5.7%, monthly rent per site reached $963 versus $912 a year ago, and occupied sites increased by 99. That brings the year-to-date gain to 166, versus 67 at midyear, which is the occupancy recovery management had flagged on the prior call. Management also cited:
- roughly 12% mark-to-market on new residents;
- double-digit growth in tour requests after a website redesign.
Two caveats temper that story. Average occupancy of 93.8% remains below last year's 94.3%. New home sales volume also fell to 97 units from 119. The full-year MH rent guide was tightened to 5.4%-6.0%, raising the low end. Core expense growth guidance fell to 1.6%-2.2%, from 2.7%-3.7% at the start of the year, partly due to lower Florida property tax notices. Core NOI guidance moved to 5.7%-6.3%.
RV is where bears have legitimate ammunition. Annual RV and marina rent grew a healthy 5.3%. Seasonal and transient revenue, however, fell 5.6% in the quarter and 9.3% year to date. Combined RV and marina rent growth guidance was cut for a third time, to 0.9%-1.5%. The range started the year at 2.4%-3.4%. Management now implies roughly a 7% fourth-quarter decline in seasonal and transient revenue versus a prior flat assumption, because winter booking pace has shown no recovery. It also stepped back from earlier optimism about returning Canadian visitors. Membership trends are mixed:
- core subscription revenue rose 8.4%;
- total memberships slipped to about 107,400 from 108,700 at year-end.
The forward signals are moderating rather than breaking. Preliminary 2027 rent growth assumptions are about 5.1% for core MH and 4.7% for annual RV. The RV figure is below last year's 5.1%, which management called an appropriate moderation after strong years. The MH figure is flat even with higher inflation, and neither assumption includes occupancy gains. Financing is a growing headwind. Secured debt quotes rose to 6.1%-6.6% from 5.25%-5.75% last quarter, and a $200 million term loan matures in 2027. Leverage did ease to 4.3 times Adjusted EBITDAre. A potential longer-term catalyst is the Road to Housing Act, which removes the permanent chassis requirement for manufactured homes, though rulemaking is still underway.
The market setup is more complicated than an in-line print suggests. Earnings Whispers investor sentiment fell from roughly neutral at -0.04 to -0.25. That is a meaningful shift toward skepticism heading into the report. Shares are down 5.4% since the open after the July report, at $61.97, about 2.5% below the 200-day moving average of $63.54. The stock has, however, recovered from its $58.33 quarter-end price. Price and AVWAP trend readings remain negative, consistent with a market that has been leaning against the stock rather than rewarding its steady execution.
The bottom line is that ELS remains a high-quality compounder whose core MH engine and cost discipline are getting better, not worse. The quarter offered no catalyst to break the stock's drift, though. Seasonal and transient RV weakness keeps consuming the upside, 2027 rate assumptions are cooling, and debt is getting pricier. Until RV stabilizes or MH occupancy gains show up more clearly in guidance, the story is reliable but capped.
Read our earnings preview for Equity LifeStyle Properties, Inc.: https://www.earningswhispers.com/article/ELS/20416
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-20 | |
| Oct-12 | |
| Sep-25 | |
| Sep-21 | |
| Sep-14 | |
| Jul-28 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-13 | |
| Jun-10 |
