Financial Institutions Faces Test Of Raised Margin And Return Targets As Loan Growth Outruns Guidance
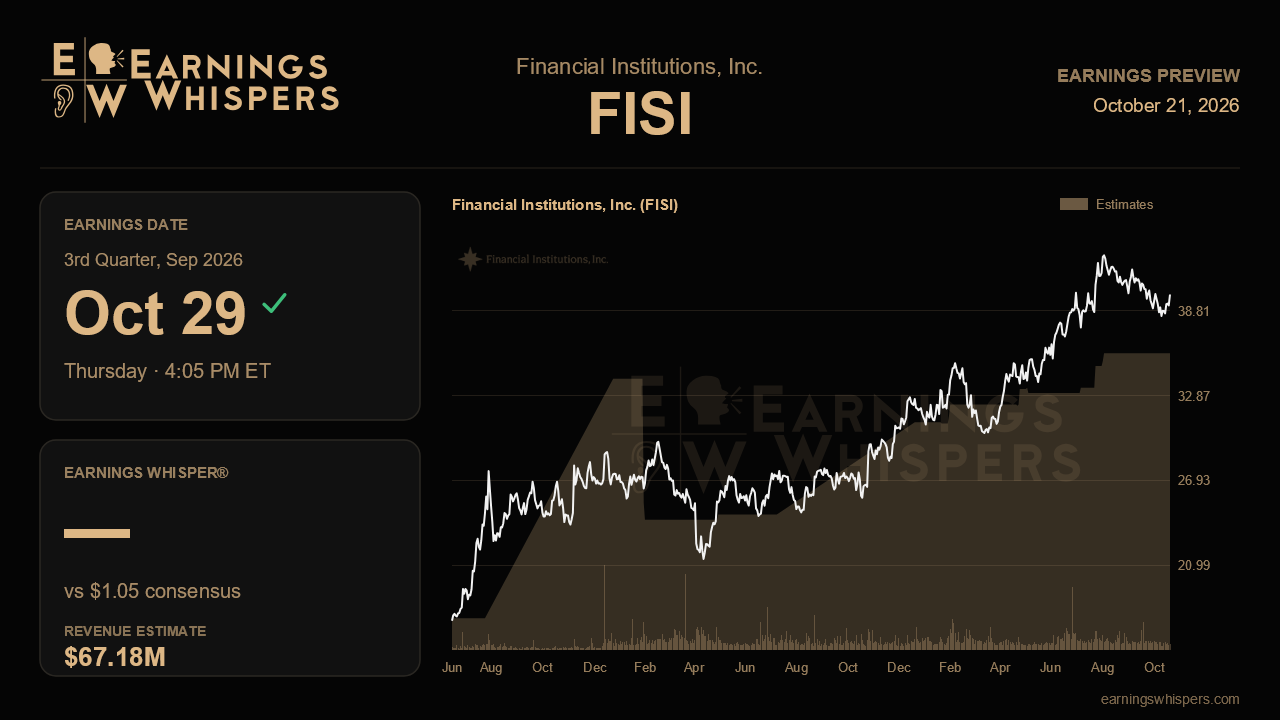
Financial Institutions spent its last earnings call doing something regional banks rarely do all at once: raising its targets for net interest margin, return on assets, return on equity and efficiency in a single sweep, with nothing cut to offset them. The third-quarter report, due after the close on October 29, is the first real check on whether that burst of confidence was well founded or whether the second quarter marked a high-water mark for a bank that is now running into a floor on deposit costs.
The Street is not asking for much on the surface. Consensus calls for earnings of $1.05 a share, a penny above the second quarter's $1.04 and about 6% above the $0.99 earned a year ago. That is modest growth, and essentially flat sequentially, which says analysts expect the gains of the past year to be sustained rather than extended. The revenue consensus of $67.2 million, implying a roughly 30% year-over-year drop, looks far worse than the business suggests and appears to reflect a different revenue definition than the prior figures rather than a genuine collapse. A decline of that size would be impossible to square with management's raised outlook, so earnings, margin and fee trends are the more reliable scorecard here.
The margin is the hinge. Management lifted its full-year net interest margin target three times in succession, from the mid-360s to the upper 360s and most recently to about 370 basis points, with the second-quarter margin landing right around that level. Holding near 3.70% would validate the guidance, but the same call carried a caution: deposit costs are close to bottoming and CD pricing remains competitive. In other words, the cheap funding tailwind that powered margin expansion is fading, and from here the margin depends more on loan growth and asset repricing. Any slippage below the second-quarter level would quickly raise questions about whether the at-least 1.30% return on assets and 12.5% return on equity targets are still within reach.
Loan growth is the second test. Commercial loans jumped 4.3% sequentially in the second quarter, and first-half growth ran near 8% annualized, well ahead of a full-year target management kept at 5%. That gap is either conservatism or an honest acknowledgment of payoff risk, particularly early CRE paydowns tied to the Baltimore loan production office. Continued commercial momentum from the six recently hired lenders and from contractor activity around Micron's Syracuse buildout, enough to offset the deliberate runoff in indirect auto, would support a higher target. A sharp sequential stall would suggest the second quarter pulled demand forward. Fee income matters too: swap fees rebounded with lending activity, servicing income climbed, and assets under management crossed $4 billion. Sustaining those gains helps the efficiency ratio stay below the newly promised 57%.
Credit and capital round out the picture. Net charge-offs fell to 11 basis points from 44 in the first quarter, but the loss reserve sits near the low end of its historical range at about 1% of loans, leaving little cushion if losses normalize. With common equity Tier 1 capital at 11.44% and no buyback last quarter, any signal on capital deployment would be notable.
The market has been less enthusiastic than management. Shares are up 2.6% since the last report, trailing the S&P 500 by about 1.6 points, and sentiment has turned more bearish, moving from mildly negative to a clearly skeptical reading. At $39.95, the stock sits comfortably above its 200-day average but roughly 7% below its post-earnings high of $42.97, so this is not a breakout setup. That skepticism lowers the bar somewhat, but the core question is unchanged: can Financial Institutions hold its margin near 370 basis points as funding tailwinds fade? If it can, the raised return targets look credible and the loan target may move up. If not, last quarter's optimism will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-01 | |
| Aug-26 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jun-30 | |
| May-29 | |
| May-20 | |
| Apr-25 | |
| Apr-24 | |
| Apr-23 | |
| Apr-23 |
