SEI Beats On Record Sales Momentum, But Slowing Growth And A $32.5 Million Charge Complicate The Story
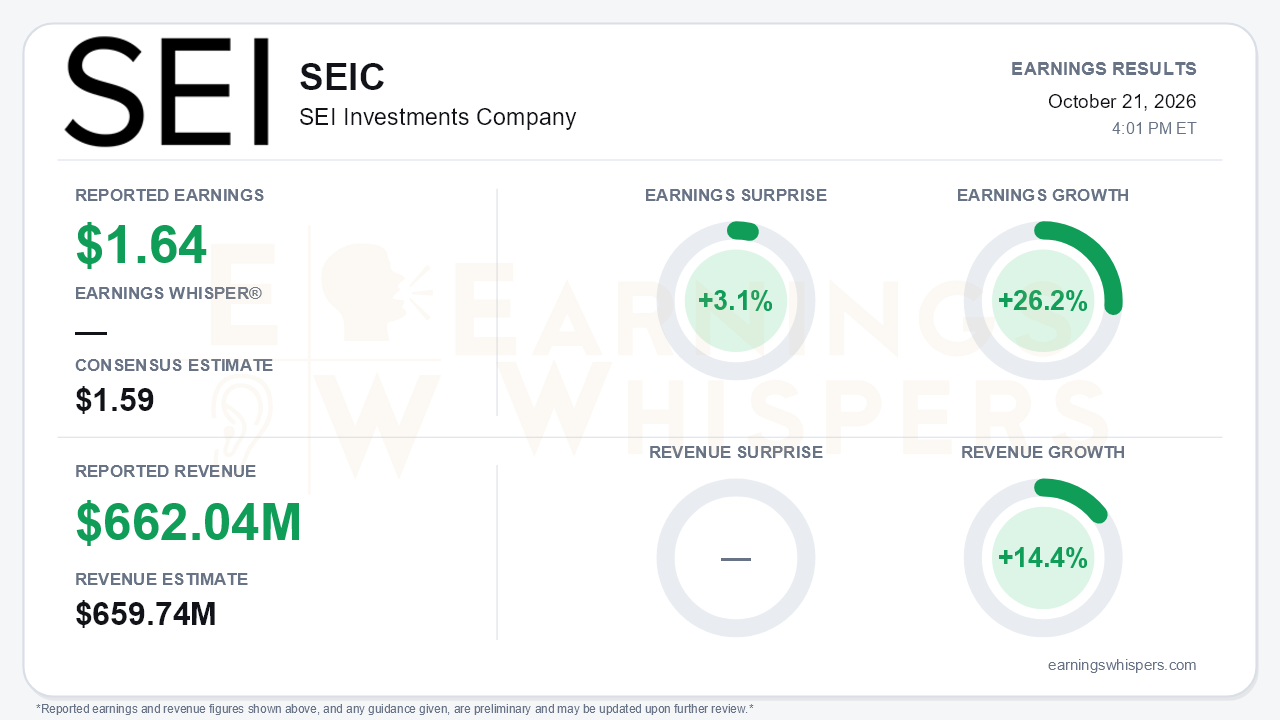
SEI Investments delivered a modest third-quarter beat. Earnings of $1.64 per share topped the $1.59 consensus by 3.1%, and revenue of $662.04 million edged past the $659.74 million estimate by 0.3%. Earnings grew 26.2% year over year and revenue rose 14.4%. The more important development sits below the surface. Year-to-date net sales events reached $157.4 million through September, already above any full year in SEI's history. That pipeline strength is the core of the story. The central tension is that it arrived alongside a clear moderation in growth rates from the second quarter's peak, a sequential dip in adjusted earnings and a sizable GAAP charge.
The gap between GAAP and adjusted results matters this quarter. GAAP diluted EPS rose only 6% to $1.38. The main reason was a $32.5 million one-time charge to terminate SEI's agreement to buy Stratos' Mexican RIA subsidiary, NSC, which management excluded as outside the normal course of business. The adjusted figure carries help of its own. A 3% lower share count added to per-share growth, and Stratos added $23.3 million of revenue. Excluding Stratos, Investment Advisors revenue grew 10% rather than 26%. Interest and dividend income also fell to $6.9 million from $10.2 million. On the call, management acknowledged that adjusted EPS slipped $0.02 sequentially. Two items drove the dip: an $8 million decline in gains from consolidated investment vehicles to a more normal level, and a roughly $6 million incentive-compensation true-up tied to strong year-to-date performance. On the company's own adjusted basis, EPS growth slowed to 24% from 38% in the second quarter. Adjusted operating profit growth eased to 25% from 36%, and revenue growth slipped to 14% from 15%.
Operationally, the franchise looks healthier than the deceleration suggests. Adjusted operating margin of 31% was up 260 basis points from a year ago. It dipped about 80 basis points sequentially, but management said it was up roughly 20 basis points excluding the compensation accrual. Private Banks was the standout, with revenue up 11% and operating profit up 38% as margin widened to 20% from 16%. Investment Managers again generated $32 million of sales events, about 90% tied to alternatives. Its wins included two of the top 25 first-time outsourcers, and SEI is in talks with roughly 15 of the top 100 managers. Assets under administration grew 4% sequentially. The weak spots remain on the asset-management side. Institutional Investors revenue fell 2% with negative sales events. LSV swung to $5.3 billion of net outflows from inflows in the prior quarter, and total AUM was essentially flat at $606.4 billion. Advisors margin also slipped on Stratos technology investment.
The forward catalysts are tangible:
- The retail transfer agency launched August 3, targeting more than $10 million of run-rate revenue with fund administration by the end of 2027.
- Alternatives-in-CIT closings rose to 14 managers from five.
- ETF assets topped $9 billion.
- Management pointed to roughly $50 billion of assets being pushed off a competitor's custody platform and described institutional and wealth pipelines as at all-time highs.
The risks are equally concrete. Management is hiring "as quickly as humanly possible" to convert Investment Managers wins, an admission that capacity could pace revenue conversion. Retail private-credit flows are softening, although management sees no cracks in the pipeline. SEI also provides no formal guidance.
Capital return is accelerating. Repurchases nearly doubled to $215.1 million at an average price of $105.24, management expects a similar fourth-quarter pace, and the board added $800 million of authorization, bringing capacity to roughly $926 million.
Investor sentiment remained positive heading into the report but softened slightly, slipping from 0.163 to 0.139. The stock has treated the story constructively without pricing in perfection. Shares closed at $107.15 the day before the release, up 4.8% from the open after the July report and 16.2% above the 200-day moving average. They sat about 4.5% below the 52-week high of $112.15 set on August 28. Most Earnings Whispers trend readings are positive, including sequential growth and momentum, while price trend is neutral. That fits a stock that has rallied but stalled short of its summer peak.
The bottom line is that SEI's quarter was better on business momentum than on headline growth. Record sales, Private Banks operating leverage and a growing set of new revenue streams preserve a credible growth story. However, decelerating growth rates, the sequential adjusted EPS dip, LSV and institutional outflows, and the NSC charge give skeptics legitimate ammunition. With shares already near the top of their recent range, the next test is whether SEI can convert its record backlog into revenue fast enough to re-accelerate growth.
Read our earnings preview for SEI Investments Company: https://www.earningswhispers.com/article/SEIC/20482
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Sep-30 | |
| Sep-22 | |
| Sep-18 | |
| Sep-10 | |
| Aug-12 | |
| Aug-07 | |
| Aug-06 |
