QuantumScape Narrows Its Loss And Beats Estimates, But A New 100 MWh Factory Plan Raises The Funding Question
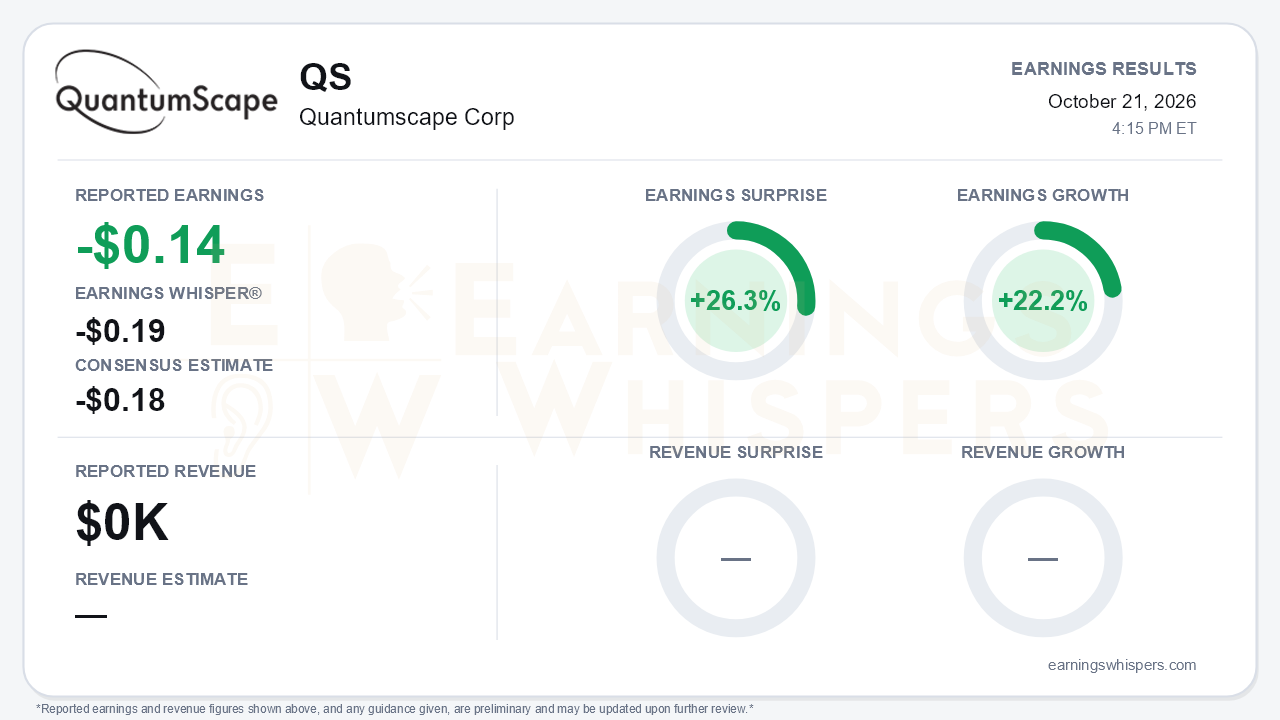
QuantumScape delivered a cleaner-than-expected quarter on the bottom line. The company posted a third-quarter loss of $0.14 per share, well ahead of the -$0.18 consensus and the -$0.19 Earnings Whisper number, for a 26.3% positive surprise. The loss also narrowed 22.2% from a year ago. Reported revenue remained $0.0 million, which is a reminder that QuantumScape is still a pre-commercial story judged on spending discipline and technical milestones rather than sales. The central development, however, was not the beat. Management committed to a 100 MWh mass-production line targeting a 2028 start, a move that strengthens the commercialization narrative but complicates the capital story.
The operating numbers behind the EPS beat show steady cost control rather than a step change. Adjusted EBITDA loss improved to $60.7 million from $64.2 million in the second quarter and $63.2 million in the first. Management reaffirmed full-year guidance for an adjusted EBITDA loss of $250 million to $275 million for the third straight quarter, and spending to date leaves it tracking toward the favorable end of that range. Capex guidance of $27 million to $37 million was also reaffirmed after being cut from $40 million to $60 million last quarter. Liquidity is still the constraint. Cash and liquidity fell to $819.8 million from $859 million in June and $970.8 million at year-end 2025, a slower burn but an uninterrupted decline.
The call was notably more confident in tone, and commercial engagement broadened. QuantumScape recorded its first billings from Honda and its first billings in the QSAS segment, which targets defense, aviation and telecom. It also signed a new agreement with a global mobility manufacturer. Management described the Eagle Line as a "workhorse" after reaching 90%+ uptime last quarter. Mühlbauer joined Murata and Corning to complete an end-to-end equipment chain. The QS Power Block, an in-rack AI data center reference design launched at OCP, claims 4x the power density and 5x the runtime of the OCP spec. Management cited thermal stability above 300C, validated by customers and third parties. Volkswagen's PowerCo is also expanding its scope to data center and robotics applications. Demand signals clearly improved, but none of this has yet turned into firm data center or defense orders.
The weaker data deserves scrutiny. Customer billings, the closest proxy to commercial traction, fell to $9.8 million from $10.8 million in the second quarter and $11.0 million in the first. Year-to-date billings of roughly $31.6 million already far exceed fiscal 2025's $19.5 million, but the sequential trend is pointing the wrong way. The PowerCo relationship keeps being rewritten. Potential development payments were cut from about $131 million to about $75 million last quarter, and transition payments have now been eliminated in favor of technology milestones, all against a Volkswagen restructuring backdrop. The new production line also marks a real departure from the capital-light licensing model. Management targets equipment cost to QuantumScape below $100 million and is pursuing non-dilutive funding. The actual capital plan, however, will not arrive until 2027 guidance. The CFO's temporary medical leave adds another layer of uncertainty at an awkward moment.
The market had been treating the stock harshly heading into the report. Shares closed at $3.98 the day before earnings, down 27.9% since the open following the July report. That left them 42.7% below the 200-day moving average of $6.95 and 39.1% below the inter-earnings high of $6.53 set in mid-August. The stock hit a 52-week low of $3.80 on October 15 and entered the print just 4.7% above that level. Investor sentiment remained negative but improved modestly, moving from -0.36 to -0.31. That shift signals slightly less pessimism rather than conviction. The Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP all weak, although momentum has turned positive.
That is the central tension. The narrower loss, reaffirmed guidance and broader customer roster give turnaround skeptics less to work with on execution. Meanwhile, the 100 MWh line, the unresolved funding plan, slipping billings and repeatedly reduced Volkswagen economics give bears legitimate ammunition on capital and dilution risk. The November 11 Kyoto technology reveal is the next identifiable catalyst.
The bottom line is that QuantumScape beat on earnings through cost discipline and sounded more like a company preparing for production than a lab project. The quarter traded one question for another: execution looks better, but how the company will fund its manufacturing ambition is now the open issue. Until management defines that plan and billings resume growing, a stock sitting near its 52-week low is likely to stay hostage to the cash runway rather than the EPS beat.
Read our earnings preview for Quantumscape Corp: https://www.earningswhispers.com/article/QS/20478
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 4 hours | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Jul-26 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 |
