Exelixis Faces A Test Of Its Trimmed Outlook As Street Models Run Above Guidance
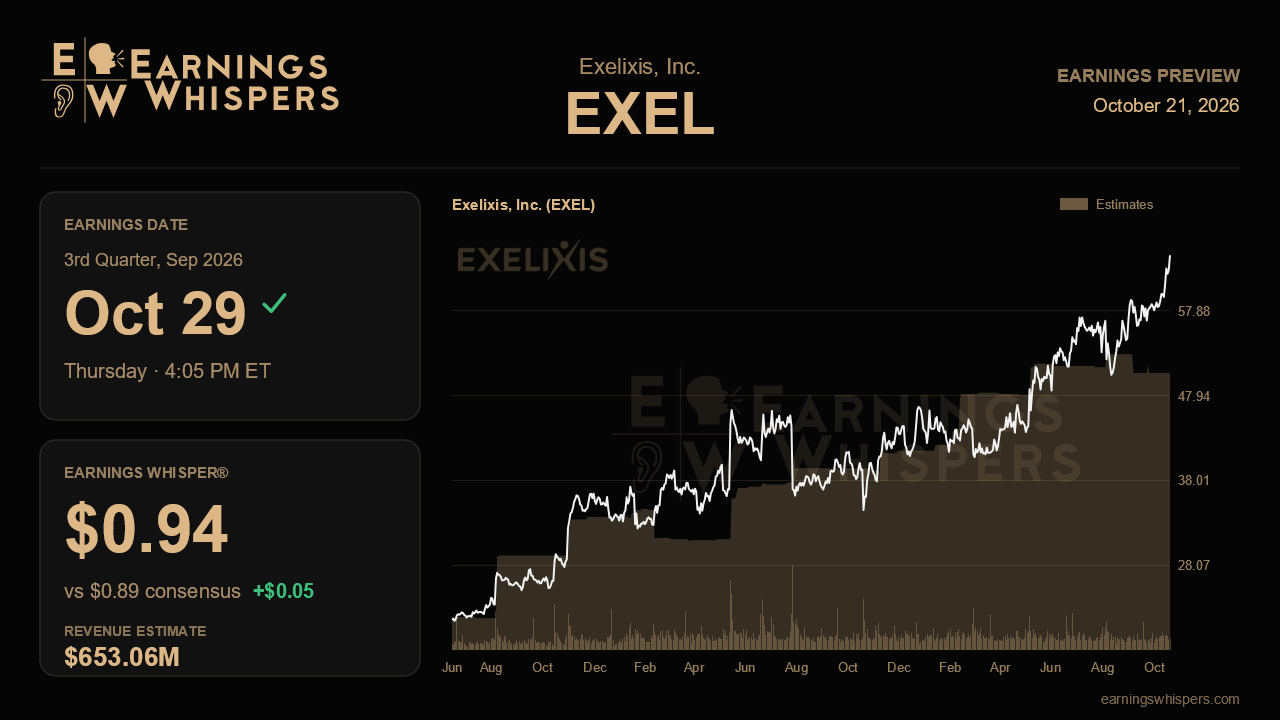
Exelixis heads into its third-quarter report with an unusual mismatch between what management has said and what the market seems to believe. Three months ago the company cut its 2026 revenue forecast for the first time in this cycle, blaming a slower ramp for cabozantinib in neuroendocrine tumors. Since then the stock has climbed about 22% while the S&P 500 went nowhere, and the full-year consensus still sits above the top of management's reduced range. Something has to give, and Thursday's numbers will show whether the guidance cut was conservative housekeeping or the start of a softer stretch.
For the September quarter, analysts expect non-GAAP earnings of $0.89 a share on revenue of $653.1 million. That revenue figure implies growth of about 9.3% from $597.8 million a year ago, a solid but unspectacular pace, and a step up from the $628.7 million reported last quarter. Earnings would compare with $0.75 in the prior quarter and $0.67 a year earlier, helped by heavy share repurchases and a leaner research budget. The Earnings Whisper of $0.94 sits a nickel above consensus, a meaningful gap that suggests the informal bar for a beat is higher than the published one.
The guidance math is where this report gets interesting. Management now expects 2026 revenue of $2.50 billion to $2.55 billion, down from $2.525 billion to $2.625 billion, yet the consensus of $2.59 billion sits above the new ceiling. Either analysts have been slow to update, or they are betting the cut was overly cautious. A quarter that lands comfortably ahead of $653 million, paired with a reaffirmed or nudged-up range, would validate the optimists. A result near consensus with an unchanged outlook would likely force estimate reductions toward the guided range, which is a less friendly setup for a stock trading near its highs.
Operationally, the core cabozantinib franchise has given little cause for concern. U.S. net product revenue rose from $555 million to $573 million between the first and second quarters, prescription share held at 47%, and volume growth of 12% ran well ahead of the broader market. Gross-to-net deductions are also improving, with management projecting 30% to 31% for the year versus an earlier 31% to 32%, which supports pricing realization. The open question is neuroendocrine tumors. Management described patient uptake as more gradual than expected, reflecting the slow-moving nature of these cancers, and acknowledged that its own Stellar 311 trial may be pulling some patients away from commercial therapy. Evidence that new-patient share in later-line neuroendocrine disease kept expanding beyond the 45% level would go a long way toward easing the main worry from last quarter.
The pipeline adds a second layer. Zanzalintinib has a regulatory decision expected in December resting on the overall Stellar 303 result after a subgroup endpoint missed, and top-line data from Stellar 304 in non-clear cell kidney cancer are due in the second half. Any update on timing, along with commentary on the newly activated Stellar 316 and enrollment in meningioma, will shape how much of the recent rally reflects pipeline hopes rather than near-term sales.
Sentiment has warmed considerably, with bearish readings easing to 17.1% from 37.2% before the last report, and the stock at $64.39 is pressing against its post-earnings high of $64.42, far above its 200-day average near $50. That positioning leaves less room for a merely adequate quarter. The deciding factor is whether cabozantinib sales run strong enough to put the full-year range back in play, proving last quarter's cut was a speed bump rather than a turn in the growth story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-07 | |
| Sep-30 | |
| Sep-11 | |
| Sep-11 |
Exelixis, An IBD 50 Stock, Pulls A Bearish Move With Surprise Cancer Delay
EXEL
Investor's Business Daily
|
| Sep-11 | |
| Sep-04 |
IBD Stock Of The Day Exelixis Hits Earnings Snag - And Then Breaks Out
EXEL
Investor's Business Daily
|
| Sep-02 | |
| Sep-01 | |
| Aug-31 | |
| Aug-28 | |
| Aug-24 |
