Erie Indemnity's Q3 Test: Can Online Quoting And New Auto Products Halt Shrinking Policy Counts?
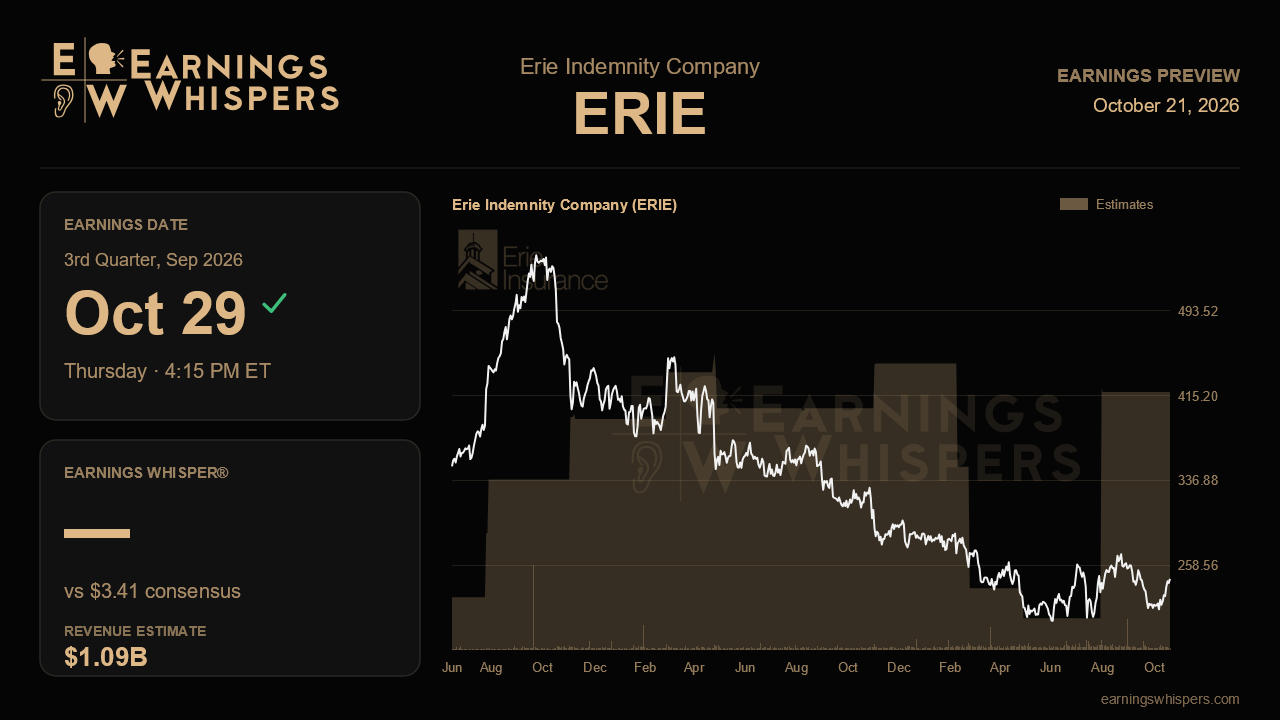
Erie Indemnity heads into its third-quarter report with a split personality. The insurance operation it manages has largely repaired its underwriting, but the growth engine that feeds Erie's own revenue keeps losing speed. Last quarter's call made that tension explicit, with management calling growth its primary challenge even as the Exchange's combined ratio improved 13 points from a year earlier. This report, due after the close on October 29, will show whether the new sales tools rolled out this year are starting to slow the erosion or whether the slowdown has simply rolled into another quarter.
The Street is not asking for much. Consensus calls for earnings of $3.41 per share, down 2.6% from $3.50 a year ago and slightly below the $3.45 posted last quarter, on revenue of about $1.09 billion, up a modest 2.2%. That revenue forecast is essentially flat with the second quarter, which tells you analysts expect premium growth at the Exchange to keep cooling rather than snap back. Erie does not issue formal guidance, so the consensus figure is the only real yardstick, and it already reflects a business that is growing its top line slowly while its costs grow faster.
That cost side matters more than it might seem. Commission expense rose 9.6% in the second quarter, driven by higher agent incentives that are tied to the Exchange's improved profitability. In other words, the underwriting recovery that looks so good at the Exchange level partly comes back as a cost burden for Erie itself, which helps explain why analysts expect lower earnings despite higher revenue. If commission growth keeps outrunning revenue growth, the margin squeeze becomes a structural issue rather than a one-quarter quirk.
The growth numbers are where the narrative will be won or lost. Direct written premium growth slid from 7.6% in the third quarter of 2025 to 3.3% last quarter, policies in force fell 2.0%, and retention dropped for a fourth straight quarter to 87.5%. Average premium per policy growth also moderated to 6.8% as rates reached adequacy and management declined to cut prices broadly. That combination is the worry: pricing is no longer doing the heavy lifting, and the customer base is shrinking. Validation would look like retention stabilizing near 87.5% or ticking up, policy count declines narrowing, and some sign that Erie Secure Auto, now in 10 states including Pennsylvania since May, and the online quoting platform, which management said converts at nearly double the legacy rate, are generating new business. A further decline in retention or a policy count drop worse than 2% would suggest those initiatives are not yet big enough to matter.
Underwriting results deserve attention too, though the bar is getting higher. The year-ago third quarter Exchange combined ratio was 100.6%, a far easier comparison than the 116.9% the second quarter lapped, so double-digit year-over-year improvement is unlikely. Investors should watch whether the ratio holds near or below 100% and whether policyholder surplus, which reached $10.7 billion, keeps climbing. Updates on the succession plan for CEO Tim NeCastro, who retires at the end of 2026, could also surface.
Sentiment has warmed noticeably, with readings far less bearish than before the last report, yet the stock has gained only 2.2% since then, trailing the S&P 500 by about a point. Shares sit almost exactly on their 200-day moving average and roughly in the middle of their post-earnings range, well short of the $271 high. That is a market waiting for proof. The central question is simple: can Erie show that its new products and digital tools are beginning to stop the policy count bleed? Profitability has been fixed; growth is now the whole story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-12 | |
| Aug-26 | |
| Aug-25 | |
| Jul-31 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-17 | |
| Jul-15 | |
| Jun-04 | |
| Apr-25 | |
| Apr-24 | |
| Apr-23 |
