Pathward Beats On Buybacks, A Low Tax Rate And Better Adjusted Margin, But A 5.61% NPL Ratio Still Defines The Story
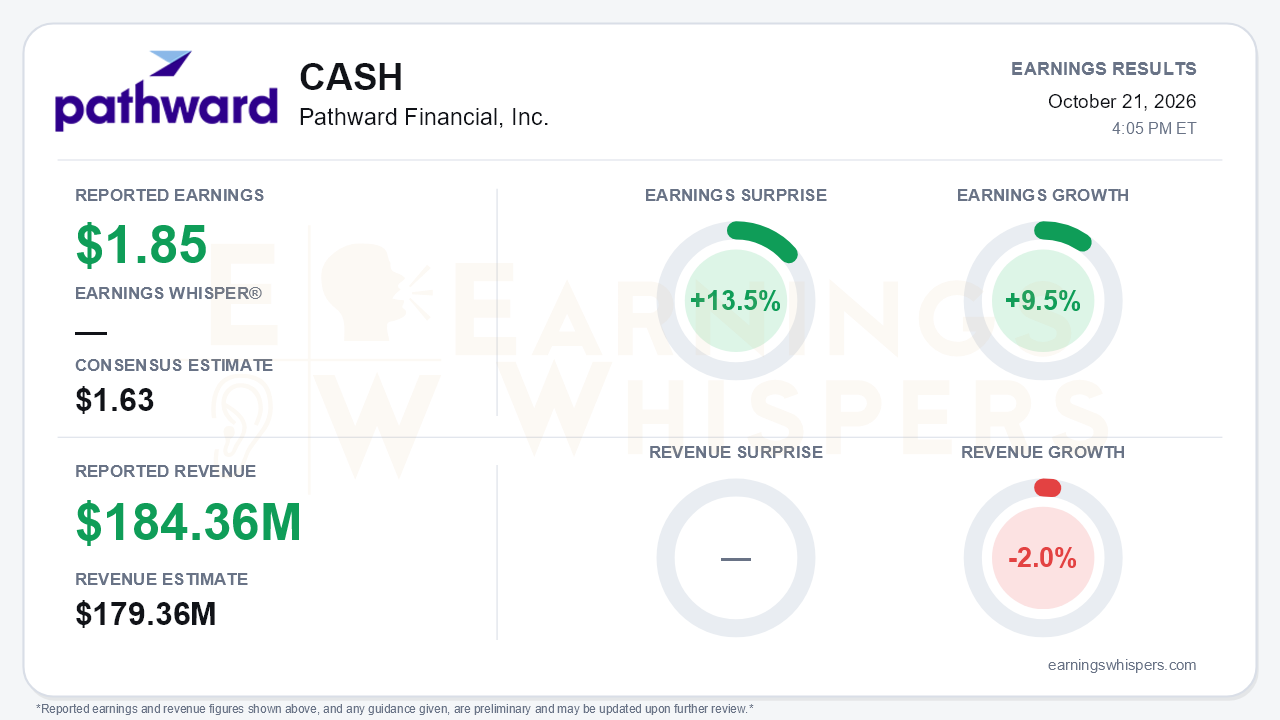
Pathward Financial (NASDAQ: CASH) reported fiscal fourth-quarter earnings of $1.85 per share, beating the $1.63 consensus by 13.5% and rising 9.5% from a year ago. Revenue of $184.36 million topped expectations by 2.8% but fell 2.0% year over year. The beat is real, and so is improvement in the core franchise: adjusted margin, fee income, originations and partner renewals all moved the right way. But the quality of the beat deserves scrutiny, and the credit book is still getting worse. That is the central tension.
The EPS growth came from below the operating line. Net income was essentially flat at $38.6 million versus $38.8 million, and pre-tax income fell to $43.1 million from $48.4 million. Two things turned that into per-share growth. Diluted shares fell about 9% to 20.85 million. The effective tax rate also dropped to 10.1% from 19.2%, helped by renewable energy tax credits and a prior-year life insurance surrender. Provision expense was $10.3 million against a $6.4 million reversal a year ago. Even so, reported provisioning was flattered by a $9.0 million reduction in commercial finance reserves, as specific reserves were consumed by charge-offs. Commercial finance coverage fell to 1.46% from 1.71% in June, while nonperforming loans rose to $289.3 million, or 5.61% of loans. That ratio was 5.28% last quarter and 2.05% a year ago. Commercial loans more than 89 days past due and still accruing roughly doubled sequentially to $32.8 million. Bears have legitimate ammunition: reserve coverage is thinning while problem assets keep rising.
The operating picture underneath is considerably healthier. Reported net interest margin fell to 6.79% from 7.46%, but that decline mostly reflects the October 2025 sale of a credit sponsorship portfolio booked on a gross basis. Adjusted NIM, which captures the economics more cleanly, rose to 5.51% from 5.27% in the June quarter and 5.43% a year ago. Noninterest income grew 12%, with card and deposit fees up to $35.8 million from $27.8 million as last year's contract wins ramped. Custodial deposits held at other banks climbed to $630 million from $210.5 million. Originations nearly doubled to $2.2 billion, and management called that level the new run rate. Commercial finance loans grew 13% year over year. Noninterest expense fell 10%, largely because legal and consulting costs halved.
The call preserved a credible growth story. Management reaffirmed fiscal 2027 EPS guidance of $9.50 to $10.00 and added the H&R Block renewal through mid-2030, following the earlier Claire renewal. Executives also stressed that no partner exceeds 5% of revenue, a direct answer to concerns about fintech partners seeking their own charters. Securities runoff toward an $800 million to $1 billion floor should keep recycling roughly $150 million a year from low-yielding bonds into higher-yielding loans.
The caveats are meaningful:
- **Credit:** Management described charge-offs as episodic and tied to a single renewable-energy developer. However, funding completion of those projects will keep adding to nonaccruals until the assets are sold.
- **Expenses:** The fiscal 2027 cost ramp is pulled forward into the December quarter and first half, so the 10% expense decline will not repeat soon.
- **Margin:** Management concedes the current asset sensitivity is temporary.
- **Buybacks:** The previous framing of repurchasing 70% to 80% of net income was dropped in favor of vaguer language. That is notable given how much of this quarter's per-share growth came from the shrinking share count.
- **Balance sheet:** Tangible book value slipped to $24.73 from $25.83 as unrealized securities losses widened. Short-term borrowings doubled to $334.5 million while deposits fell 3%.
Investors were not leaning bullish into the print. Earnings Whispers sentiment swung from a neutral 0.04 to -0.41, a substantial deterioration. Shares sat at $73.93 before the report, down 4.4% since the open after the July release and nearly 13% below the 200-day moving average of $84.89. The stock had fallen about 19% from its early-August high of $91.70 and traded just 5.6% above the $70 low set on October 14. Earnings Whispers trend readings remain mostly negative, with price, sequential growth and AVWAP all pointing lower. This setup gives a clean beat and reaffirmed guidance room to surprise skeptics. Credibility is the constraint: management raised fiscal 2026 guidance in the first quarter, cut it in the third, and finished below the original range.
The bottom line is that Pathward's franchise is executing well. Adjusted margin, fee growth, originations and partner renewals all support the fiscal 2027 targets. But the headline beat leaned on a lower share count, a lighter tax rate and reserve drawdowns, while the NPL ratio climbed again. Until nonperforming renewable-energy loans start resolving rather than accumulating, the market is likely to discount guidance that already proved fragile once this year.
Read our earnings preview for Pathward Financial, Inc.: https://www.earningswhispers.com/article/CASH/20444
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Aug-20 | |
| Aug-05 | |
| Jul-30 | |
| Jul-30 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-08 |
