DexCom's Whisper Bar Sits Above Consensus As Ireland Costs Test Its Margin Story
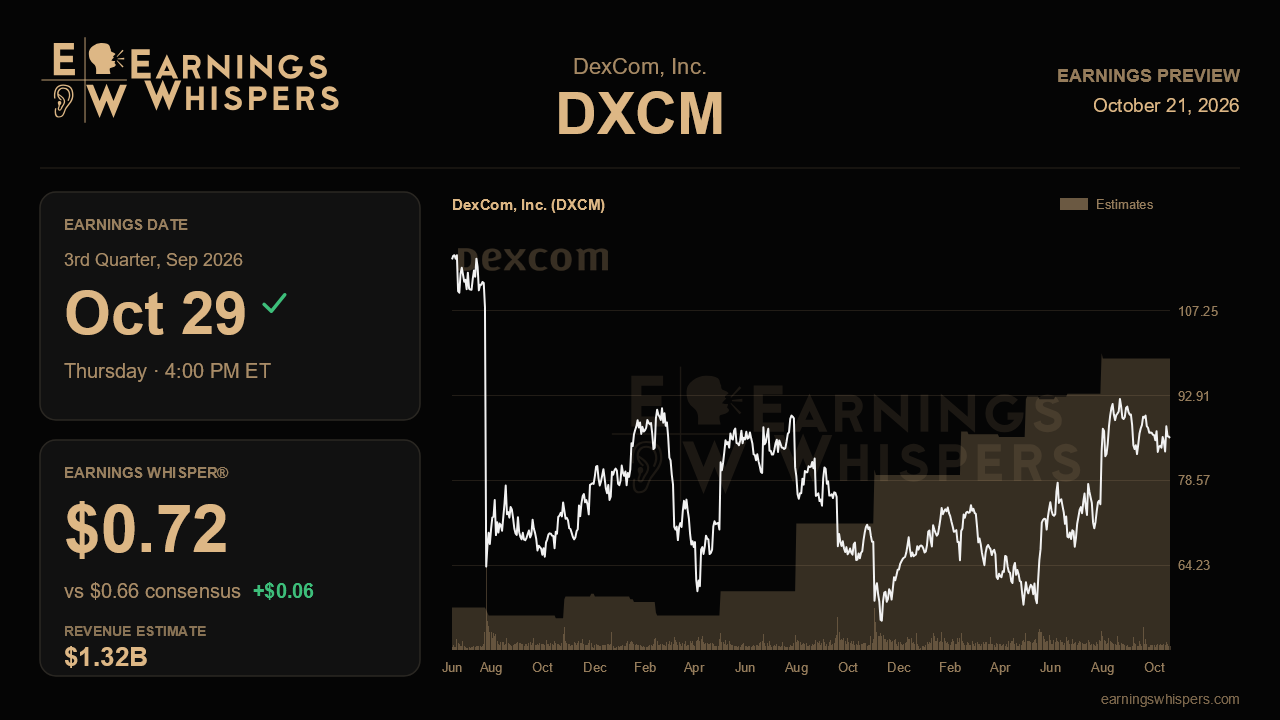
DexCom heads into its third-quarter report with a reversal in fortune that is easy to see. Three months ago the company was still trying to convince skeptics that the sensor quality problems of late 2025 were behind it. It then delivered its first outright revenue guidance raise in several quarters, lifted every margin target, and posted a strong randomized trial readout for type 2 patients who do not use insulin. The question now is less about repair and more about whether DexCom can sustain that momentum through a quarter that management itself flagged as carrying extra cost pressure.
Wall Street expects earnings of $0.66 a share on revenue of $1.32 billion, which would represent growth of roughly 8% and 9%, respectively, from a year ago. That is steady rather than spectacular, and notably the EPS estimate sits below the $0.70 DexCom earned last quarter on nearly identical revenue. The Earnings Whisper of $0.72 points to a meaningfully higher unofficial bar, above both consensus and the prior quarter's result. In other words, the market appears to be betting that the sequential margin dip analysts have modeled will prove milder than feared. For the full year, DexCom narrowed its revenue outlook to $5.18 billion to $5.25 billion, and the $5.22 billion consensus sits just above the midpoint. The Street is not demanding another raise, but it is leaning toward the upper half.
Margins are the most important swing factor. Reported gross margin climbed from 61.3% a year ago to 64.1% last quarter, and full-year guidance was lifted to about 64%. But management warned that the Ireland plant, scheduled to turn on in the fourth quarter, would add hiring and depreciation costs during the third quarter before shifting fixed costs into cost of goods sold. A gross margin that holds near 64% despite that drag would validate the view that the growing mix of 15-day sensors is a durable tailwind. A sharper step down would raise questions about whether the newly raised operating margin target of 23.5% to 24% still looks comfortable. The share buyback also matters here, since roughly $600 million of the $1 billion authorization was executed in the second quarter, giving per-share results a lift from a lower count.
On the top line, the key evidence is U.S. new customer starts. Management described a sequential uptick last quarter, matching the first quarter's record pace and erasing the dip caused by last year's deployment complaints. Continued strength would support the claim that product quality is no longer a drag. Internationally, the picture is more complicated. DexCom trimmed second-half international revenue by about $15 million for currency and acknowledged tougher comparisons ahead, so organic growth abroad, including early traction for DexCom Flex in Germany and the 15-day sensor's Canadian clearance, needs to offset those factors. Any update on NutriSense, the redesigned Stelo app, or CMS coverage for non-insulin type 2 patients will also be scrutinized, though the base case for that coverage decision remained mid-2027 even after the trial data.
Sentiment has swung decisively, moving from clearly bearish ahead of the last report to moderately bullish now. The stock has gained about 7% since the prior release, outpacing the S&P 500 by roughly four percentage points, and trades well above its 200-day moving average. Its entire post-earnings range sits above last quarter's high, though at around $86 it remains about 7% below the recent peak of $92.59 rather than pressing for a breakout.
That combination means the easy part of the recovery trade is done. For the narrative to hold, DexCom needs to show that customer starts are still climbing and that gross margin can absorb the Ireland ramp without giving back much of this year's hard-won expansion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-02 | |
| Sep-28 | |
| Sep-28 | |
| Sep-15 | |
| Sep-14 |
