DexCom Beats And Raises Margin Outlook Again As U.S. Acceleration Offsets An International Slowdown And New CVS Access Risk
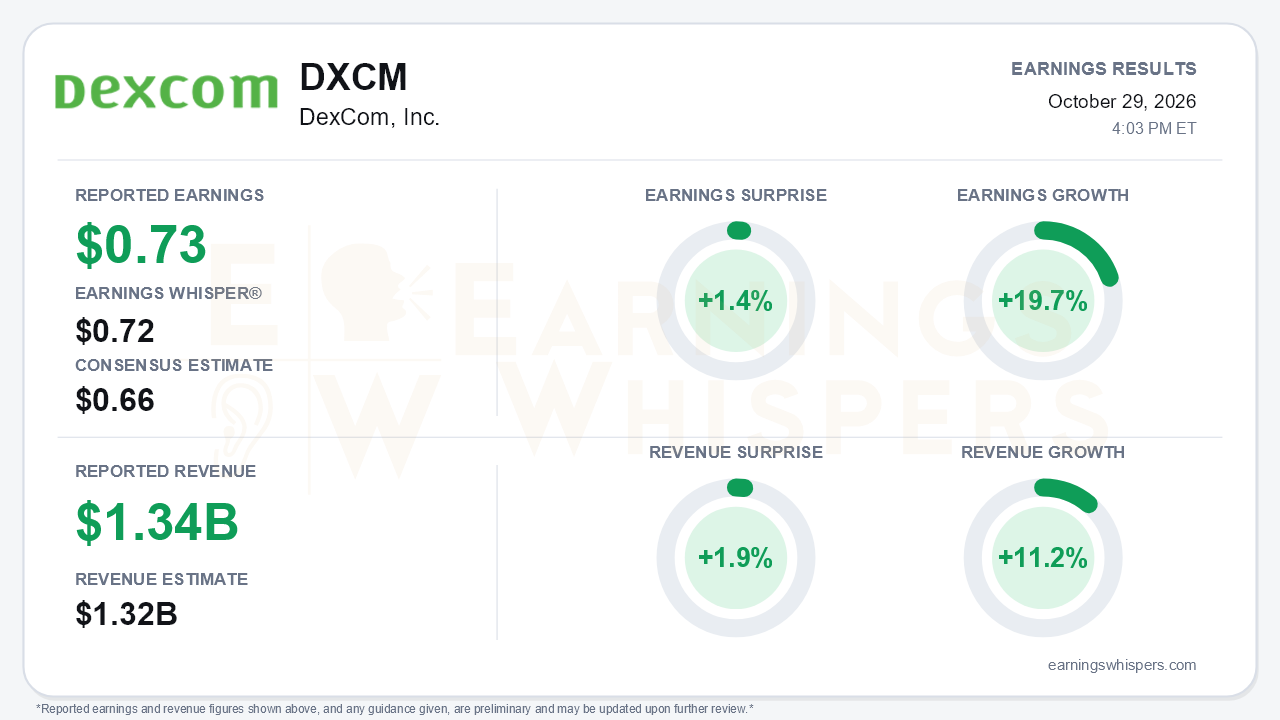
DexCom delivered a clean beat-and-raise in the third quarter. Non-GAAP earnings were $0.73 per share, ahead of the $0.66 consensus and edging past the $0.72 Earnings Whisper number, for a 1.4% surprise. Revenue of $1.345 billion topped the $1.32 billion consensus by 1.9%. Earnings grew 19.7% year over year on 11.2% revenue growth, and management lifted full-year margin guidance for a fourth straight time. The central tension is that profitability and U.S. momentum are clearly improving while consolidated top-line growth keeps decelerating. Revenue growth slowed from 15% in the first quarter to 13% in the second and 11% now, and the guidance implies roughly 10% in the fourth quarter.
The quality of the earnings beat is mostly operational, with one caveat. Non-GAAP gross margin expanded to 65.1% from 61.3% a year ago. It also improved sequentially from 64.1% in the second quarter and 63.5% in the first, reaching its highest level since late 2022. Non-GAAP operating margin rose 270 basis points to 25.3%. The caveat is that buybacks did meaningful work on the per-share number. Non-GAAP diluted shares fell to 375.8 million from 399.7 million, so per-share growth outpaced the rise in non-GAAP net income, which went to $275.0 million from $242.5 million. On a GAAP basis, net income actually dipped to $275.1 million from $283.8 million, but only because the prior-year quarter included an $82.7 million equity-investment gain. GAAP operating income rose 35% to $327.2 million, and that is the more honest read on the core business.
Beneath the headline, the geographic mix shifted sharply. U.S. revenue grew 14% to $970 million, accelerating from 11% in each of the first two quarters. Management attributed this to multi-quarter share gains led by Type 2 patients not on insulin and said 2026 is tracking toward a record year for new patients. International growth, however, slowed to 5% from 16% organic in the second quarter. Management called the slowdown temporary, saying the business is lapping reimbursement wins from the second half of 2025. Management was emphatic that pricing is stable and that utilization and retention are holding steady. That pushback matters because competitors have flagged category pricing pressure, particularly in cash-pay markets outside the U.S.
The catalyst slate is unusually dense:
- **CONNECT trial:** The randomized trial was published in The New England Journal of Medicine. Management expects it to influence an update to the ADA Standards of Care in the coming weeks.
- **CMS coverage:** A coverage decision for Type 2 patients not on insulin is still expected by year-end, effective mid-2027.
- **G7 15 Day rollout:** The system launches in Canada in November, and Japan has cleared it for an early-2027 launch.
- **Distribution:** DexCom signed a deal to acquire its largest remaining European distributor and go direct, with closing expected in 2027.
- **Capital return:** The $1 billion 2026 buyback is complete, and a new $1 billion authorization was announced.
Bears have legitimate ammunition, though. DexCom lost a CVS PBM formulary position, worth under 4% of U.S. revenue. Management expects limited 2027 financial impact because of price offsets, but the loss raises the broader risk of exclusive formulary deals. Full-year gross margin guidance was also held at roughly 64% rather than raised. Startup costs at the Ireland facility imply a sequential step-down of about 130-150 basis points in the fourth quarter, with the drag extending into the first half of 2027.
The market setup is more complicated than the surprise implies. Investor sentiment swung meaningfully, from -0.38 at the prior report to +0.11. That is a move from clearly negative to modestly positive, though hardly euphoric. The stock has not followed. Shares entered the report at $78.62, down 1.6% since the open after the July report. They sat 15.1% below the 52-week high of $92.59 set in late August and just 2.7% above the inter-earnings low reached two days before the release. The stock remains 5.6% above its 200-day moving average, so the longer-term trend has not broken. Still, the round trip from the August peak shows how quickly enthusiasm faded as investors focused on deceleration and access risk. Sequential growth and momentum trend readings are positive, while AVWAP remains negative, reflecting that pressure.
The bottom line is that DexCom posted an execution-driven quarter: accelerating U.S. growth, record-level gross margins, steadily rising profitability guidance and aggressive capital returns. These results undercut the more pessimistic narratives that weighed on the shares after August. The open questions are whether international growth rebounds as management promises, whether the PBM loss stays contained, and whether clinical and coverage catalysts can re-accelerate consolidated growth from a roughly 10% exit rate. Until then, margin expansion and buybacks are carrying more of the earnings story than the top line.
Read our earnings preview for DexCom, Inc.: https://www.earningswhispers.com/article/DXCM/21185
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours |
Diabetes Wearable-Maker Handily Beats Earnings Views, Hikes Sales Guide
DXCM
Investor's Business Daily
|
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 |
