Minerals Technologies Faces A Price-Cost Test As Street Sets Bar Below Its Own Guidance
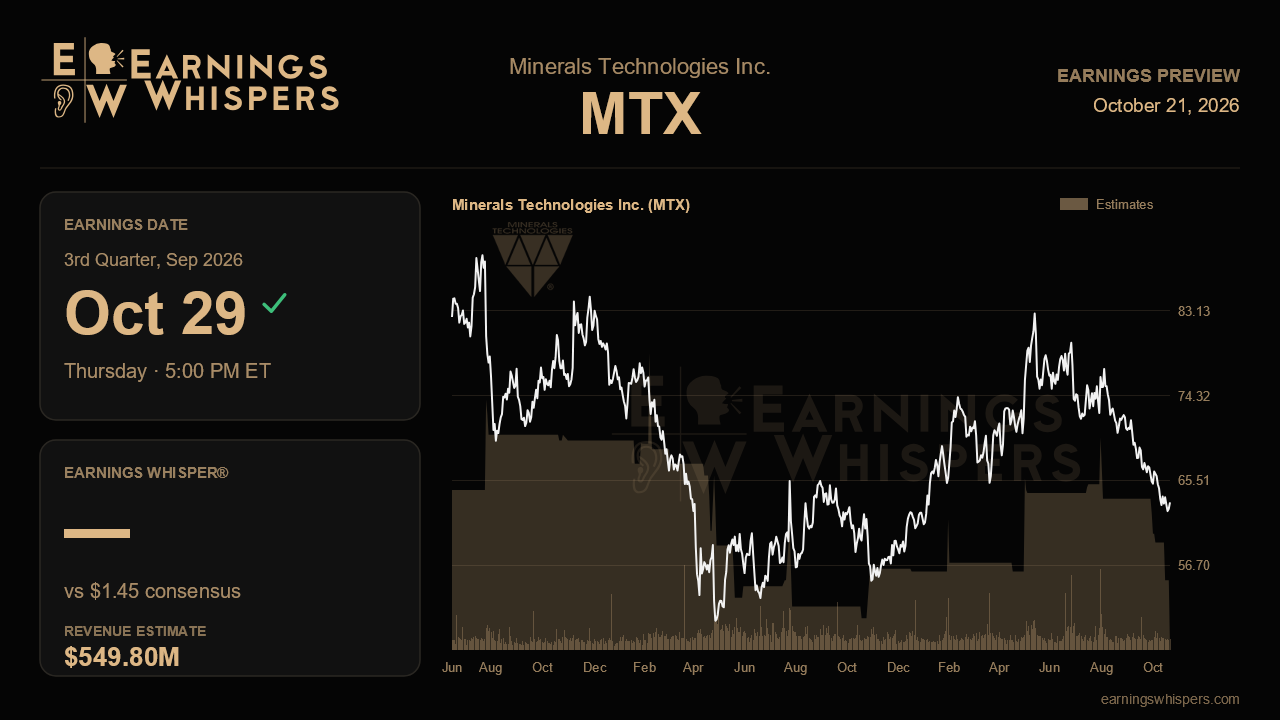
Minerals Technologies heads into its third-quarter report with a peculiar expectations gap. Three months ago management guided third-quarter earnings to $1.55 to $1.60 a share, already a step down from the prior quarter's range. The Street has gone further, settling on a consensus of $1.45. That figure is about 6.5% below the $1.55 earned a year ago and implies analysts doubt the company can hold even its trimmed outlook. Unless the consensus reflects a different earnings basis, the market is effectively pricing in a miss of management's own range before the numbers arrive after the close on October 29.
Revenue tells a calmer story. Consensus calls for $549.8 million, up 3.3% from a year ago and essentially flat with the $548.4 million reported last quarter. That is modest growth, a bit softer than the 7% first-half pace and the mid-single-digit growth management reaffirmed for the year. The problem has never been demand. It is what happens between the top line and the bottom line.
That gap is the heart of this report. On the last call, management said input costs for energy, freight and raw materials kept rising from the first quarter to the second and again into the third, with most of the pressure landing in Consumer & Specialty, where contractual pricing trails costs by roughly 90 days. The company expected to be about $5 million to $6 million upside down on price versus cost in the third quarter, roughly double the temporary hit it had assumed a quarter earlier, and it cut its full-year operating margin target to about 13% to 13.5% from around 14%. Validation would be a third quarter that lands inside the guided range, a price-cost shortfall no larger than flagged, and a clear statement that the fourth-quarter margin recovery is on schedule. A challenge would be another round of cost increases, a wider price-cost gap, or any hint that the snapback slips into 2027. Consumer & Specialty volumes matter too, since cat litter and personal-care orders were pushed out of the second quarter into the back half, and a new Fabricare product is supposed to start helping in the fourth quarter.
The offset is Engineered Solutions, which posted a record 17.8% segment margin last quarter. Environmental and infrastructure sales were up 19% year to date, refractories benefited from MINSCAN installations, and the Raffinol bleaching earth expansion entered the quarter fully ramped with a booked-out order book. Evidence that those sales flowed through in the third quarter, along with progress on Fluorosorb, where specified systems reached 18 versus a target of 10, would show the growth engine is real. Soft residential construction remains a drag that management has not seen improve. Investors will also want management to connect the new projects introduced at its September Investor Day to tangible earnings timelines, and to give any update on the talc litigation that prompted a $290 million reserve charge.
The market has already rendered a harsh preliminary verdict. Shares have fallen 12.4% since the last report while the S&P 500 gained 3.3%, and at $62.56 the stock trades well below its 200-day moving average of $71.47 and barely above its post-earnings low of $61.82. The entire post-report range sits beneath the prior quarter's trough of $70.55. Sentiment has swung from mildly bullish heading into the last report to firmly bearish now. That pessimism lowers the hurdle, though it guarantees nothing.
Ultimately, this quarter comes down to whether inflation has finally stopped outrunning pricing. If management delivers within its guided range and confirms that Consumer & Specialty margins turn the corner in the fourth quarter, a beat against a discounted consensus could ease some of the gloom. If costs climbed yet again, the narrative of delayed but inevitable margin recovery starts to look like a moving target.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-05 | |
| Oct-01 | |
| Oct-01 | |
| Sep-23 | |
| Sep-16 | |
| Sep-01 | |
| Aug-24 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-28 | |
| Jul-22 | |
| Jul-02 |
