Texas Capital Beats And Raises On Fee Momentum, But Credit Migration And A Shrinking Mortgage Book Complicate The Record Quarter
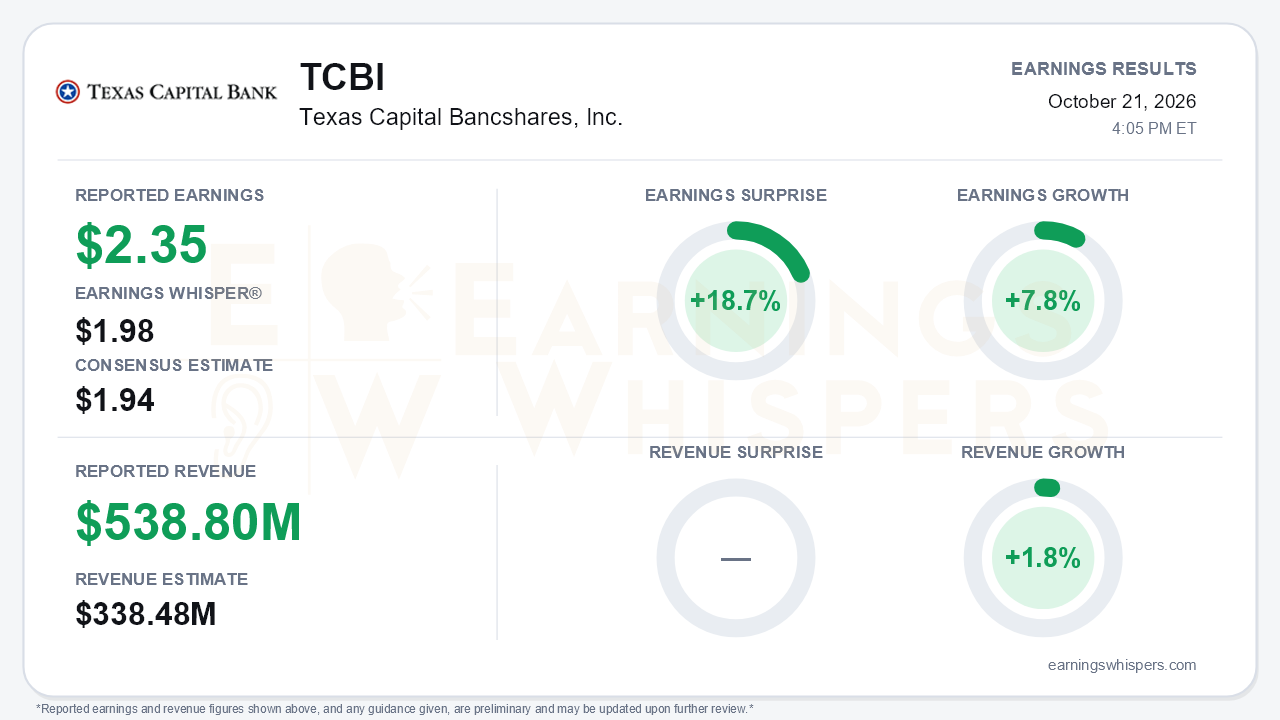
Texas Capital Bancshares (AMEX: TCBI) delivered a clear beat in the third quarter. Adjusted earnings of $2.35 per share topped the $1.94 consensus by 18.7% and cleared the $1.98 Earnings Whisper number. EPS grew 7.8% year over year. The sequential picture is stronger: adjusted EPS rose from $1.58 in Q1 to $1.88 in Q2 and now $2.35, a record. GAAP diluted EPS was $2.28 after $4.3 million of restructuring charges. The headline revenue comparison needs a caveat. Earnings Whispers reports revenue of $538.8 million, up 1.8% year over year. That figure combines gross interest income with fee income, while the $338.48 million consensus appears to reflect the company's net revenue convention. On that net basis, total revenue was a record $356.6 million, versus $340.4 million a year ago. Most of the 59.2% revenue surprise is therefore a difference in how revenue is measured. The genuine top-line beat was real but more modest.
The quality of the quarter is better than a typical bank beat because it came from operations rather than reserve releases. Provision expense actually rose year over year, to $17.0 million from $12.0 million. Net interest income reached a record $275.0 million. Net interest margin expanded 16 basis points sequentially to 3.44%, well above the low-to-mid 3.20s management had guided in July. Loan yields rose while deposit costs increased only 5 basis points. Fees were the bigger story. Non-interest income climbed to $81.6 million from $68.6 million a year ago, and investment banking and trading posted a third straight record at $46.7 million. Adjusted pre-provision net revenue of $157.0 million marked a ninth consecutive quarter of year-over-year expansion. The adjusted efficiency ratio improved to 56.0% from 60.4% in Q2.
The call produced the first explicit full-year guidance raise of 2026. Revenue growth guidance moved to high single digits, after three calls at mid-to-high single digits. Fee guidance rose to $295-300 million from $270-290 million, with investment banking now tracking roughly 40% annual growth. Management guided fourth-quarter NIM to 3.45-3.50% and framed a higher-rate backdrop as a tailwind. Its rate assumption now has the Fed's upper bound at 4.25% at year-end. The tone was noticeably more expansive. Management called it the "most complete quarter" in the company's history and announced a renewed frontline hiring push, new offices in New York, Los Angeles and Chicago, a technology leadership overhaul, and a private bank build-out targeted for 2027.
Bears have legitimate ammunition, however, and the credit book is the central tension. Criticized loans rose to $782.4 million from $696.3 million in June and $529.7 million a year ago. Special mention loans have roughly doubled from a year ago to $526.3 million, which management attributed to C&I borrowers facing consumer-demand and margin pressure. Loans 90 days past due and still accruing jumped to $53.2 million from essentially nothing in Q2. Net charge-offs did ease to 24 basis points from 26 and 30 basis points in the prior two quarters. Still, the migration trend points the wrong way. Elsewhere, mortgage rates near 7% pushed period-end mortgage finance balances down 15% sequentially. Full-year average guidance was cut to about $5.5 billion from about $6 billion, with Q4 averaging roughly $4.5 billion. CRE continues to shrink, and deposits fell 4% as brokered funding ran off. The expense guide moved up to mid-to-high single-digit growth. Management also guided Q4 fees down to $70-75 million and Q4 NII flat at $270-275 million, so this quarter may mark a near-term peak rather than a new run-rate.
Capital return remains a support. The company bought back about 1.05 million shares for $103.0 million at an average of $96.99, and the board authorized a new $200 million program. CET1 held at 12.2%. Book value per share slipped to $75.13 from $77.01, however, on a larger AOCI loss and the buybacks.
The market setup is more complicated than the surprise implies. Investor sentiment entering the report had swung meaningfully from roughly neutral (-0.02) to clearly positive (+0.33). The stock had moved the other way. Shares were at $91.06, down 7.6% since the open after the July report. That left them about 7.6% below the 200-day moving average of $98.51 and only 3.8% above the October 14 inter-earnings low of $87.75. Price and AVWAP trend readings remain negative. The company's own buyback price sits above where the stock now trades.
The bottom line is that Texas Capital delivered a high-quality operating beat and a credible guidance raise, driven by fees and margin. Balance-sheet growth contributed little. That fee-led growth story now has to outrun rising criticized loans, a contracting mortgage warehouse, a heavier expense budget and a softer fourth-quarter guide. Improving sentiment suggests investors are leaning toward the growth narrative, but a stock trading near its quarterly lows shows the market has not yet resolved that tension.
Read our earnings preview for Texas Capital Bancshares, Inc.: https://www.earningswhispers.com/article/TCBI/20487
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Oct-01 | |
| Sep-16 | |
| Sep-14 | |
| Sep-14 | |
| Aug-18 | |
| Aug-18 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-13 |
