Ategrity Posts Record 84.7% Combined Ratio, But Investment Losses Drive A Wide EPS Miss And Premium Growth Slows Sharply
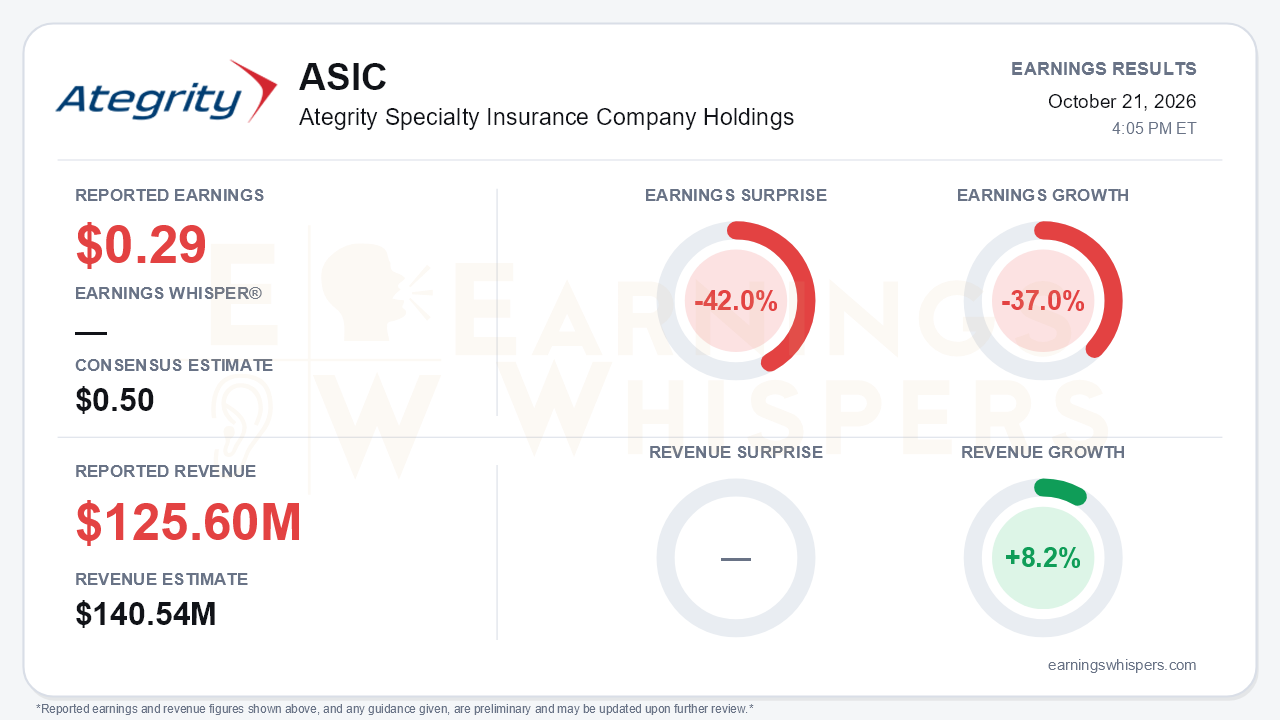
Ategrity Specialty Insurance Company Holdings (NYSE: ASIC) delivered two very different stories in the third quarter. The insurance operation had the best underwriting quarter in its history. The overall results were a clear miss. EPS of $0.29 fell 42.0% short of the $0.50 consensus and was down 37.0% year over year. Revenue of $125.6 million missed the $140.54 million estimate by 10.6%, although it still grew 8.2%. Most of the miss traces to a single line: $17.2 million of realized and unrealized investment losses, tied to the company's utility and infrastructure holdings. The more consequential issue for the investment case is not that mark-to-market hit. It is that premium growth decelerated sharply and management trimmed its growth outlook again.
The quality of the miss deserves careful parsing. Underwriting income rose 83.7% to $19.5 million. The combined ratio fell to a record 84.7%, from 88.7% a year ago and 85.9% in Q2. Both the loss ratio and the expense ratio improved:
- The loss ratio fell 2.5 points to 57.5%.
- The expense ratio fell to 27.2% from 28.7%.
Net earned premiums climbed to $127.1 million from $93.7 million, and net investment income rose to $13.1 million. Pre-tax income, however, roughly halved to $14.6 million once the investment swing hit. A $3.5 million loss allocated to the general partner's non-controlling interest cushioned the result attributable to stockholders. On a sequential basis, the earnings decline is stark: adjusted EPS slid to $0.29 from $0.67 in Q2 and $0.51 in Q1. There was also a hit to equity. Other comprehensive income absorbed a $21.5 million unrealized loss, which left comprehensive income negative. Book value per share slipped to $13.72 from $13.86 at the end of Q2, though it remains up 7.4% from year-end.
The top line is where the narrative shifted. Gross written premiums rose 14.7% to $165.0 million. That compares with 23.4% growth in Q2, 23.1% in Q1, and 30% in Q4 of last year. It also fell short of the Q2-call target of growing more than 20 points above the E&S market. Property was the bright spot: growth accelerated to 25%, from 21.3% in Q2 and 13% in Q1, helped by Midwest and New England expansion. Casualty was the problem. Growth collapsed to 10%, from 24.7% in Q2 and 38% two quarters earlier. Management attributed the slowdown to three factors:
- first-mover rate increases on redesigned, expanded-coverage casualty forms, which lowered conversion;
- a temporary productivity drag from the next-generation platform rollout;
- delayed underwriter start dates.
Submissions grew 30%, which is respectable but far below the roughly 90% cited at the end of last year. Management's tone turned more defensive in Q&A around the casualty pricing decision.
Guidance moved in opposite directions. Management lowered its Q4 growth target to 15–20 points above the E&S market, from more than 20 points previously. It framed part of that change as a cushion against volatile stamping data. At the same time, it guided the Q4 combined ratio below 87%, better than the roughly 87% guide for Q3. In effect, Ategrity is choosing rate adequacy over volume, which is defensible underwriting but a different growth profile than investors had been paying for. Potential offsets exist. Four specialty products launched in four weeks, and management says none of their upside is in the plan. The new platform should lift quote throughput in Q4. Management also plans to raise the fixed-income allocation to about 90% from about 80%, which should reduce the investment volatility that drove this quarter's miss. Capital return is another lever: $47 million of buyback capacity remains, and management intends to repurchase shares in Q4 after buying none in Q3.
The market setup makes the report more awkward. Shares closed at $27.60 ahead of the release, 12.5% above the opening price following the July report. That left the stock 24.6% above its 200-day moving average and within 4.8% of the $29.00 52-week high set in mid-September. The stock rallied during the quarter even as investor sentiment stayed negative, improving only marginally from -0.444 to -0.420. The Earnings Whispers trend readings on momentum and AVWAP were positive heading in. A stock priced near its highs leaves less room for a growth reset, and bears now have legitimate ammunition on casualty momentum and guidance credibility.
The bottom line is that Ategrity's underwriting engine has never looked better, and the headline EPS miss is largely an investment-mark story that the portfolio shift should help contain. But the growth deceleration, the missed growth target, and a second consecutive reduction in market-relative guidance change the debate. That debate is moving from how fast Ategrity can compound to whether casualty growth recovers once the repricing and platform transition settle.
Read our earnings preview for Ategrity Specialty Insurance Company Holdings: https://www.earningswhispers.com/article/ASIC/20497
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-14 | |
| Aug-18 | |
| Jul-30 | |
| Jul-29 | |
| Jul-23 | |
| Jul-10 | |
| Apr-30 | |
| Apr-30 | |
| Apr-29 | |
| Apr-16 | |
| Mar-10 | |
| Mar-03 |
