PTC Therapeutics Must Show Sephience-Style Momentum Holds As Shares Slide Despite Third Guidance Raise
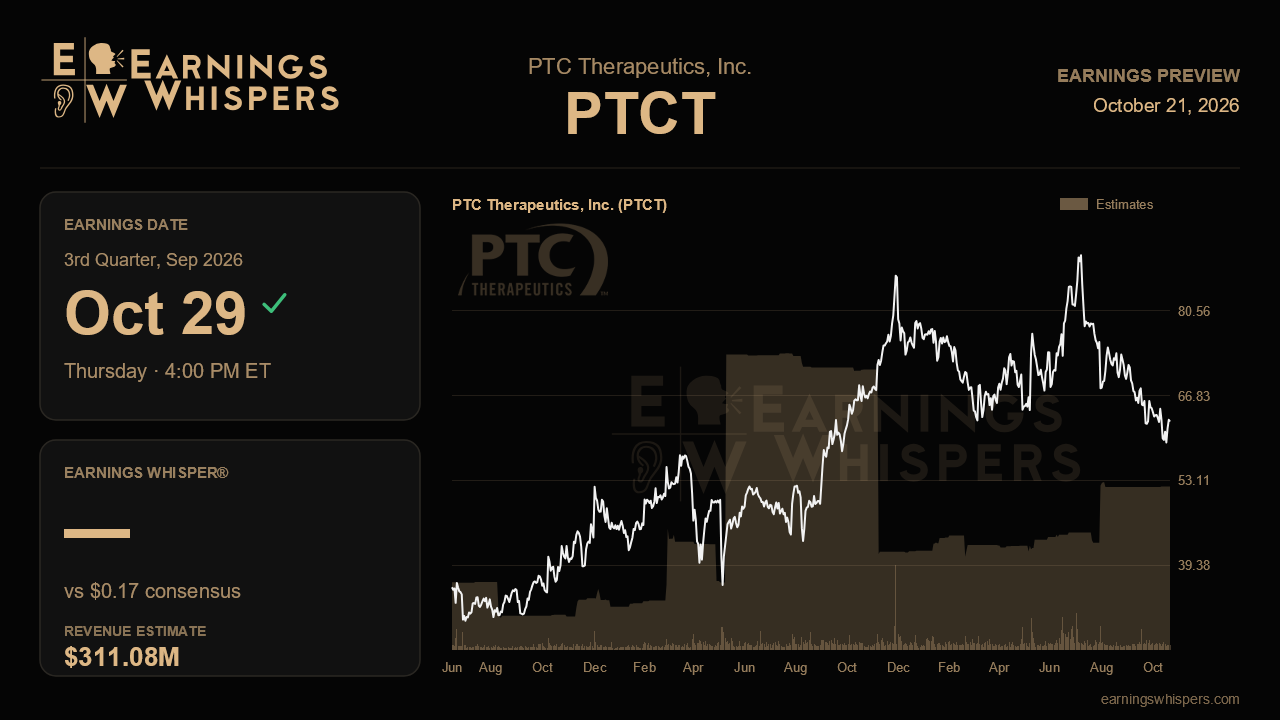
PTC Therapeutics heads into its third-quarter report with an odd disconnect. Management has raised its 2026 outlook three quarters in a row on the strength of its Suffiance launch in PKU, yet the stock has fallen 11.7% since the last report, trailing the S&P 500 by more than 15 percentage points. The results due after the close on October 29 need to show whether the market is wrong to doubt the growth story, or whether it is pricing in a plateau the company has not yet admitted to.
The Street is looking for earnings of $0.17 a share on revenue of $311.1 million. That would be a 47.4% jump in revenue from a year ago but a 15% drop in per-share profit, and a step down from the $360.5 million and $0.92 posted last quarter. The sequential decline is less alarming than it looks. Roughly $121 million of last quarter's revenue came from sources other than product sales, and analysts appear unwilling to assume that repeats. The cleaner measure is net product revenue, which reached $239 million in the second quarter. More telling still, the full-year consensus of $1.15 billion sits below the bottom of management's freshly raised $1.18 billion to $1.28 billion range. Either analysts are skeptical of the guidance or their models have not caught up. A quarter that keeps the company on track for its range would force estimates higher.
Suffiance is the variable that matters. Global sales climbed from $19.6 million at launch to $92 million, then $125 million, then $151 million last quarter, with commercial patients reaching 1,647 and every US Center of Excellence now prescribing. That breadth is impressive, but it also means the easy gains from new prescribing centers are largely captured. Growth from here depends on deeper use within those centers, Japan, where pricing matches the US and is locked for a decade, and paid early access in France, Italy, Spain and Latin America. A sequential increase in the mid-teens percentage range would validate the narrative. A flattening in patient additions would challenge it, especially since the discontinuation rate drifted up to about 20% from the low double digits cited earlier. Management called that near steady state; this quarter should show whether that claim holds.
There is also a subtle math point in the product guidance. The company expects $850 million to $950 million in 2026 product revenue, and first-half sales totaled about $465 million. The midpoint implies second-half quarters averaging around $218 million, below the second-quarter run rate. That suggests either conservatism or meaningful assumed erosion in the DMD franchise, where Emflaza faces multiple generics and Translarna orders are lumpy. Evidence that DMD continues to prove more durable than feared would make the guidance look beatable. Updates on Germany pricing, now pushed to the second half from a summer target, and on Italian and Spanish health technology reviews will also help gauge the international ramp.
Beyond the numbers, the company owes investors progress on its plan to engage the FDA with Novartis on a possible accelerated path for vodoplam in Huntington's disease, the start of the PROVE-FA vatiquinone study, and a clearer read on reaching cash-flow breakeven this year, backed by $2.23 billion in cash.
Sentiment has cooled to 18.3% bullish from 24.6% before the last report, and the stock, at $62.62, sits below its 200-day moving average of $71.22 and near the bottom of its post-earnings range of $58.80 to $75.00, a full tier lower than the prior quarter's $67 to $91 band. Expectations have reset downward. The central question is simple: if Suffiance growth keeps compounding while discontinuations stabilize, the guidance raises look credible and the selloff looks premature. If the launch curve bends, the market's skepticism will have been early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-15 | |
| Oct-06 | |
| Sep-30 | |
| Sep-25 | |
| Sep-21 | |
| Sep-04 | |
| Aug-27 | |
| Aug-24 | |
| Aug-17 | |
| Aug-13 | |
| Aug-12 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 |
