Pinterest Must Prove Its North American Rebound Can Outlast A Mechanically Softer Third Quarter
Pinterest finally gave the bulls something concrete last quarter. After three calls spent explaining a monetization gap, retailer and tariff pressure and a sales overhaul that was still disrupting the business, the company reported that US and Canada revenue growth had jumped to 18% from 13% the quarter before and 9% the quarter before that. Management also lifted its full-year adjusted EBITDA margin target to roughly 30%. The report due after the close on October 29 is the first test of whether that inflection was a turning point or a single good quarter, and it arrives with headline growth that is set to slow on paper.
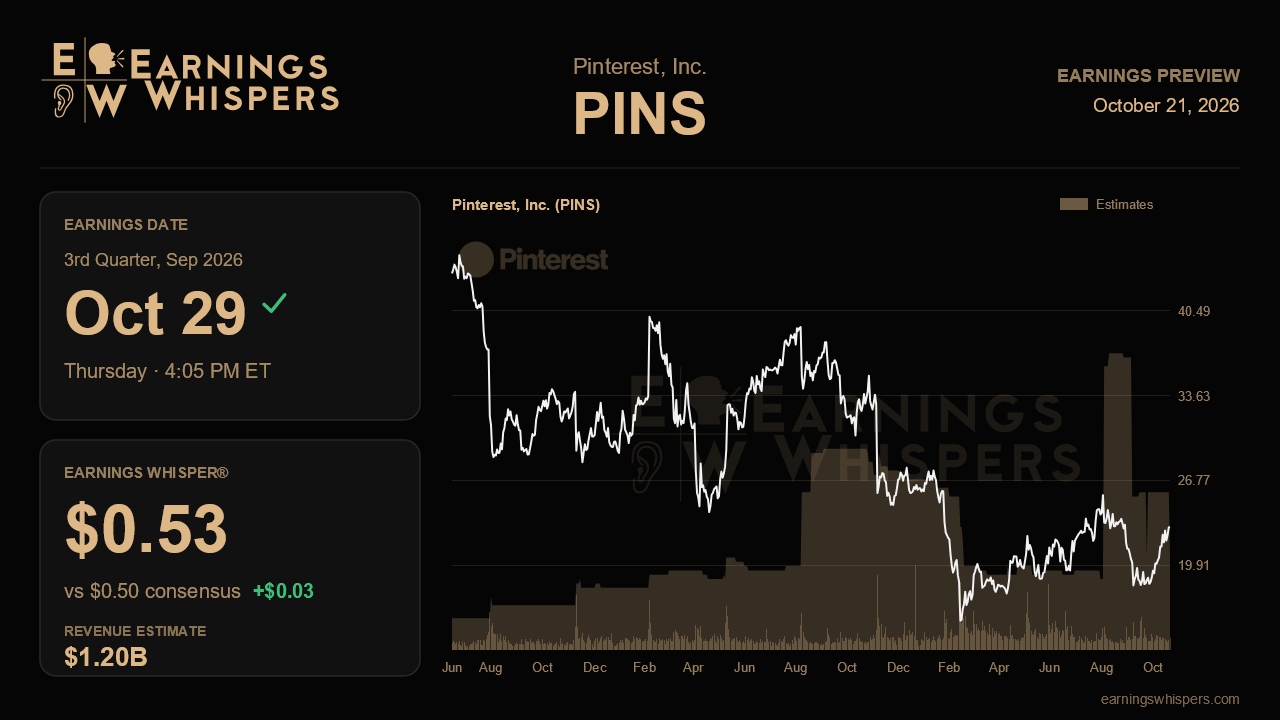
Wall Street expects non-GAAP earnings of $0.50 per share on revenue of about $1.20 billion, which would be roughly 14.4% growth from the $1.05 billion reported a year ago. That is a clear step down from the 18% pace of the second quarter, but it matches management's own outlook almost exactly. The company guided to $1.195 billion to $1.21 billion, and consensus sits comfortably inside that range, a touch below the midpoint. The whisper number of $0.53 is modestly above consensus, suggesting the more engaged crowd expects Pinterest to clear the bar on profitability again, as it did when second-quarter EBITDA beat guidance. Pinterest also topped its own second-quarter revenue range by a wide margin, so a result merely at the midpoint could feel underwhelming.
The deceleration needs context. Management attributed about three points of the slowdown to mechanical factors: a currency headwind, the shift in timing of Amazon's Prime Day and the absence of World Cup spending. Strip those out and underlying growth looks closer to the second quarter's pace. The key evidence will be North America. If UCAN growth holds in the mid to high teens, it would confirm that improvements in return on ad spend, the AI bidding and first-party measurement pilot that management credited for part of the second-quarter beat, and the revamped go-to-market effort are durable. A sharp fade back toward the low teens would revive doubts that the sales transformation is truly paying off. Commentary on how many additional advertisers joined the bidding pilot during the quarter will matter as much as the revenue figure itself.
Europe is the known soft spot. Growth there fell to 12% from 27% as regulatory actions squeezed spending by Asia-based cross-border retailers, and management warned that pressure would persist while the third quarter presents the toughest European comparison of the year. International sales reorganization is also expected to remain disruptive. Investors should not be surprised by weak European numbers, so the more useful signal is whether management sees the cross-border drag stabilizing and whether the UCAN playbook is gaining traction under new international leadership. On costs, GPU capacity and the inclusion of TV Scientific will weigh on cost of revenue in the back half, which makes delivery against the raised 30% margin target a meaningful test of discipline. Early engagement data from Pinterest Assistant, rolled out to most US users at the end of July, would add color to the longer-term story.
The market has not paid up for the improvement. Shares have fallen 4.3% since the last report, trailing the S&P 500 by nearly four points, even as sentiment has turned less bearish than it was heading into the prior quarter. At about $22.95, the stock sits above its 200-day moving average but roughly 8% below its post-earnings high of $25.06, leaving it in the middle of its range rather than near a breakout.
That gap between operating momentum and share performance frames the report. If North America keeps growing near its second-quarter pace and margins track toward 30% despite rising infrastructure costs, the softer headline growth should be read as noise. If UCAN cools meaningfully while Europe stays weak, the inflection narrative will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-19 | |
| Oct-17 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 |
