Pinterest Misses Its Own Guide As Growth Slides To 12%, Ending The Re-Acceleration Story Despite Record Users
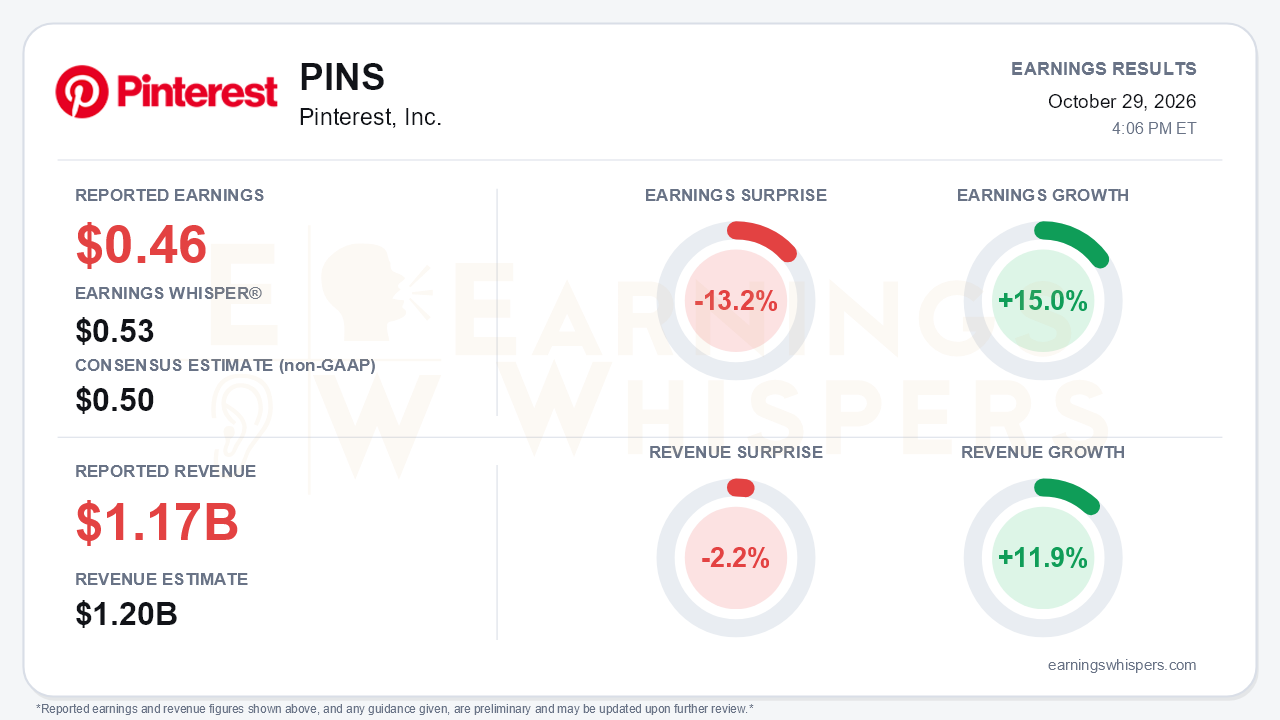
Pinterest's third quarter broke the re-acceleration narrative that carried the stock through the first half. The company earned $0.46 per share on a non-GAAP basis, missing the $0.50 consensus by 13.2% and falling well short of the $0.53 Earnings Whisper number. Revenue of $1.174 billion missed the $1.20 billion consensus by 2.2% and landed below management's own guidance of $1.19 billion to $1.21 billion, or 13% to 15% growth. Year-over-year earnings growth of 15.0% and revenue growth of 11.9% look respectable in isolation. The trajectory is the problem: revenue growth fell from 18% in Q2, and the fourth-quarter outlook of $1.425 billion to $1.475 billion, or 8% to 12% growth, came in below estimates and implies further deceleration. That is the central development in the quarter.
The quality of the earnings line deserves scrutiny. Non-GAAP net income rose only 3%, to $270 million, so most of the 15% per-share growth came from a smaller share count. Diluted shares fell to 583 million from 695 million after roughly $2.0 billion of year-to-date buybacks, partly funded by a $980 million convertible note issue. The financing has a cost on the GAAP line. Net interest income fell to $6 million from $28.5 million as cash and marketable securities dropped by about $1 billion since December. A tax provision replaced last year's benefit. Together these cut GAAP net income 77%, to $22 million. Adjusted EBITDA of $339 million rose 11% and fell inside the $335 million to $355 million guide, but the 29% margin was down about 30 basis points from a year ago, after expanding 130 basis points in Q2. Share-based compensation climbed to $288 million from $235 million. Free cash flow slipped 6% year over year to $300 million, though it improved from $270 million in Q2.
The call explained where growth went. Management attributed the 6-point deceleration to three factors:
- about 3 points from cross-border sellers pulling back after the EU removed its de minimis exemption, a larger effect than forecast;
- about 2 points from Prime Day and World Cup timing;
- about 1 point from foreign exchange.
Europe took the worst of it. Revenue there was flat (+1% in constant currency), compared with +12% in Q2 and +27% in Q1, and European ARPU fell 7%. U.S. and Canada growth slowed to 14% from 18%, with softness in food, beverage and alcohol, and Rest of World growth cooled to 24% from 38%. Monetization efficiency also weakened: ad impressions grew 17% while ad pricing fell 4%. Management's tone changed accordingly, moving from describing "strong" quarters earlier in the year to saying it was "not happy with that result."
The user story held up, which keeps the longer-term case credible. Monthly active users reached a record 661 million, up 10%, the 13th consecutive record quarter. Management said U.S. engagement, including searches, boards and outbound clicks, is growing faster than users. Several new demand levers are emerging:
- programmatic partnerships with Google DV360, Amazon DSP and Yahoo DSP, covering roughly two-thirds of the DSP market;
- Visual Search Ads, a new format in beta;
- an app-install objective, also in beta;
- Pinterest Assistant, now generally available in the U.S., where about 80% of searches are commercial.
Management also said core European enterprise growth, excluding cross-border sellers, has re-accelerated quarter-to-date above its Q2 level. Pinterest reaffirmed its roughly 30% full-year adjusted EBITDA margin target.
Bears have legitimate ammunition, however. Management does not expect cross-border spending to return for the holiday season and described recovery timing as uncertain and potentially multi-quarter. Fourth-quarter cost of revenue is expected to rise at a low-teens rate sequentially on GPU investment. The international go-to-market restructuring is still settling in with many new leaders ramping. The finance function is also changing hands: CFO Julia Donnelly is departing, and James Dibbo, formerly CFO of Amazon's ads business, joined only days before the call. Widening the Q4 revenue range to a $50 million spread signals reduced visibility, even if management framed it as prudence.
The market had already priced in some disappointment. Shares closed at $19.92 ahead of the report, down 16.9% from the $23.98 open after the August release and about 4.2% below the 200-day moving average of $20.79. The AVWAP trend reading remains negative. Investor sentiment stayed negative but improved modestly, from -0.25 to -0.20, suggesting expectations were subdued rather than euphoric going in. A guide-down still lands poorly when the stock is already trading below its long-term average.
The bottom line is that Pinterest delivered a quarter where engagement and cash generation held up but the revenue engine stalled. The company missed its own guide, its per-share growth leaned heavily on buybacks, and its Q4 outlook points to growth potentially slipping into single digits. The new ad formats, DSP reach and early European recovery give management a path back. Until cross-border spending stabilizes and ad pricing firms, though, the burden of proof has shifted to execution.
Read our earnings preview for Pinterest, Inc.: https://www.earningswhispers.com/article/PINS/21231
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 7 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-19 | |
| Oct-17 | |
| Oct-16 | |
| Oct-15 | |
| Oct-13 |
