PennyMac Faces Proof Test On Cost Cuts And Recapture After Third Straight Guidance Reset
PennyMac Financial Services heads into its third-quarter report with a credibility problem that its operating metrics have not yet been able to fix. Management has trimmed its return outlook twice in three quarters, most recently guiding to high-single-digit adjusted returns on equity for the second half of 2026 and pushing its mid-teens target out to the exit of 2027. Meanwhile, recapture rates, servicing efficiency and automation have all been moving in the right direction. Thursday's release after the close is the first quarter in which the company's promised $60 million in annualized cost savings is supposed to show up, which makes it a referendum on whether the self-help story can start offsetting a punishing rate backdrop.
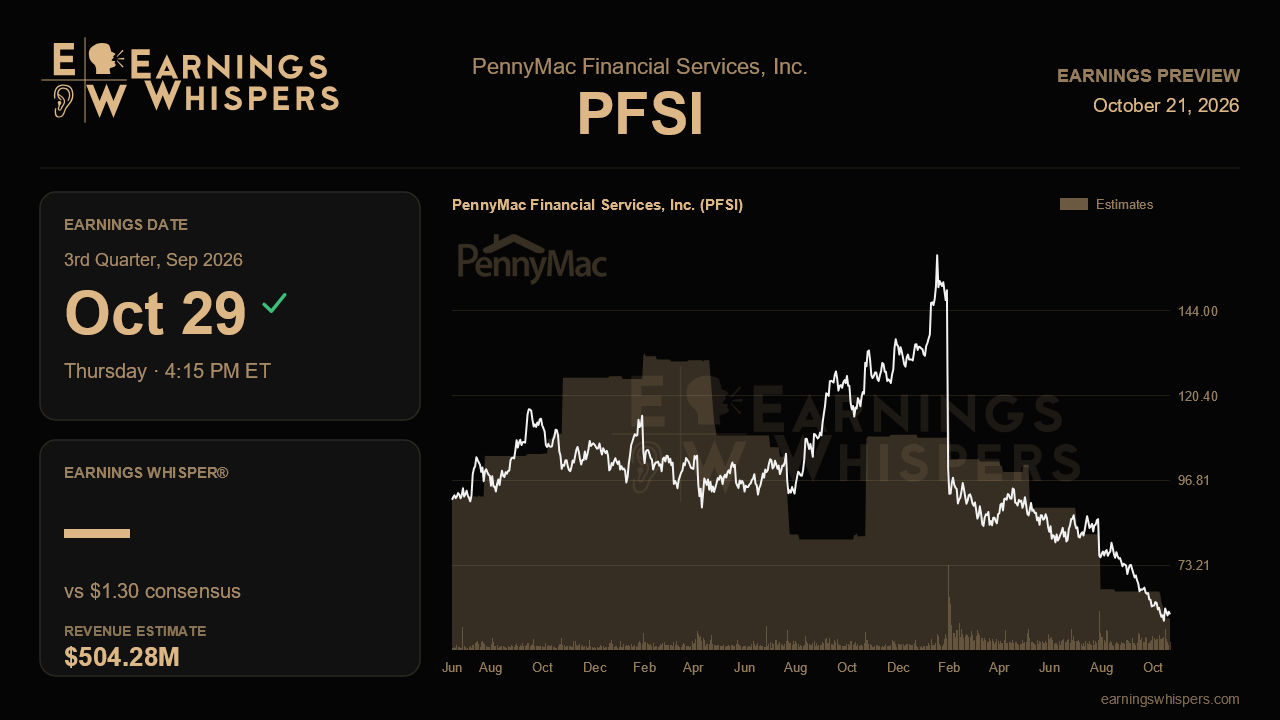
The Street is braced for a sharp year-over-year contraction. Consensus calls for earnings of $1.30 per share on revenue of $504.3 million, down roughly 61% and 20% respectively from the $3.37 and $632.9 million posted a year ago. Sequentially, though, the bar is nearly flat: last quarter delivered adjusted EPS of $1.39 on $497 million in revenue. That framing matters. Analysts are effectively assuming the business has found a floor, consistent with management's high-single-digit return guidance, rather than modeling further deterioration. A print meaningfully below the prior quarter would suggest even the reset outlook was too generous.
The biggest swing factor is the production segment, where pre-tax income collapsed to $38 million last quarter from $134 million as higher rates choked off refinance demand and Consumer Direct locks fell 32%. Validation would look like stabilizing lock volumes and evidence that the cost-to-produce reduction, targeted at more than 20% by the end of the third quarter, is landing. Broker Direct offers a modest bright spot, with margins rising to 104 basis points and non-QM locks tripling, though management has already abandoned its 10% share target there. In correspondent, the question is how much damage GSE cash-window competition and PMT's exit from agency-eligible conventional purchases have done to volumes.
Servicing is the other half of the equation, and the cleaner place to look for good news. Pre-tax income excluding valuation nearly doubled to $99 million last quarter, and continued strength there would support management's argument that the franchise is scaling. The caveat is hedging. Hedge costs ballooned to $52 million from $14 million the quarter before, producing a $77 million net MSR loss. Another quarter of costly hedge results would undercut the servicing improvement and reinforce concerns that rate volatility is overwhelming the model. Investors should also look for confirmation that the CENLAR subservicing acquisition remains on track to close in the fourth quarter, along with any early read on FHA modification rules dampening buyout activity.
The market has rendered a harsh verdict in the meantime. Shares have fallen 23.4% since the last report, trailing the S&P 500 by more than 28 percentage points, and at $59.53 they sit near the bottom of the post-earnings range of $57.52 to $80.38 and well beneath the 200-day moving average of $87.44. Sentiment has soured accordingly, with bearish readings rising to about 50% from 29% heading into the prior report. That pessimism arguably lowers the hurdle, since a steady quarter with tangible cost relief could be enough to ease fears, but another guidance cut would land on a stock with little technical support beneath it.
Ultimately, this report hinges on one question: can expense discipline and recapture gains hold earnings near last quarter's level without help from rates? If the cost savings appear, hedge costs normalize and management reaffirms its second-half and exit-2027 targets without another delay, the recovery narrative survives. A fourth consecutive step down in returns would make the 2027 goal look less like a plan and more like a moving target.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-05 | |
| Sep-08 | |
| Sep-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-17 | |
| Aug-13 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 |
